


Sanoma Oyj (HLSE:SANOMA) just delivered a third quarter in which net income and earnings per share roughly doubled year on year, while management also narrowed its 2026 net sales guidance range.
The share price around €8.81 tells a mixed story, with a 7 day share price return down 16.4% and the 30 day move lower by 9.2%, even though Sanoma Oyj’s 3 year total shareholder return is up 30.7% while the 1 year total shareholder return is down 13.3%.
Scan how Sanoma Oyj’s sharp earnings shift compares with other media and education players by reviewing our hand picked list of 199 high quality undervalued stocks that combine resilient cash flows with stronger balance sheets.
Sanoma Oyj just paired a jump in profitability with a sliding share price. The business looks resilient. The open question is whether the current valuation already reflects that strength or leaves a margin of safety.
Most Popular Narrative: 29% Undervalued
Sanoma Oyj’s most followed narrative pegs fair value at €12.34, compared with the recent €8.81 share price. This suggests a sizeable valuation gap that depends on curriculum driven growth, digital learning and balance sheet repair actually playing out.
Curriculum-driven expansion in K12 learning, including recent acquisitions of Vicens Vives in Spain and Fluentbe in Poland, is widening Sanoma Oyj’s content portfolio and digital reach across large European school and tutoring markets. This can support sustained Learning net sales growth and maintain the segment’s adjusted operating margin above 23%.
See why 6 investors see Sanoma Oyj as 29% undervalued.
Result: Fair Value of €12.34 (UNDERVALUED)
Still, this bullish Sanoma Oyj narrative relies on the tough ad market in Finland not worsening further and on ambitious earnings targets for 2029 actually being met.
Find out about the key risks to this Sanoma Oyj narrative.
Another Take On Sanoma Oyj’s Valuation
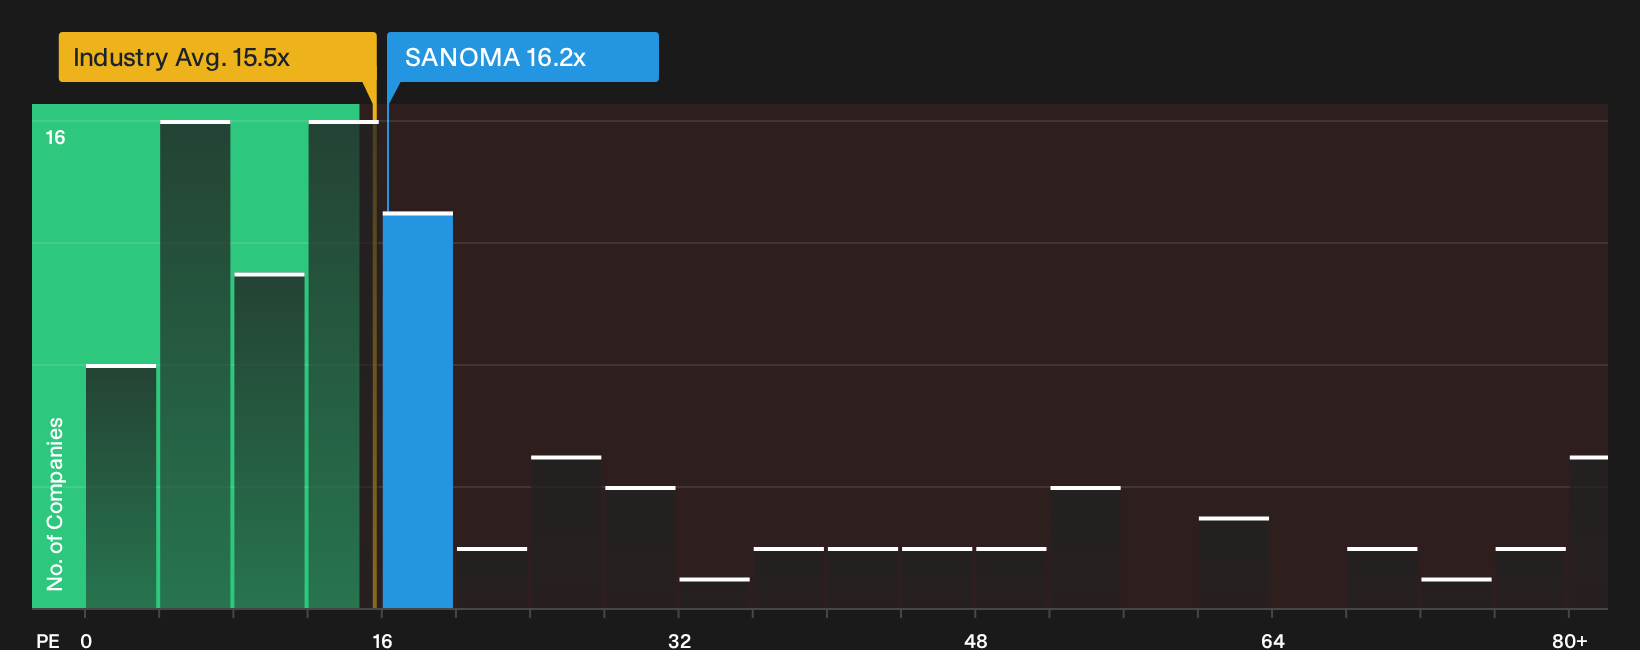
The first narrative leans heavily on analyst targets and future earnings. A second lens is simple multiples. Sanoma Oyj trades on a P/E of 16.2x, above both its peer average of 14.4x and a fair ratio of 28x that our modelling suggests the market could eventually move toward.
This mix of higher pricing than peers but a much lower level than the fair ratio points to a tug of war between caution and optimism. It raises a clear question for you as an investor: does that gap signal extra valuation risk or a potential opportunity if sentiment shifts?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Does the mix of stronger earnings and a volatile share price around Sanoma Oyj leave you feeling cautious or curious? Act quickly and review both sides of the story by weighing the 4 key rewards and 2 important warning signs
Looking For More Investment Ideas Beyond Sanoma Oyj?
If Sanoma Oyj has you thinking harder about value and quality, do not stop here. Broaden your watchlist with focused ideas built from clear fundamentals.
- Target stability first by reviewing a list of solid balance sheet and fundamentals (203 results) that can help you focus on companies with stronger financial footing.
- Hunt for mispriced quality and scan a 603 high quality undiscovered gems that may not yet be widely followed by the broader market.
- Prioritise resilience in choppy periods and study a 218 resilient stocks with low risk scores that filters for businesses with lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com