


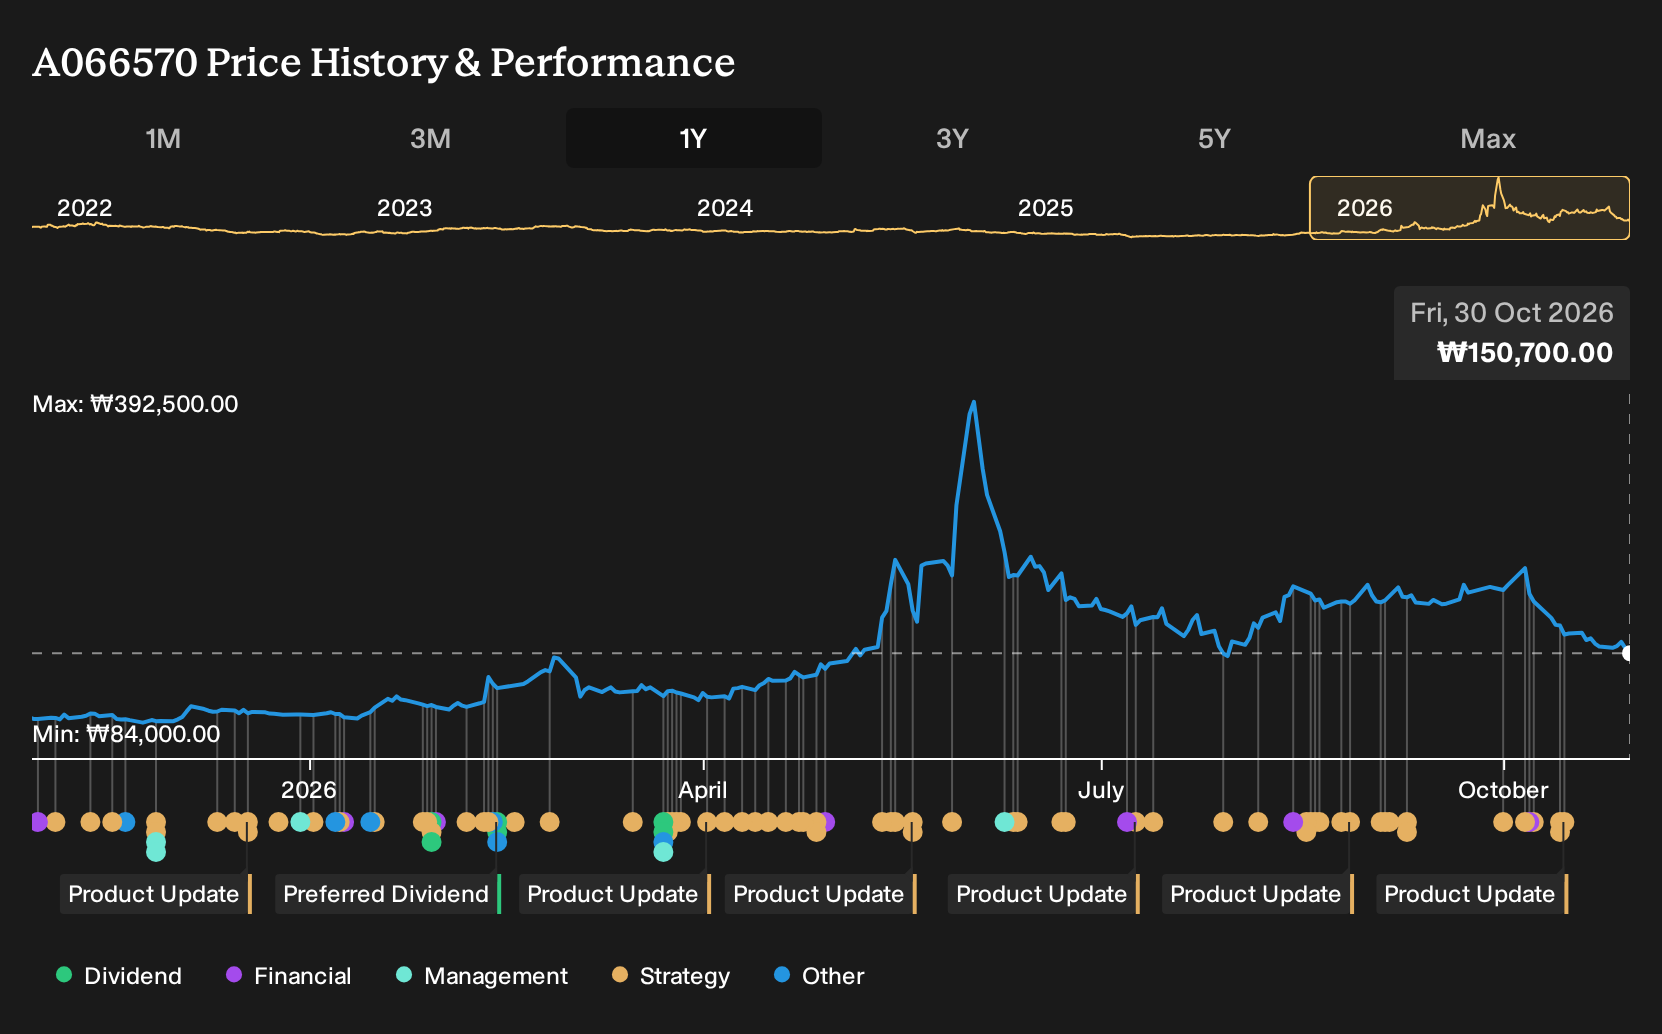
If LG Electronics was on your watchlist instead of in your portfolio, the recent performance may feel expensive in hindsight. For LG Electronics shareholders, the return over the past year was 73.8%, including dividends. That outcome invites a simple question. Back on 30 October 2025, when analysts were arguing over whether modest revenue growth and a higher profit margin were realistic, what signals could have helped you judge if those margin assumptions were credible before the move happened?
LG Electronics has already moved. Pinpoint other ways to investigate the theme among 54 AI infrastructure stocks.
The Two Stories LG Electronics Investors Were Choosing Between
The shares cost ₩87,900 at the start of the period, and LG Electronics sat between two very different but plausible stories about where the business could go next.
On the optimistic side, the bullish view put Fair Value at ₩95,865, essentially the price implied if modest revenue growth of 3.3% a year and a profit margin rising to 2.5% played out alongside a 9.6x future P/E assumption.
The cautious camp pointed to a Fair Value of ₩77,500 and focused on risks such as rising US tariffs and aggressive Chinese competition that could leave revenue growth closer to 2.8% with only a small move in margins to 1.1%.
What The Results Changed For LG Electronics
The most concrete evidence arrived in Q2 2026 when LG Electronics reported revenue of ₩23,826,468m compared with ₩20,735,142m a year earlier, while net income was almost flat at about ₩605,000m and net margin slipped from 2.9% to 2.5%. That pattern supported the cautious case on profitability, even as it aligned more with the optimistic story on the top line.
The useful takeaway is simple. When a thesis leans on margin expansion, treat net margin as the key claim to test and track it quarter by quarter against the original assumption.
What Today's LG Electronics Price Already Assumes
LG Electronics now trades at ₩150,700. The selected Narrative’s Fair Value sits below that level and suggests that today’s price already reflects a significant amount of anticipated success from B2B, premium hardware and newer profit streams.
The key question is what has to continue working. A buyer today would need confidence that B2B, AI data center cooling and automotive electronics can compensate for weak appliance and TV demand without eroding profitability through higher costs.
"Although LG Electronics is leaning into B2B and subscription services for "qualitative growth," persistent reports of flat to only modestly recovering global demand for core appliances and TVs mean these newer lines may need to carry more of the load than initially assumed. This creates a risk of slower consolidated revenue growth if subscriptions and B2B do not scale fast enough to offset weak consumer hardware volumes."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Before The Next Story Makes Headlines
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 46% below our estimate - supplies high voltage and subsea cables utilities depend on for grid renewal.
- Company 2 - 31% below our estimate - assembles commercial aircraft emerging from a long running multi country industrial partnership.
- Company 3 - 37% below our estimate - shifts steel production toward electric arc furnaces and higher margin downstream contract work.
Three companies from the same screener. Open the full list of 199 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com