


- Tanabe Pharma filed a marketing authorization application in Japan on 29 October 2026 for ZYNLONTA, a CD19-directed antibody drug conjugate, and granted Nippon Shinyaku exclusive sublicensing rights to commercialize MT-2111 for relapsed or refractory diffuse large B-cell lymphoma after at least two prior systemic therapies.
- The sublicense positions Nippon Shinyaku to expand its oncology portfolio with a first in class lymphoma therapy. Tanabe Pharma continues to handle development and regulatory responsibilities, creating a focused split between commercialization and clinical execution in the Japanese market.
- Next comes a look at how Nippon Shinyaku's exclusive commercialization role for ZYNLONTA in Japan could reshape its broader investment narrative.
What Is Nippon Shinyaku's Investment Narrative?
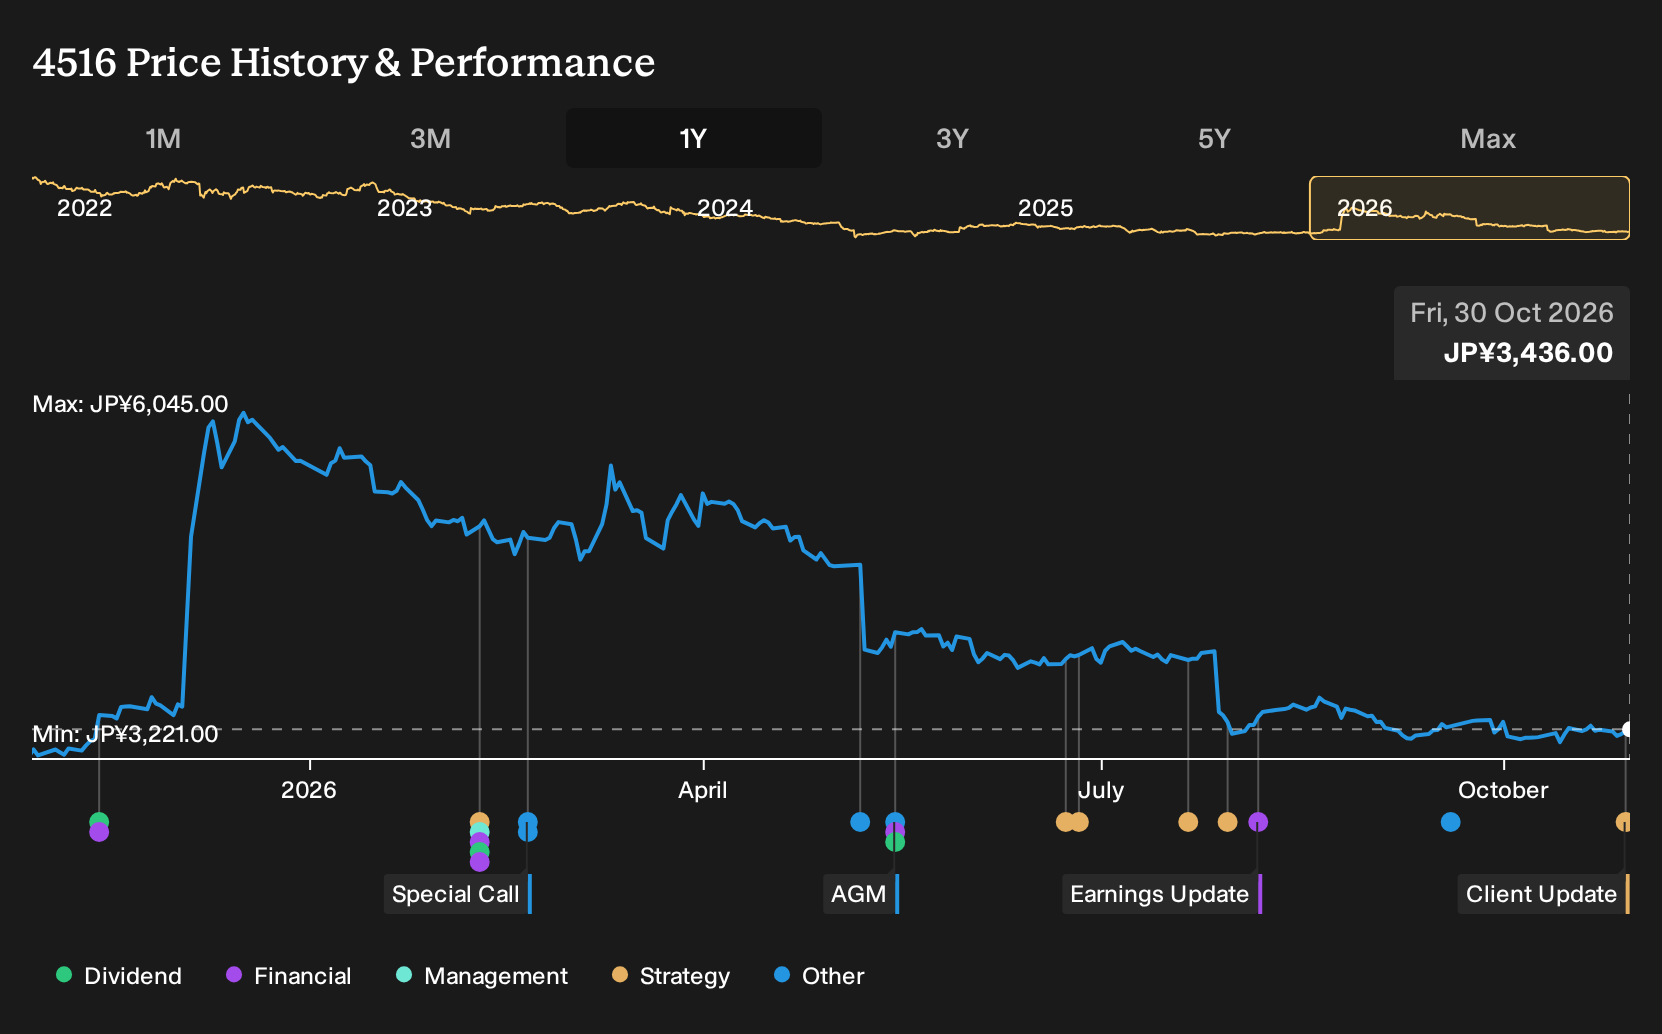
Owning Nippon Shinyaku means buying into a mid sized pharma group that blends a urology and rare disease franchise with a smaller but growing oncology effort and a steady functional food business. The ZYNLONTA sublicense leans into that oncology ambition without loading the balance sheet with heavy development spend, since Tanabe Pharma retains clinical and regulatory duties. For a shareholder, the near term story still revolves around stabilising earnings, which recently declined year on year, keeping dividend reliability near its current 3.61% level and considering whether the current P/E of 7.3x reflects caution rather than a structural reset.
The ZYNLONTA deal could matter for sentiment if approval lands smoothly in Japan and commercial execution is clean, because it offers a fresh, clearly defined product launch in an area of high medical need. In the short term it does not change forecasts that call for revenue and profit contraction over the next three years, and it does not address issues such as low forecast return on equity or management’s relatively short tenure. That mix of valuation, income profile, pipeline potential and operational questions defines the broad thesis an investor needs to be comfortable with when holding Nippon Shinyaku.
Even so, there is a harder question around the sustainability of that story if...
There's only one way to know the right time to buy, sell or hold Nippon Shinyaku. Head to Simply Wall St's company report for the latest analysis of Nippon Shinyaku's Fair Value.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Nippon Shinyaku research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Nippon Shinyaku. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nippon Shinyaku's overall financial health at a glance.
Looking For More Investment Ideas Beyond Nippon Shinyaku?
If you want to put Nippon Shinyaku in context, it helps to line it up against other opportunities. The Simply Wall St Screener can surface focused shortlists that match the kind of risk, income or value profile you care about most.
- For income focused investors who want yield with an eye on resilience, scan a curated set of 27 dividend fortresses that may help anchor the more volatile parts of your portfolio.
- If capital preservation and steadier business profiles sit higher on your priority list, filter for 24 resilient stocks with low risk scores that may offer a calmer ride through market swings.
- When you are hunting for under the radar ideas with strong fundamentals, use the screener to surface 71 high quality undiscovered gems that might not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com