


Conestoga Capital Advisors’ exit from Hillman Solutions (HLMN) has put fresh attention on how much of the hardware supplier’s growth now leans on acquisitions and new business wins.
Hillman Solutions’ share price has climbed 8.33% over the past week and 11.59% over the past month, yet it remains down 10.45% year to date, with a 1 year total shareholder return that is 15.40% lower and a 5 year total shareholder return that is 27.84% lower. This points to short term momentum building against a weaker longer term record as investors weigh acquisition driven growth against higher leverage and softer margins.
Scan 29 high quality undervalued stocks that, unlike Hillman Solutions, combine acquisition stories with stronger balance sheets and margins, which may better support the kind of rerating investors often look for.For Hillman Solutions, a short burst of gains after a tougher stretch can signal either a business quietly turning a corner or traders simply rotating back in. The valuation work starts by separating those two stories.
Most Popular Narrative: 35% Undervalued
Hillman Solutions last closed at $7.80, while the most followed narrative centers on a fair value estimate of $12.00 using a 9.87% discount rate. That gap frames the current debate over whether the recent share price rebound is simply a bounce or the start of investors warming to its earnings story.
The main thing that has to go right is that Hillman turns its expanded Pro and industrial presence, high margin Robotics & Digital Solutions, and new distribution investments into sustained earnings growth that materially improves margins and returns on invested capital from the levels investors have questioned.
The numbers imply the share price reflects skepticism that Hillman’s long-term revenue growth, margin trajectory, and ROIC targets through 2030 will be met, even after record 2025 results, raised 2026 guidance, and continued investment in Pro channels and automation, which this narrative views as leaving the stock undervalued.
See why 1 investors see Hillman Solutions as 35% undervalued.
Result: Fair Value of $12 (UNDERVALUED)
Still, the Hillman Solutions story can unravel if weakness in Protective Solutions drags on or if margin targets slip as tariff related pricing support fades.
Find out about the key risks to this Hillman Solutions narrative.
Another View: Multiples Paint A Tougher Picture For Hillman Solutions
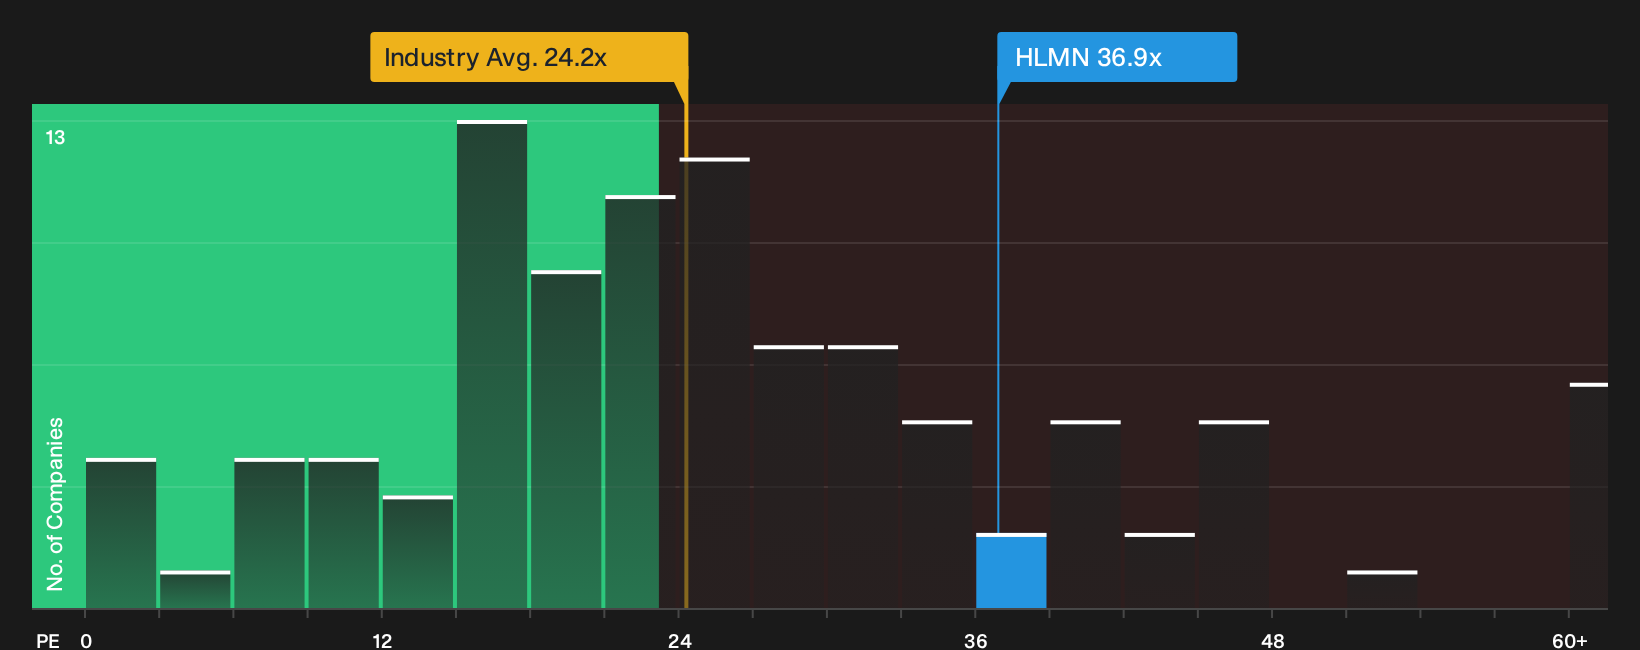
Hillman Solutions might appear inexpensive relative to a $12 fair value narrative, yet on basic earnings measures it does not. The stock trades on a P/E of 36.9x, which is higher than both the US Machinery industry at 24.8x and its own fair ratio of 28.2x, leaving less room if expectations slip.
This higher P/E suggests investors are already paying a premium for the earnings story, and any setback in margins or cash generation could weigh on sentiment more quickly than a pure DCF view implies. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Hillman Solutions rarely stay mixed for long. Consider acting promptly, review the data yourself, and weigh the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Hillman Solutions?
If Hillman Solutions has sharpened your focus on valuation, use that momentum to hunt for other opportunities where the numbers and story line up more cleanly.
- Target sturdier balance sheets and cash flows by reviewing the list of solid balance sheet and fundamentals (25 results) to help anchor your portfolio when sentiment swings.
- Hunt for potential mispricings in quality businesses using the 29 high quality undervalued stocks so you do not miss companies trading below their fundamentals.
- Stack potential income ideas on top of your growth picks by scanning the 5 dividend fortresses to aim for a blend of yield and financial resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com