


Argus recently reduced its target price for Harmonic (HLIT) to US$10.00. This has put fresh attention on how the broadband access specialist’s fundamentals line up with expectations at a recent close of US$10.23.
Recent trading has been choppy for Harmonic, with the share price falling 5.28% in the last session and down 11.43% over 90 days. A modest 2.10% year-to-date share price return contrasts with a 1-year total shareholder return that is lower at a 4.39% decline, pointing to fading momentum despite earlier gains.
Contrast Argus’ reset on Harmonic with other potential opportunities by scanning a curated set of 29 high quality undervalued stocks that pair solid balance sheets with stronger valuation support.
Harmonic now trades only slightly above Argus’ revised target, yet still sits at a steep discount to the wider analyst and intrinsic value estimates. Is the market being fairly cautious, or is it mispricing this broadband player’s prospects?
Most Popular Narrative: 37% Undervalued
On the narrative view, Harmonic’s fair value sits at $16.14, well above the recent $10.23 close. This puts a spotlight on what needs to go right to close that gap.
Shift toward higher margin software and recurring broadband services is accelerating as Harmonic targets recurring revenue of 22% to 25% of total, including intelligence at about 10% of sales within three years, which can lift gross margin and support operating margins above 20%.
See why 17 investors see Harmonic as 37% undervalued.
Result: Fair Value of $16.14 (UNDERVALUED)
Still, the Harmonic narrative leans heavily on a few large broadband customers, and it assumes memory cost pressures do not squeeze margins for longer than planned.
Find out about the key risks to this Harmonic narrative.
Another View: How Harmonic Screens On Earnings
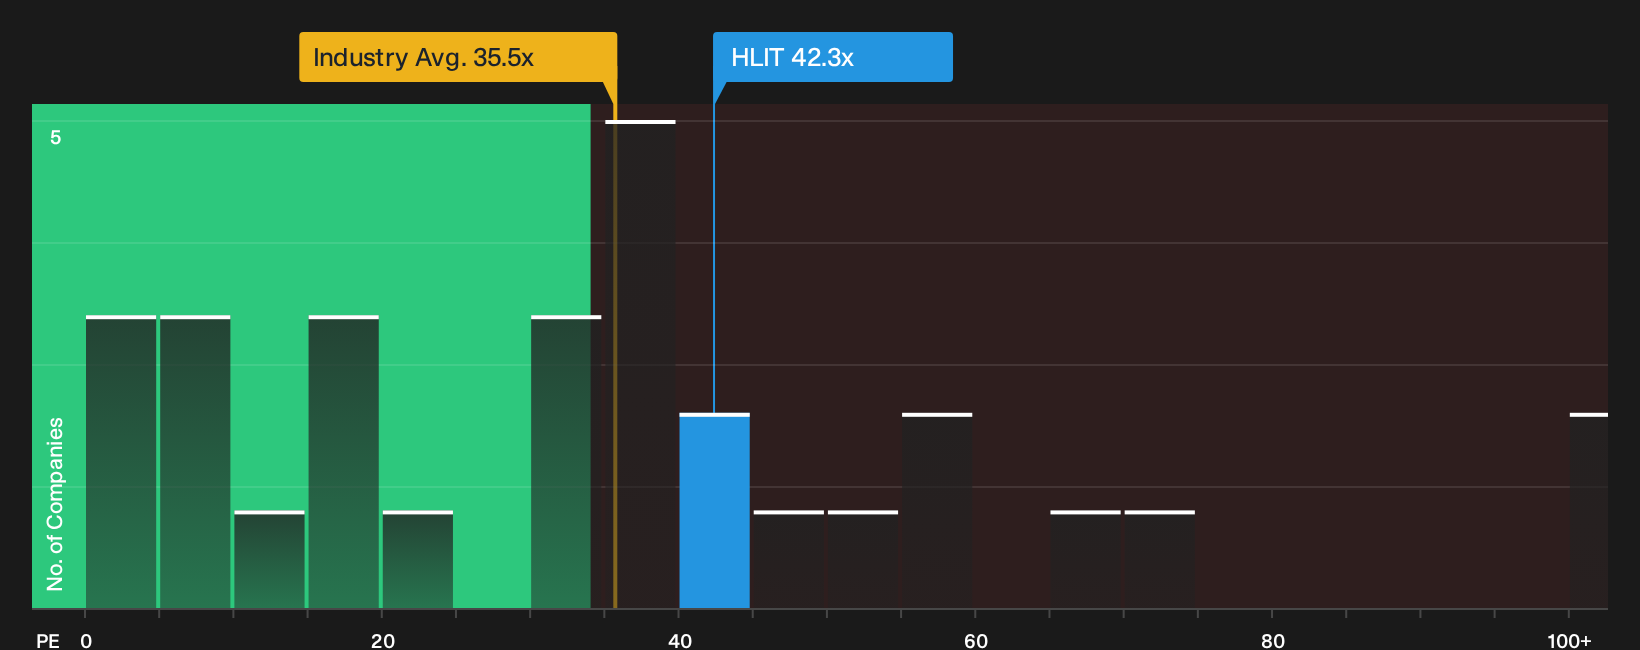
While the Simply Wall St fair value estimate suggests Harmonic is trading at a discount, its P/E ratio of 42.3x tells a more cautious story. That level is higher than the US Communications industry at 38.2x and above a fair ratio of 34.3x, which points to valuation risk if expectations slip. Which signal do you think the market adjusts to first?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on value and risk often create the sharpest opportunities. Move quickly, review the underlying numbers, and weigh the 2 key rewards and 1 important warning sign.
Looking For More Ideas Beyond Harmonic?
If you stop at Harmonic, you miss a wider field of potential opportunities. Run a quick screen now and compare what you see before the market moves.
- Target higher potential upside by scanning a curated 18 high quality undiscovered gems that many investors are not watching yet.
- Strengthen portfolio resilience by focusing on a list of solid balance sheet and fundamentals (25 results) that can better handle tougher conditions.
- Review a focused set of 5 dividend fortresses that aim to deliver income above 5%.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com