


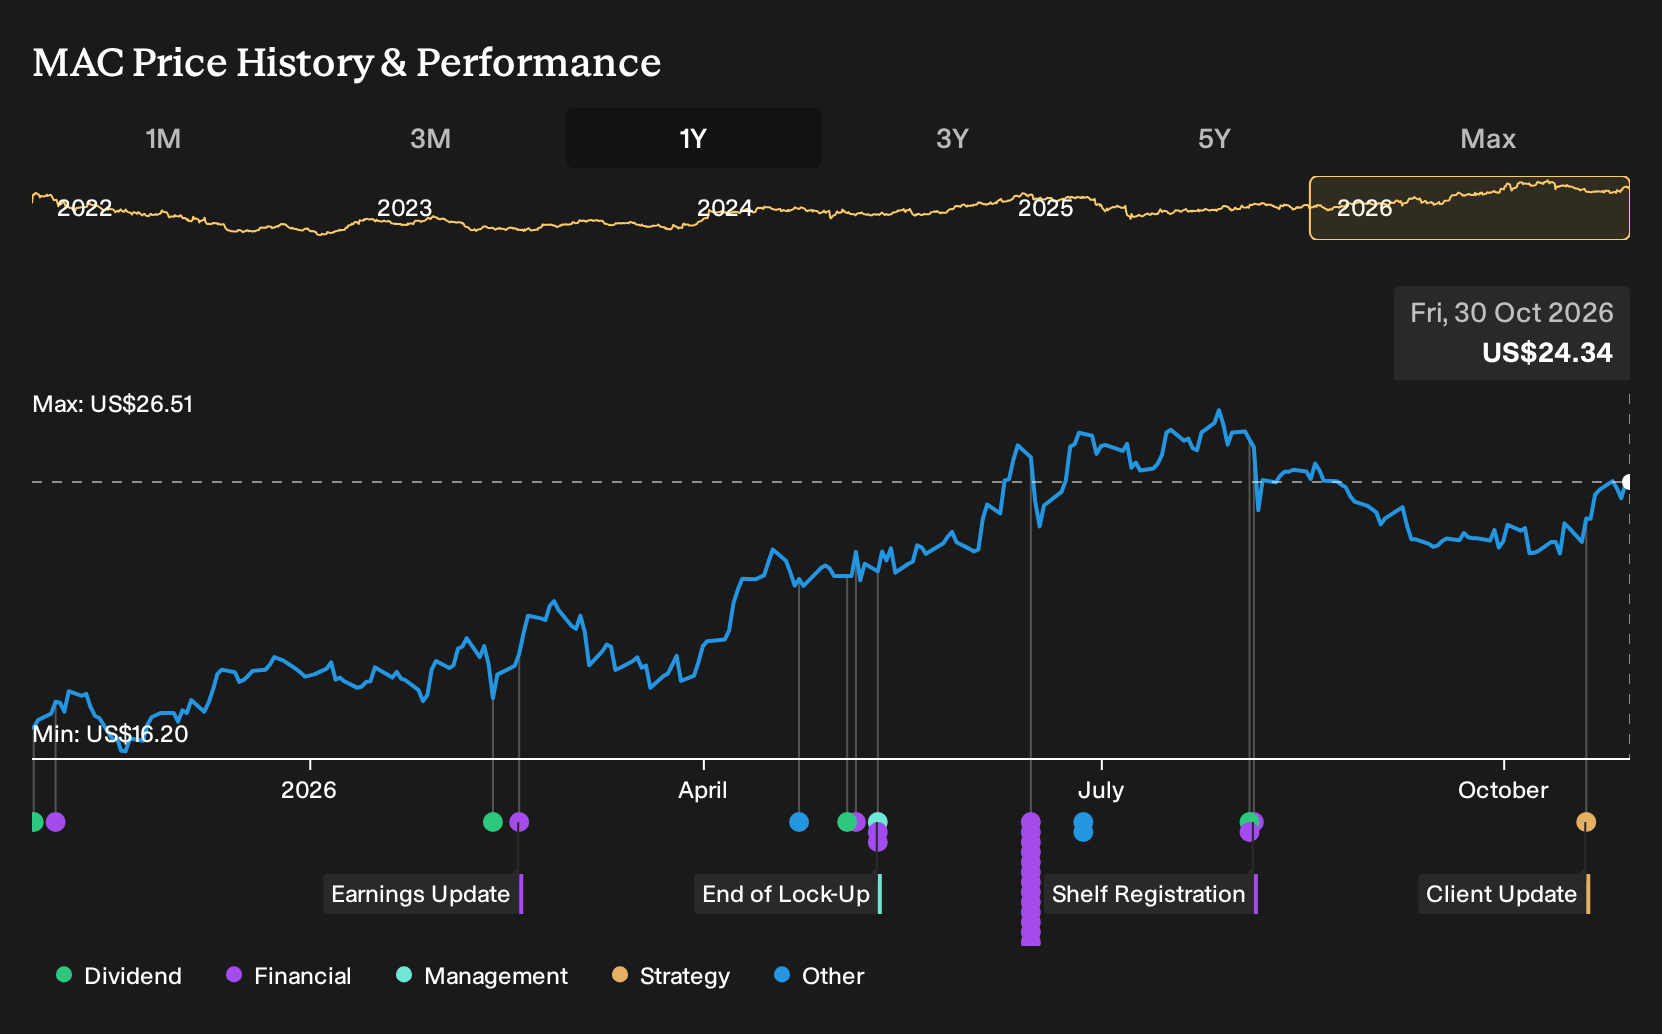
If you only skimmed Macerich headlines about high leverage, refinancing risk, and struggling mall tenants a year ago, a big gain might not have been the outcome you expected. Holding Macerich over the past year would have returned 46.6%, including dividends. If you had been weighing those concerns against bullish talk of experiential retail and urban assets back on 30 October 2025, what did that contrast really signal about the business you were underwriting?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
If the move has made Macerich harder to judge, start where the gap is still open and scan 29 high quality undervalued stocks.
The Two Macerich Stories Investors Had To Weigh
The shares cost US$16.92 at the start, so any Macerich view had to begin with what that price already implied.
The bullish Narrative put Fair Value at US$19.53, about 15% above the start price, and leaned on experiential retail and urban malls. It assumed revenue would fall 1.1% a year while profit margin moved up to 2.2% and the future P/E reached 352.8x.
The bearish case set Fair Value at US$15 and focused on e-commerce pressure and high leverage. It rested on the risk that declining mall demand would hit leasing revenue and leave refinancing as a persistent concern.
What The Evidence Around Macerich Actually Tested
Macerich’s Q2 2026 numbers showed revenue of US$252.4m and a net loss of US$27.3m, with net margin improving from -16.5% to -10.8%. That trend, together with Q1 2026 leasing momentum and the Annapolis Mall acquisition, supported the bull view on experiential assets and demand, but profitability still falling short kept the cautious case alive. The evidence cut both ways.
The lesson is simple. When a thesis hinges on margin repair, track net margin and absolute profit against the original forecast, not just headline leasing wins or new projects.
What Macerich’s Run Leaves You Paying For Now
With Macerich now at US$24.34, the latest Narrative’s Fair Value sits below the current price, which frames the recent gain as compressing the implied margin of safety.
That Narrative leans on leasing momentum and the Path Forward plan but worries about refinancing pressure and e-commerce. A buyer today effectively banks on durable rent growth, so how does that square with the risk that long term mall demand keeps eroding occupancy and achievable rents?
"Persistent shifts to e-commerce and changing consumer preferences threaten long-term leasing revenue and profitability, despite recent leasing gains and backfilling efforts. High leverage and exposure to underperforming malls increase refinancing risk, limit redevelopment capacity, and pressure future earnings and cash flow."
One Narrative disagrees with today's price. → See where this Narrative says Macerich should trade
Looking Past Macerich’s Malls
Once you understand what drives Macerich, it becomes easier to recognize echoes elsewhere. Mall strategies help frame how other retail landlords position their properties.
Big malls emphasize experiential tenants and dense urban locations. They depend on entertainment, dining and destination shopping to keep traffic flowing through large enclosed spaces.
Another landlord follows a simpler path, focusing on single tenant retail sites. Tenants typically handle property level costs through long leases with defined terms.
Those properties tilt toward everyday spending, often with occupants that have stronger credit profiles than many mall tenants. If you are weighing mall exposure today, that different way of owning retail space might deserve closer attention next.
One Narrative has already put a figure on it. → Uncover the company trading 17% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com