


Fed officials are talking tougher on inflation again, and that can shake up anything tied to future cash flows, including steady dividend payers. Rate hike expectations move discount rates higher, which can pressure valuations but also reveal which payouts look more resilient. This piece unpacks three US large cap dividend stocks that screens suggest could be relatively well positioned, helping you decide whether they deserve a closer look or a spot on your avoid list.
The three tickers in this piece are just a small sample of the idea, and the full screen surfaced 33 more large cap dividend payers with equally compelling stories that are not covered here. To move straight into the full list and identify your own highest conviction defensive income plays, head to the US Large-Cap Defensive Dividend Stocks screener.
Sun Communities (SUI)
Overview: Sun Communities is a US based real estate investment trust that owns and operates manufactured housing and RV communities that generate rental income and fund a consistent dividend profile.
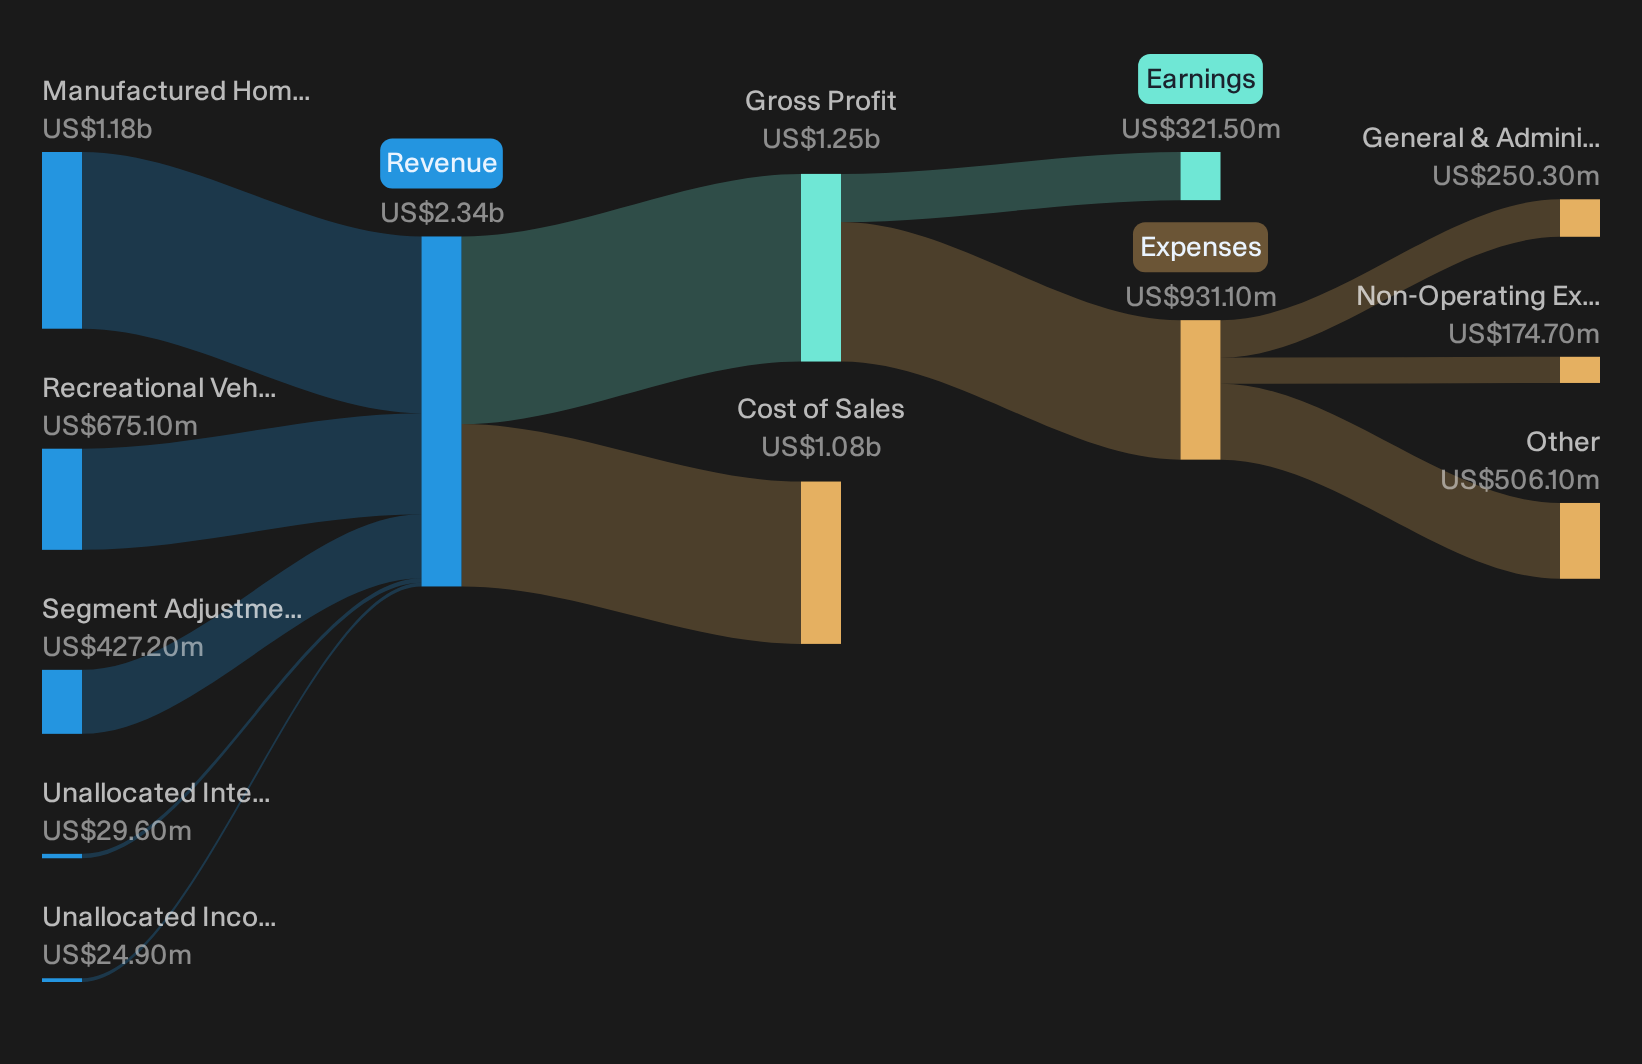
Operations: Sun Communities earns about $1.18b from manufactured home communities and $675 million from RV resorts, with additional segment adjustments and smaller unallocated income streams.
Market Cap: $13.7b
Sun Communities fits the defensive dividend theme through rental income from essential housing and long stay RV sites. This gives investors exposure to recurring cash flows that can feel very different from more cyclical sectors when the Fed talks tougher on rates.
"Ongoing structural U.S. housing affordability pressures and limited new manufactured housing supply, combined with occupancy above 98% in Sun Communities’ manufactured housing portfolio, support the potential for sustained rent growth and stable site revenue that can feed into long term NOI and earnings."
The main swing factor is how cost pressures and leverage affect margins if higher interest rates remain in place for longer than expected.
If that rate risk is what you are weighing, the full narrative for Sun Communities describes how Sun Communities’ balance sheet, lease terms and capital plans could be decoupling from the noise.
Lamb Weston Holdings (LW)
Overview: Lamb Weston Holdings is a frozen potato specialist supplying fries and related products to restaurants, retailers, and foodservice customers across multiple regions.
Operations: Lamb Weston generates about $4.45b in North America revenue and $2.17b internationally from frozen potato and related product sales.
Market Cap: $7.34b
Lamb Weston fits the screener as a consumer staples style dividend payer. Fry demand can feel steadier than many discretionary categories when the Fed leans more hawkish.
"The call now places the cause on supply. Mike Smith calls the European crop “a tale of two years,” argues that raw potato quality and yield “is likely going to be the limiter,” and says “not all open industry capacity will be used.”
For dividend focused investors, the key question is what happens to earnings power if a single unseen pressure quietly shifts how that supply story translates into margins.
That quiet pressure is exactly where the story gets interesting, and the full narrative for Lamb Weston Holdings shows how Lamb Weston could turn supply friction into an earnings reset opportunity.

VICI Properties (VICI)
Overview: VICI Properties is a large US REIT that owns major casino and leisure real estate and collects rent through long-term leases.
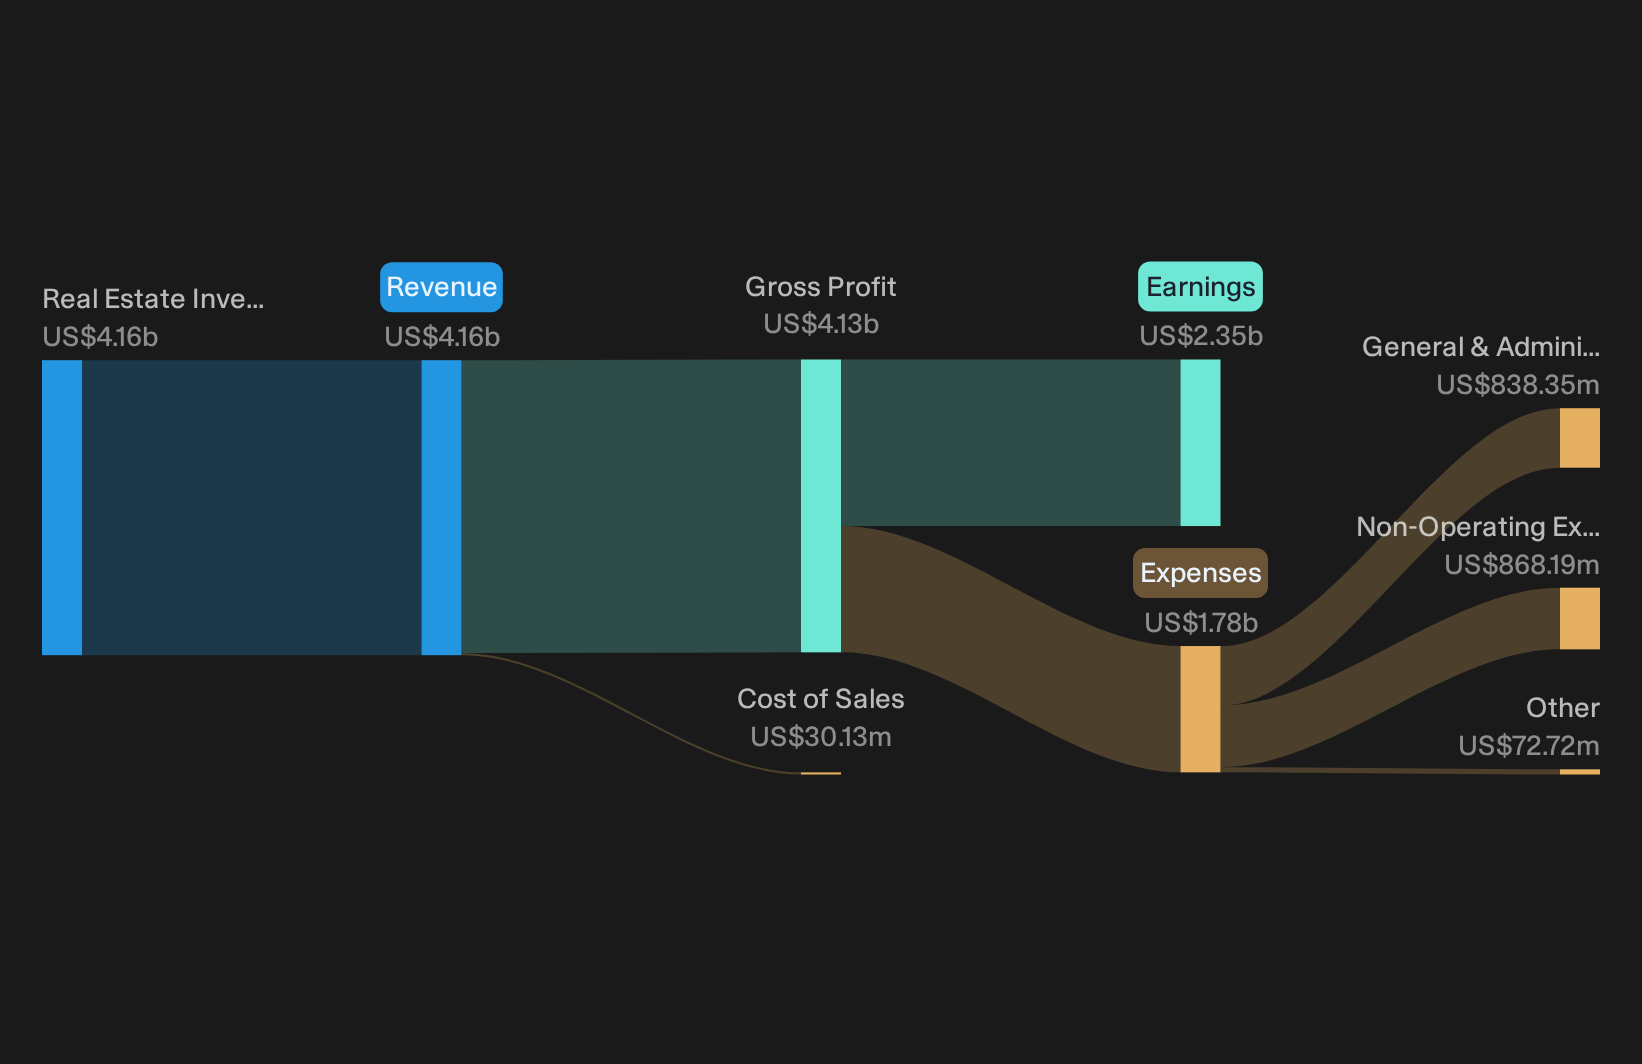
Operations: VICI Properties generates about US$4.16b in real estate investment activity revenue, all sourced from properties across the United States.
Market Cap: US$27.0b
VICI Properties lines up with this defensive dividend screen because it pairs a sizeable payout with long leases to big casino operators. The key question for readers is how stable that rent stream looks as rates climb and tourism faces policy uncertainty.
"Given the present uncertainty and unrest on the United States and its immigration and tourism policies will penalize the growth of VICI during the next couple of years, being more pronounced on the next year, and tapering a little above the economy growth rate after that."
What really matters is how one unresolved tenant and funding pressure ultimately feeds through to the path of future dividend headroom.
That uncertainty is only half the story. Read the full narrative for VICI Properties to see how VICI Properties could turn policy noise into accelerating rent resilience and dividend flexibility.
Seeking Alternatives Before The Crowd?
Fresh ideas move first. Breakout themes, early momentum, and quality stocks can get caught flying once attention spikes. Scan these curated lists while it matters and get in early.
- Review the list of solid balance sheet and fundamentals (25 results) to find income-focused companies with balance sheet strength to handle rate changes.
- Use the 54 AI infrastructure stocks to explore companies participating in AI infrastructure activity.
- Search the 18 high quality undiscovered gems for earlier-stage companies that may not yet have broad market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com