


Exelon (EXC) just reported third quarter earnings that topped analyst expectations, raised its full year adjusted operating earnings guidance, and reaffirmed a robust multi year earnings outlook despite lower year over year net income.
Recent moves suggest investors are warming to Exelon again, with a 14.3% 1 month share price return and a 5.1% year to date share price gain helping offset earlier softness, while 3 year and 5 year total shareholder returns of 27.5% and 42.8% indicate steadier long run compounding.
Scan for more regulated utilities showing similar earnings resilience and renewed interest to Exelon with our hand picked 39 power grid technology and infrastructure stocks.
That kind of rebound in Exelon can either read as a clear vote of confidence in the regulated utility earnings story or as sentiment snapping back after a weak spell. The valuation now needs a closer look.
Most Popular Narrative: 3% Undervalued
Exelon closed at $46.16 against a narrative fair value of $47.59, which frames the recent rebound as a modest discount rather than a stretched move, and puts the focus firmly on how much of the multi year plan is already embedded in the price.
The rebalanced US$41.7b capital plan that shifts US$1.5b into higher earning transmission while deferring US$1.1b of lower priority distribution projects positions Exelon to pursue its targeted 7.9% rate base growth with a tilt toward assets that can support operating EPS and cash flow. Company wide efforts to cap adjusted O&M growth at no more than 2% annually through 2029, including identified US$350m of savings in 2027 and early completion of about 86% of 2026 debt needs plus pre pricing of roughly 37% of planned equity through 2029, are aimed at supporting net margins and sustaining credit metrics as the capex plan is executed.
See why 37 investors see Exelon as 3% undervalued.
Result: Fair Value of $47.59 (UNDERVALUED)
Still, that story can fray quickly if regulators squeeze allowed returns or if customer affordability concerns slow approval of Exelon’s US$41.7b capital program.
Find out about the key risks to this Exelon narrative.
Another View: Exelon Through The Cash Flow Lens
There is a catch. While the narrative fair value points to Exelon as 3% undervalued, the Simply Wall St DCF work paints a very different picture, with the share price of $46.16 sitting well above an estimated future cash flow value of $7.63. That gap raises a simple question for investors: Which story feels more credible to you?
Look into how the SWS DCF model arrives at its fair value.
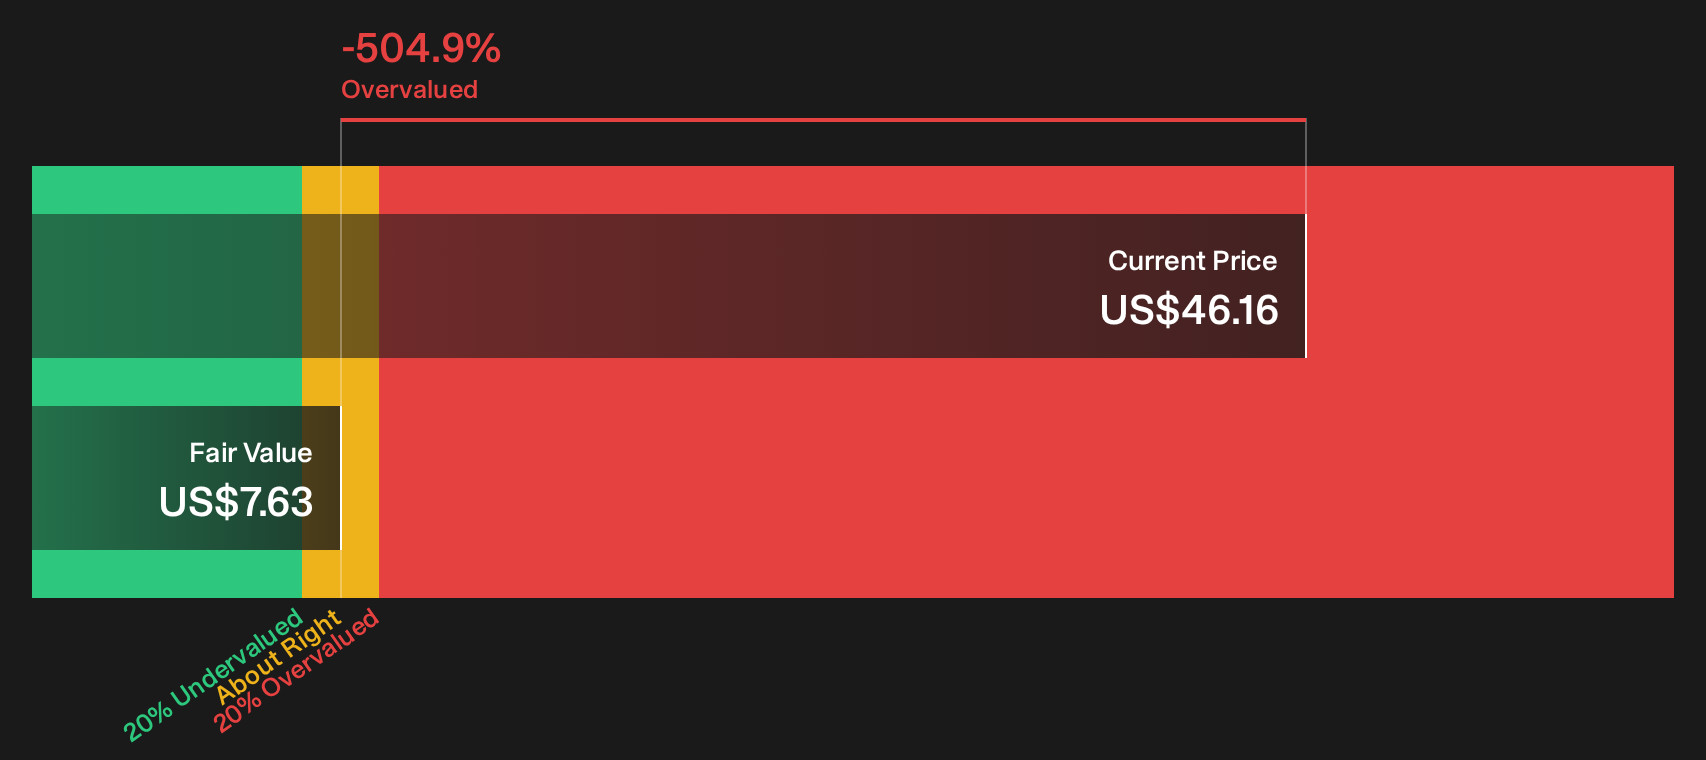
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Exelon for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the data or a clear signal taking shape. Act while the information is fresh and weigh both sides for yourself with the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Exelon?
If Exelon has sharpened your focus on regulated utilities and valuation gaps, broaden your watchlist now and see how other opportunities stack up while conditions still look compelling.
- Target resilient growth potential by hunting for quality companies that still trade at appealing prices through the 29 high quality undervalued stocks.
- Strengthen your income stream by zeroing in on companies built around reliable cash returns with the 5 dividend fortresses.
- Prioritise resilience and capital protection by scanning companies that show robust financial footing using the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com