


Ormat Technologies (ORA) heads into its upcoming September 2026 quarter earnings report with expectations shaped by a positive Earnings ESP and a Zacks Rank #3 (Hold), after beating EPS estimates in three of the last four quarters.
At a share price of US$89.69, Ormat Technologies has seen short term momentum soften, with the 90 day share price return down 8.09% and the year to date move down 21.14%, even though the 3 year total shareholder return of 39.17% still points to meaningful longer term gains for investors who stayed the course.
Compare Ormat Technologies with a curated 29 high quality undervalued stocks that pairs earnings potential with stronger recent price support.
Ormat Technologies now sits at an awkward middle ground, punished in the short term but still carrying a solid multi year record. Do the current fundamentals and price tag still stack up well enough for new buyers?
Most Popular Narrative: 29% Undervalued
On the most followed narrative, Ormat Technologies screens as undervalued, with a fair value estimate of $126.33 against a last close of $89.69. The gap between price and projected fundamentals is doing the heavy lifting in the bullish case.
Ormat Technologies’ shift from a pure play geothermal operator to a broader renewable and storage platform is reflected in energy storage and product segments that now contribute around 25% of revenue and adjusted EBITDA. Management plans to expand storage capacity to up to 1.6 GW and more than 5 GWh by 2030, which could broaden revenue streams and support overall EBITDA growth.
See why 11 investors see Ormat Technologies as 29% undervalued.
Result: Fair Value of $126.33 (UNDERVALUED)
Still, the bullish script for Ormat Technologies can unravel quickly if electricity margins fail to move toward management targets or if tight funding conditions collide with its roughly US$2.7b net debt load.
Find out about the key risks to this Ormat Technologies narrative.
Another View: Multiples Paint A Tougher Picture For Ormat Technologies
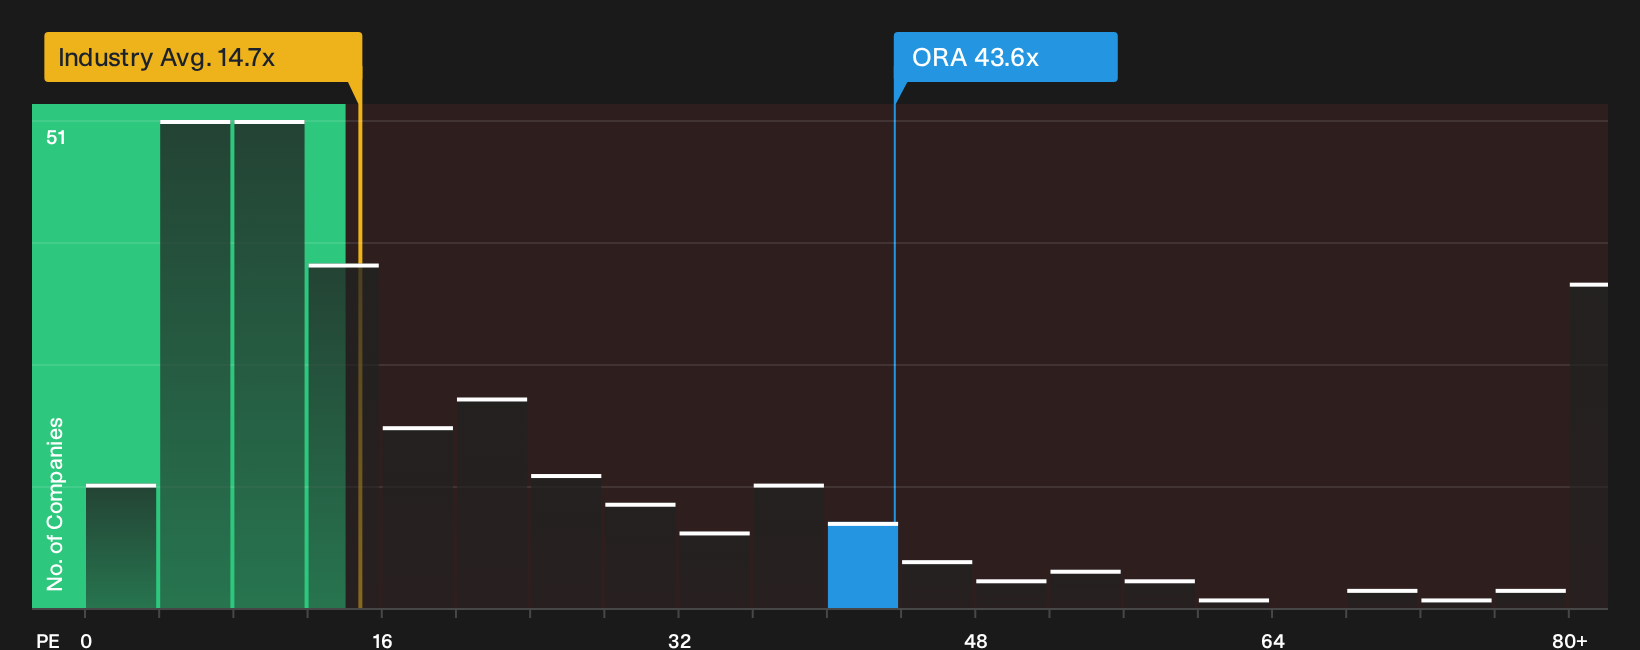
While the dominant narrative argues Ormat Technologies looks 29% undervalued on future earnings, the current P/E of 43.6x tells a tougher story. That is far above peers at 28.5x, the global renewable energy average at 14.8x, and the fair ratio of 24.1x. This combination flags real valuation risk if sentiment cools.
Our preferred multiple work suggests investors are already paying up heavily for Ormat Technologies. The real question is whether the growth and execution story is strong enough to keep that premium intact or even expand it from here.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Ormat Technologies so far. There is short term pressure and a rich P/E on one side, and a long term narrative with fair value upside on the other. Move quickly, review the underlying data, and weigh both the upside potential and downside hazards by checking the 2 key rewards and 2 important warning signs.
Ready For More Ideas Beyond Ormat Technologies?
If Ormat Technologies has you thinking about valuation gaps and risk, do not stop there. Use a focused screener to surface other opportunities that fit your style.
- Target steadier compounding potential by reviewing companies with strong balance sheets and resilient fundamentals through this curated list of solid balance sheet and fundamentals (25 results).
- Hunt for quality at a discount by scanning a refined 18 high quality undiscovered gems that highlights under-the-radar businesses with solid underlying metrics.
- Prioritise capital protection first and then returns by working through a hand picked 30 resilient stocks with low risk scores that emphasises resilience over speculation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com