


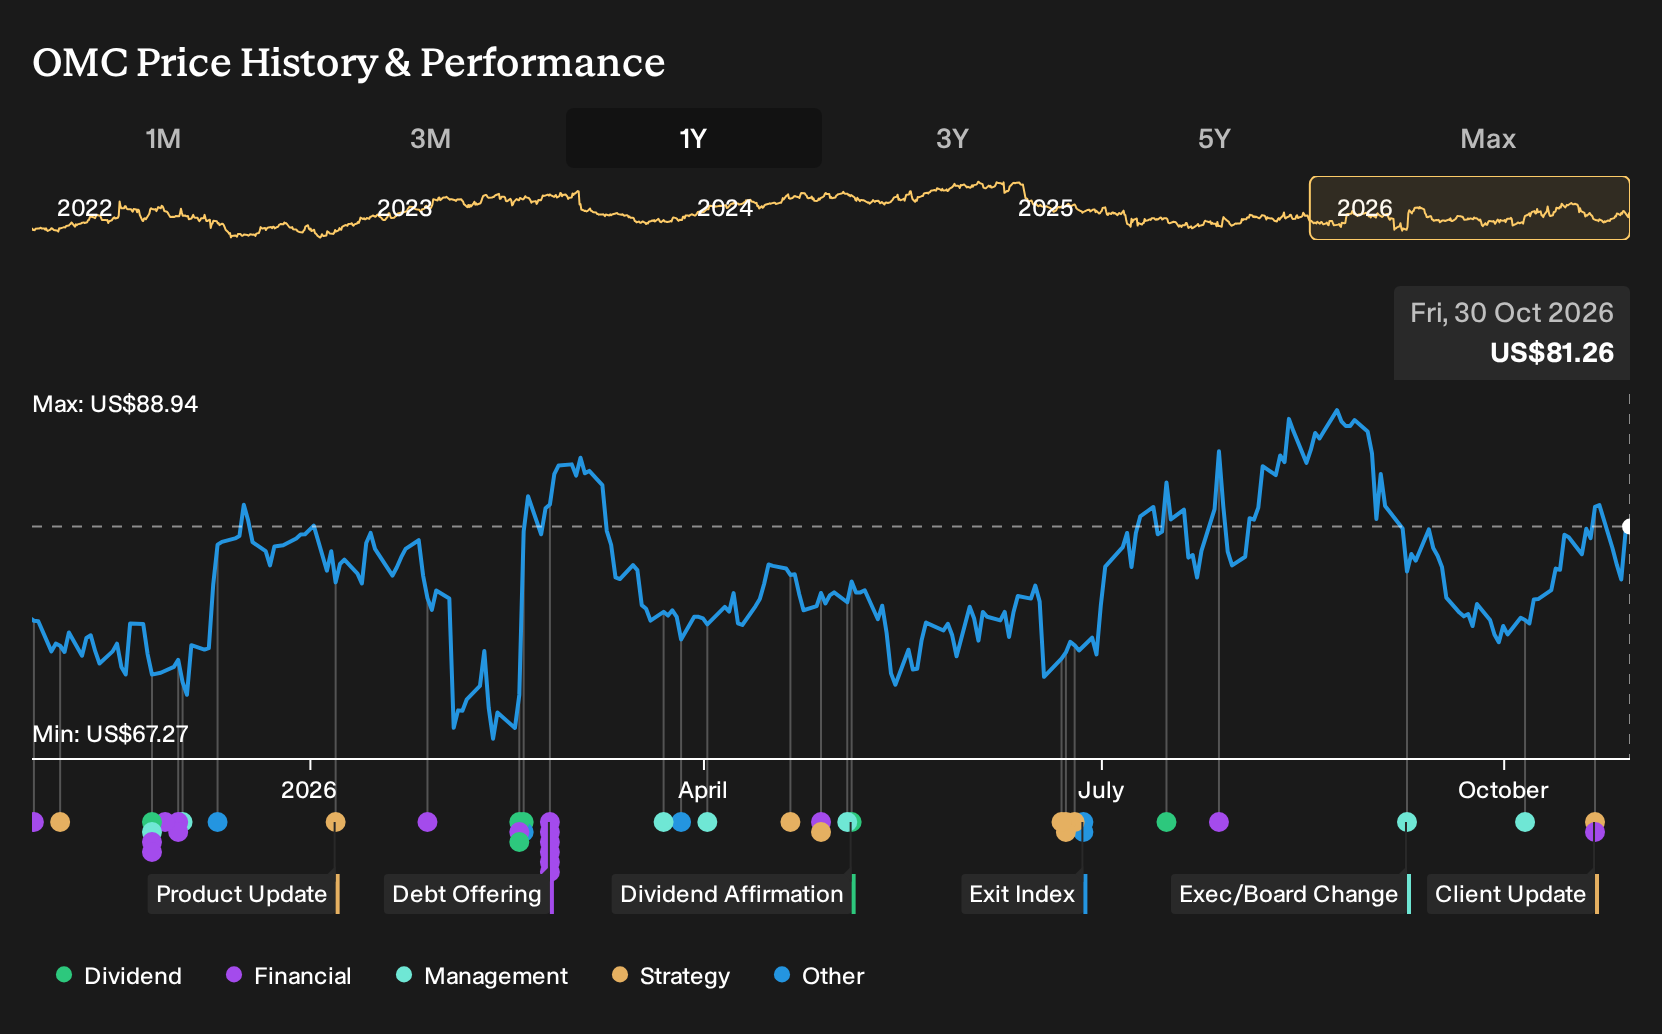
- Omnicom Group reported third quarter 2026 sales of US$6,422.8 million and net income of US$656 million, and Coca-Cola selected Omnicom as its media partner in North America while WPP Open X retained global media duties elsewhere.
- The Coca-Cola North America media mandate, combined with Omnicom’s higher year over year earnings per share and ongoing share repurchases, highlights how large client relationships, profit generation and capital returns are converging in the group’s current business profile.
- This article now examines how Omnicom Group’s earnings strength and the new Coca-Cola mandate could influence the existing investment narrative.
Omnicom Group Investment Narrative Recap
To own Omnicom Group, you need to believe the integration of Interpublic assets and the Omni tech stack can turn scale into steadier earnings, even as traditional advertising remains under pressure. The Coca-Cola North America win and the strong third quarter numbers support that narrative. The near term swing factor is execution on integration and cost saves.
The biggest risk still sits in uneven regional trends, advertising softness and higher interest expense, which can dilute the benefit of new mandates. The Coca-Cola appointment and recent earnings do not remove those issues. They simply give Omnicom more room to work on mix, pricing and margin.
The most relevant fresh data point is the third quarter 2026 earnings release. Omnicom Group reported US$6,422.8 million of sales and US$656 million of net income for the quarter, with higher basic and diluted earnings per share from continuing operations than a year earlier. For the first nine months, sales were US$19,228.2 million and net income was US$1,646 million.
For you as a shareholder, the key question is whether that earnings profile is sustainable as portfolio pruning, AI deployment and Interpublic integration continue. Higher interest costs, lower recent profit margins and regional volatility remain on the table. The recent performance simply shows the group can still produce solid income while working through those hurdles.
Omnicom Group’s current analyst narrative points to revenues of US$26.0b and earnings of US$2.6b by 2029, based on assumed yearly top line expansion of 5.2% and an earnings increase of about US$2.2b from US$390.2m today.
Discover why Omnicom Group's fair value points to a 26% potential upside to its current price, which could diminish quickly.
Exploring Other Perspectives
One alternate view puts the Coca-Cola North America win in the shadow of execution risk. The most bullish Omnicom Group analysts were already pencilling in about US$26.9b of revenue and US$3.7b of earnings by 2029. You can read that as an optimistic script that may be rewritten once this mandate fully lands.
Explore 3 other Omnicom Group fair value estimates, including one that suggests as much as 59% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Omnicom Group research is our analysis highlighting 3 key rewards and 5 important warning signs that could impact your investment decision.
- See our latest analysis for Omnicom Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Omnicom Group's overall financial health at a glance.
Looking for more investment ideas beyond Omnicom Group?
Once you have formed a view on Omnicom Group, it can help to compare that thesis with other companies filtered by quality, balance sheet strength and risk profile. The Simply Wall St Screener can narrow the field quickly so you spend time only on opportunities that fit your own criteria.
- If you care most about financial resilience, start with a list of solid balance sheet and fundamentals (25 results) that can handle shocks without constant refinancing risk.
- For investors searching for quality at a reasonable price, focus on companies in the 29 high quality undervalued stocks that pair solid fundamentals with more modest expectations embedded in their current valuations.
- If lower volatility and capital preservation matter to you, filter for 30 resilient stocks with low risk scores that score well on both stability and downside risk indicators.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com