


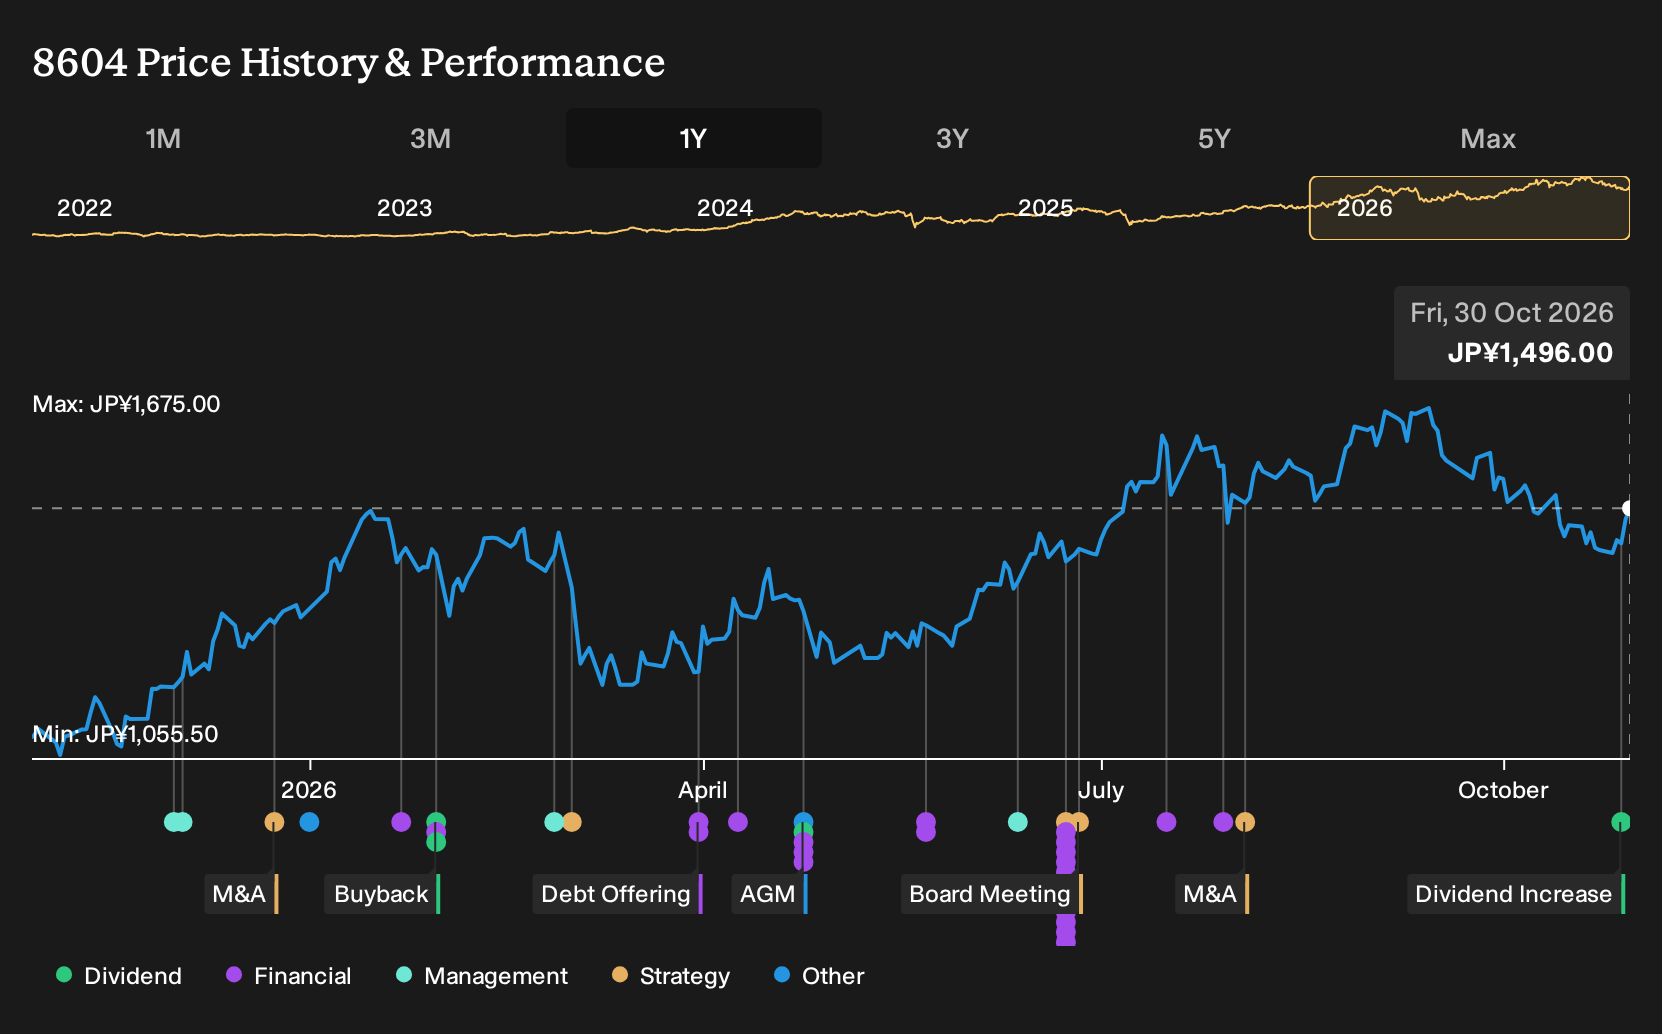
- Nomura Holdings reported half year revenue of ¥2,694,536 million and net income of ¥249,289 million, with basic EPS from continuing operations at ¥85.39 and a dividend of ¥35 per share declared for payment on December 1, 2026.
- The cash return to shareholders is funded from retained earnings, while management focuses on recurring fee income growth and cost efficiency. This highlights a tension between rewarding investors today and funding the ongoing business transformation.
- The next step is to consider how Nomura Holdings' higher half year earnings and new dividend fit into the existing investment narrative.
Nomura Holdings Investment Narrative Recap
To own Nomura Holdings, you need to be comfortable with a story that leans more on fee and interest income from Wealth Management, Investment Management and Banking, while Wholesale remains a swing factor. The latest half year results, with higher revenue and net income versus a year ago, indicate that the mix is gradually tilting toward recurring sources.
The near term catalyst still lies in execution on cost efficiency and stable fee flows after a quarter where margins and return on equity came under pressure. The main operational risk is that weaker Wholesale profitability and reliance on wholesale funding coincide with tougher markets, which could squeeze margins even if top line trends hold.
The dividend declaration of ¥35 per share for payment on December 1, 2026 is the clearest new signal to assess. It draws on retained earnings at a time when the firm is talking about business transformation, so investors are being asked to judge how comfortable they are with that cash return alongside reinvestment needs.
For catalysts, that payout interacts directly with the push into recurring revenue and cost programs such as SRC 2.0. If earnings pressure in Wholesale or higher funding costs persist, the combination of a dividend that is not well covered by free cash flow and execution risk on efficiency programs becomes central to how Nomura Holdings is viewed today.
Nomura Holdings' narrative projects revenue of ¥2,572.5b and earnings of ¥496.4b by 2029. This is based on an assumption of 3.3% yearly revenue growth and an earnings increase of about ¥93.3b from current earnings of ¥403.1b.
Uncover how Nomura Holdings' fair value indicates a 19% potential upside to its current price before the gap to market expectations closes.
Exploring Other Perspectives
For a different angle, focus on the bullish catalyst around Nomura Holdings’ fee and interest income. The most optimistic analysts were already pencilling in revenue of ¥2,806.6b and earnings of ¥550.3b by 2029, well above the ¥2,572.5b and ¥496.4b in the baseline view. These pre news forecasts may shift, so it makes sense to compare several narratives before deciding how this new dividend and earnings update fits your own thesis.
Explore another Nomura Holdings fair value estimate, including one that suggests there may be as much as 68% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Nomura Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Nomura Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nomura Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Nomura Holdings?
Once you have a view on Nomura Holdings, it can help to stack it up against other opportunities using the Simply Wall St Screener. That way you can stress test your thesis across different balance sheets, payout profiles and risk levels rather than relying on a single stock.
- If you want companies where income is a key part of the story, scan for payouts that aim for resilience with our 27 dividend fortresses.
- To focus on businesses that combine financial strength with cleaner balance sheets, filter for cash rich operators using the list of solid balance sheet and fundamentals (22 results).
- If you are hunting for candidates the market may not be paying close attention to yet, widen your search using the 71 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com