


Applied Materials (AMAT) has been getting fresh attention after committing heavier capital spending, from a new manufacturing center in Singapore to higher reinvestment that affects the cash left for buybacks and dividends.
Recent trading has been choppy. The share price fell 7.5% over the last session and is down about 24% over the past month. Applied Materials still shows a 45.1% year to date share price return and a 1 year total shareholder return of 68.3%, which signals strong momentum over a longer stretch. At the same time, fresh capex plans and the larger BE Semiconductor stake are prompting investors to reassess near term risk and reward around the current US$390.09 level.
Scan beyond Applied Materials and size up other chip equipment players singled out in our 54 AI infrastructure stocks as AI-related capex ramps and investor attention swings toward the broader supply chain.
The pullback leaves Applied Materials well off recent highs, yet still up sharply over the past year. Does it make more sense to step in around US$390 now, or wait for a deeper reset before committing fresh capital?
Most Popular Narrative: 39% Undervalued
Applied Materials is trading at $390.09 against a most-followed fair value estimate of about $638.94, so the gap is wide and depends on how its AI focused equipment, services, and capacity investments convert into future earnings.
The mix shift toward leading edge foundry logic, DRAM including high bandwidth memory, and advanced packaging is expected to account for most wafer fab equipment growth in 2026 and 2027, and Applied Materials is forecasting more than 70% growth in advanced packaging revenue and more than 50% growth in process diagnostics and control in 2026. This points to a richer product mix that can support margins and net income.
See why 329 investors see Applied Materials as 39% undervalued.
Result: Fair Value of $638.94 (UNDERVALUED)
Still, the bullish Applied Materials narrative could unravel if heavy capex keeps squeezing free cash flow, or if margin guidance stays flat despite higher revenue.
Find out about the key risks to this Applied Materials narrative.
Another View: Applied Materials Through A Cash Flow Lens
The most followed narrative frames Applied Materials as undervalued against a fair value of $638.94, yet the SWS DCF model paints a different picture. On that cash flow view, AMAT at $390.09 sits above an estimated value of $280.02. This implies an overvalued reading and raises the question of which story you trust more: cash today or projected growth.
For readers who want to see how that cash flow view is built line by line, and test whether the inputs feel realistic for AMAT, Look into how the SWS DCF model arrives at its fair value..
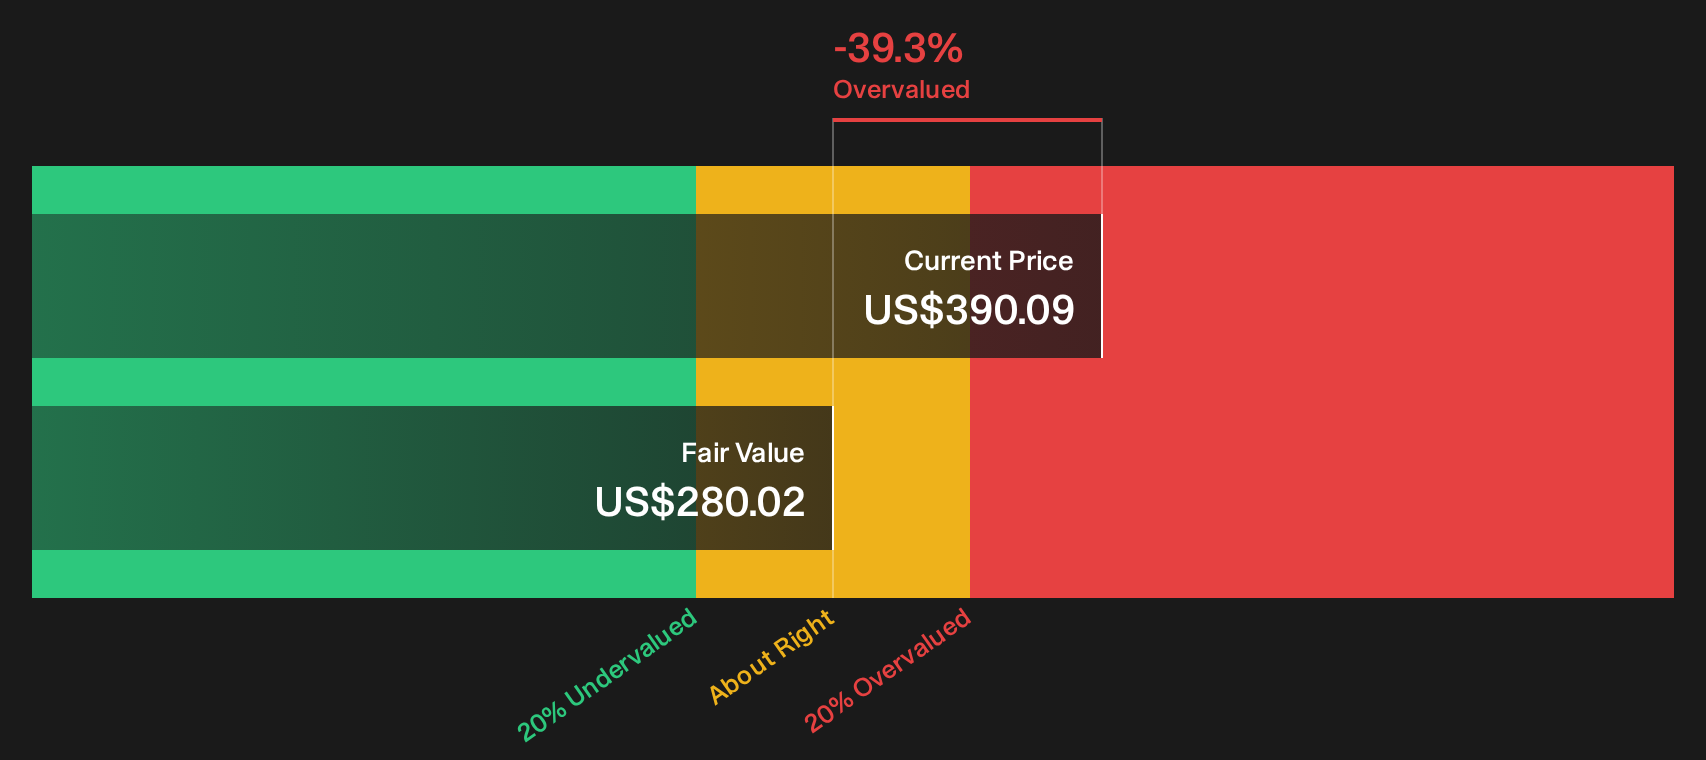
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Applied Materials for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Applied Materials so far. If you want to move fast and decide where you land on the story, weigh the 3 key rewards and 1 important warning sign.
Ready for more ideas beyond Applied Materials?
Do not stop at Applied Materials. Apply the same scrutiny across fresh opportunities so you keep widening your opportunity set instead of waiting on one ticker.
- Target reliable compounding potential with a 5 dividend fortresses that can support a steadier income stream alongside capital appreciation.
- Hunt for mispriced potential by scanning a 29 high quality undervalued stocks that couples solid balance sheets with attractive valuations.
- Spot tomorrow's potential early by reviewing a 18 high quality undiscovered gems that the wider market has not fully focused on yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com