


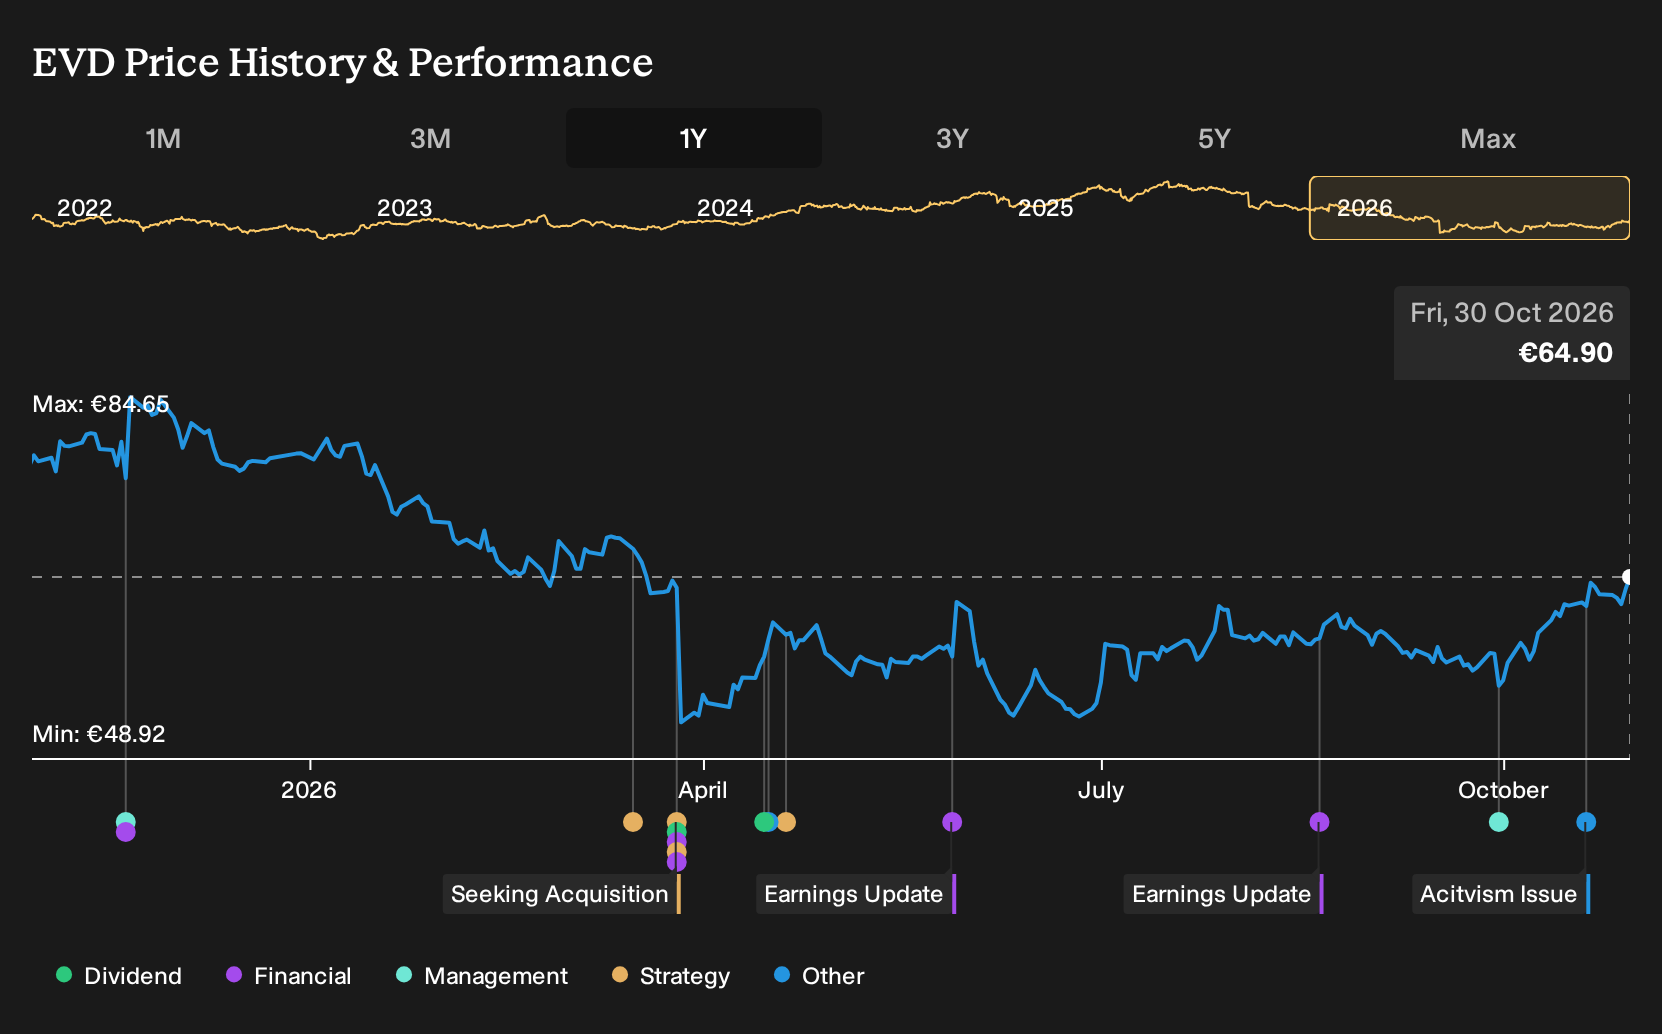
- On 20 October 2026, Ananym Capital disclosed a new stake in CTS Eventim KGaA and publicly argued that the business was significantly undervalued, urging clearer disclosure of its operating model, a more stable leadership setup and a share buyback program.
- The push for greater transparency around how CTS Eventim KGaA earns returns from ticketing, venues and mega event contracts goes straight to the core of how investors assess the quality and durability of its cash generation.
- This article will now explore how CTS Eventim KGaA's investment narrative could shift as Ananym presses for clearer disclosure and capital returns.
Scan how other investors are pricing similar stories by comparing CTS Eventim KGaA with a curated 199 high quality undervalued stocks, which may also be attracting activist attention around capital returns and disclosure.
CTS Eventim KGaA Investment Narrative Recap
To own CTS Eventim KGaA, you need to believe that international ticketing integration, venue expansion and long dated event contracts can translate into healthier margins once the current investment and program costs pass. The near term hinge is execution on Operational Excellence and Amplify, since they are raising expenses now while the expected efficiency benefits are still ahead.
The main operational risk remains cost pressure in Live Entertainment, especially around festivals and artist terms, with that segment already generating more than €1.0b of revenue at a 5% adjusted EBITDA margin in the first half of 2026. Ananym Capital's activism looks more focused on disclosure and capital allocation, so the immediate impact on these operating risks and catalysts appears limited.
Ananym Capital's October 2026 letter about CTS Eventim KGaA connects most directly to its request for a share buyback and clearer disclosure around how ticketing, venues and mega events drive returns. That push lands on a company where analysts already flag that a re rating would require confidence in sustaining at least mid single digit organic growth and better clarity on earnings durability.
A buyback, if adopted, would sit alongside existing uses of cash such as venue projects and the asset light PropCo model. Investors would therefore need to judge whether CTS Eventim KGaA can fund both growth and shareholder returns without stretching its balance sheet. The activism also highlights an unstable dividend track record and mixed valuation signals, with the stock described as trading at 43% below an internal fair value estimate while also screening as expensive on some P/E comparisons. That keeps execution and transparency firmly in focus as the practical catalysts to watch.
What The Analyst Case Implies For CTS Eventim KGaA
CTS Eventim KGaA's analyst script is built around moderate expansion rather than a breakneck sprint. The current consensus folds in revenue growth of 4.4% a year over the next three years, a step up in profit margins from 9.3% today to 11.4%, and a move in earnings from €308.0 million now to €428.3 million by 2029. That path points to an earnings increase of about €120 million, while the revenue line is framed at €3.8 billion in 2029, with the whole story discounted back using a cost of capital of roughly 7.2%.
CTS Eventim KGaA's narrative projects €3.8 billion revenue and €428.3 million earnings by 2029. This requires 4.4% yearly revenue growth and an earnings increase of about €120 million from €308.0 million.
For anyone weighing Ananym Capital's arguments, those numbers matter because they shape what "undervalued" actually means in practice. Analysts are effectively saying that by 2029 investors would need to accept a P/E of 23.0x on those forecast earnings, compared with 20.0x today and 12.6x for the broader GB Entertainment peer group. That is a punchy multiple for a business priced on mid single digit annual revenue expansion and mid teens earnings growth in euro terms.
This is where disclosure becomes more than a governance talking point. If CTS Eventim KGaA can break out how ticketing, venues and mega events contribute to that forecast €428.3 million earnings pool, investors can test whether a 23.0x P/E looks grounded in underlying cash generation or mainly in optimism about future projects. A clearer bridge from today's €308.0 million to the 2029 consensus figure would also help you decide whether current margin targets and cost saving plans feel realistic or stretched.
Uncover why CTS Eventim KGaA's fair value indicates a 28% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate CTS Eventim KGaA story leans on data and AI as the real swing factor. The most optimistic analysts, working off pre activism forecasts, were pencilling in revenue of about €3.9b and earnings of €449.2 million by 2029. Ananym’s push could easily prompt those upbeat models to be revisited, in either direction.
Explore 5 other CTS Eventim KGaA fair value estimates, including one that suggests as much as 76% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your CTS Eventim KGaA research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for CTS Eventim KGaA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CTS Eventim KGaA's overall financial health at a glance.
Looking For More Investment Ideas Beyond CTS Eventim KGaA?
Once you have formed a view on CTS Eventim KGaA, it can help to cross check that judgment against a wider watchlist of opportunities that share similar qualities or risks. The Simply Wall St Screener lets you do that quickly by filtering stocks around the themes that matter most to you, whether that is value, income or balance sheet strength.
- If you want to hunt for quality that the market may be overlooking, start with a curated set of potential value opportunities using the 603 high quality undiscovered gems.
- If capital preservation and resilience appeal more than excitement, narrow your focus to companies that screen well on stability and risk using the 218 resilient stocks with low risk scores.
- If you care about balance sheet strength backing up the equity story, scan a targeted list of solid balance sheet and fundamentals (203 results) to see which businesses combine financial resilience with fundamentals you can examine in more detail.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com