


Acadian Asset Management (AAMI) drew fresh attention after its board approved a quarterly interim dividend of $0.10 per share, payable on December 23, 2026, to shareholders of record on December 11.
Acadian Asset Management shares have cooled off in recent weeks, with the share price down 3.7% over the past week and 3.0% over the past month. Yet the year to date share price return of 87.7% and a three year total shareholder return above 4x suggest longer term momentum has been strong, even as the latest pullback hints at investors reassessing how much near term growth and risk are already reflected in the US$88.92 price.
Spot similar momentum shifts beyond Acadian Asset Management by scanning our hand picked 18 high quality undiscovered gems with fundamentals that aim to back up strong share price moves.The pullback leaves Acadian Asset Management trading just below analyst targets while above some intrinsic value estimates. This raises the question of where a fair price might reasonably fall within that range, and what investors are effectively paying for at current levels.
Price-to-Earnings of 31.1x: Is it justified?
The current $88.92 Acadian Asset Management share price implies a P/E of 31.1x, which looks expensive against close peers but cheaper than the broader US Capital Markets group.
The P/E ratio compares what investors are willing to pay today for each dollar of current earnings. For Acadian Asset Management, this 31.1x multiple sits below the US Capital Markets industry average of 38.2x, yet above the 19.4x level seen across its more direct peer group.
That split sends a mixed signal. The broader sector comparison suggests the market is not stretching the valuation as far as it could based on industry norms. In contrast, the premium to peers hints that investors are accepting a richer tag for this ticker's earnings profile than for similar companies.
Set against the wider industry, the stock trades at a firm discount to the 38.2x sector average P/E, which points to a more restrained valuation. Measured against the tighter 19.4x peer benchmark, the same 31.1x reading looks much more demanding and indicates investors are paying up relative to nearer comparables.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 31.1x (ABOUT RIGHT)
Still, Acadian Asset Management depends on fee based revenue tied to client assets, so market volatility or weaker flows could pressure earnings and challenge that richer P/E.
Find out about the key risks to this Acadian Asset Management narrative.
Another View: Acadian Asset Management Through A Cash Flow Lens
The multiple looks roughly in line with the wider group, yet the SWS DCF model paints a very different picture. On that framework, Acadian Asset Management at $88.92 trades well above an estimated future cash flow value of $9.65, which points to a rich pricing gap that readers need to weigh carefully.
Look into how the SWS DCF model arrives at its fair value.
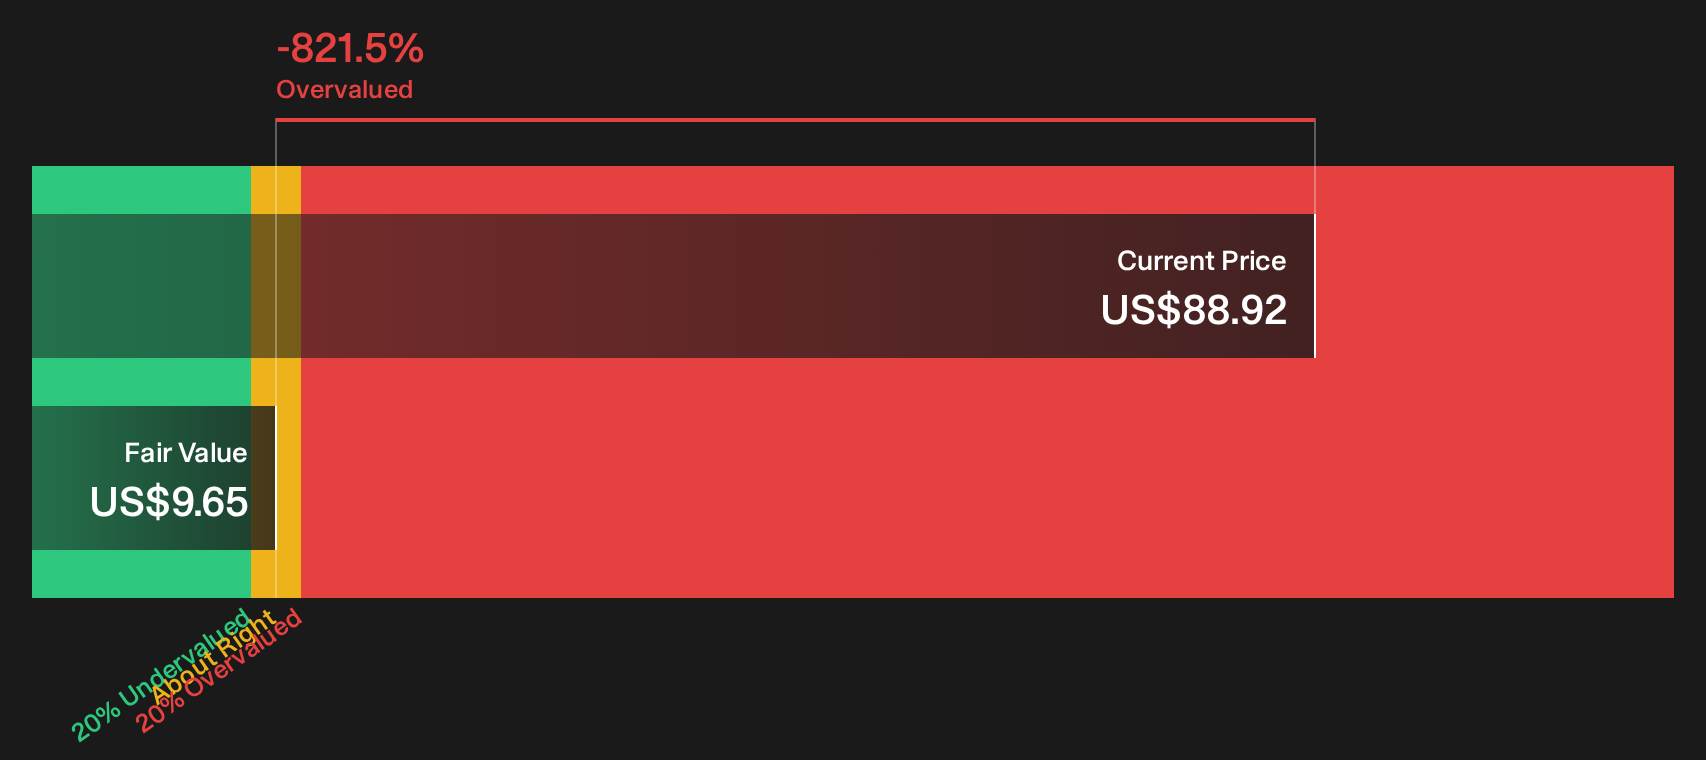
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Acadian Asset Management for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With Acadian Asset Management drawing both optimism and concern, consider those cross currents quickly and make up your own mind with the 2 key rewards and 4 important warning signs
Looking for more investment ideas beyond Acadian Asset Management?
If Acadian Asset Management has sharpened your focus on pricing and risk, do not stop here. Use the screener to spot fresh setups across sectors before the crowd.
- Target reliable cash generators by scanning a list of solid balance sheet and fundamentals (25 results) that can better withstand shocks and still support long term compounding.
- Hunt for value by checking a 29 high quality undervalued stocks where quality fundamentals line up with prices that have not fully reflected them yet.
- Reduce stress on your portfolio by comparing a 30 resilient stocks with low risk scores that scores well on balance sheet strength and business stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com