


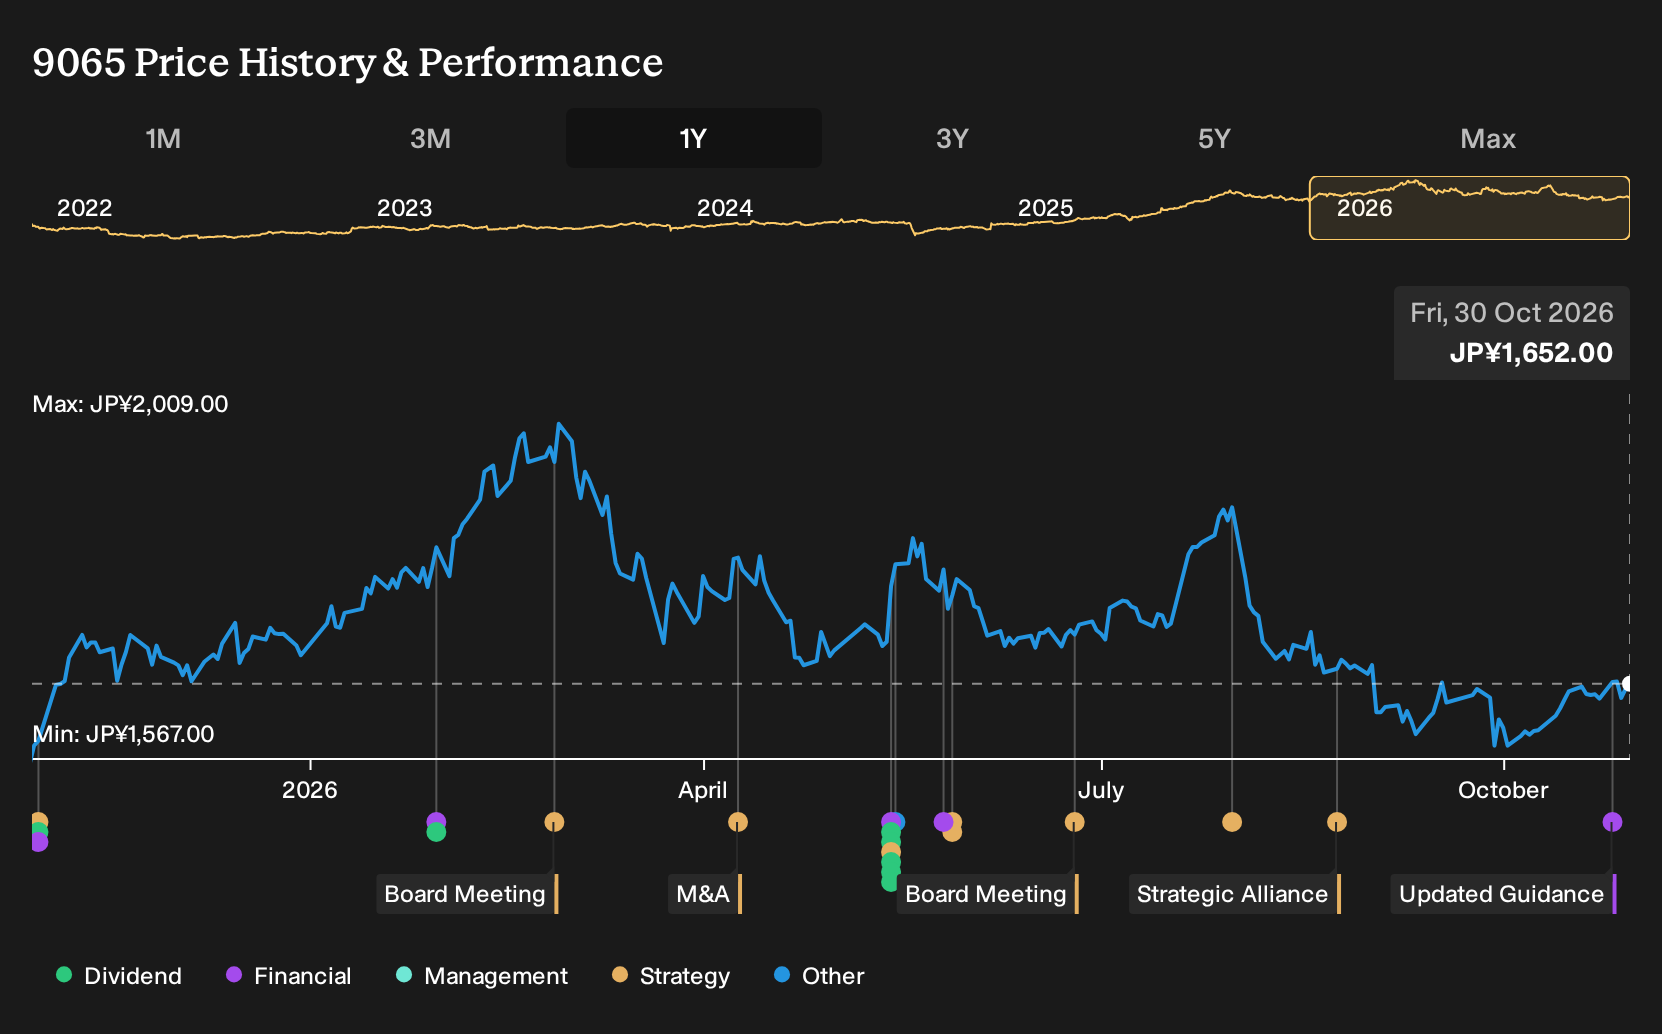
- Sankyu updated its non consolidated earnings guidance for the year ending March 31, 2027, including forecasts for net sales, ordinary profit, profit, and basic earnings per share following a late October 2026 board meeting.
- The revised outlook outlines Sankyu's expected profitability, from JPY 220,500 million in first half sales to full year profit of JPY 28,500 million, along with related earnings per share metrics.
- This article examines how Sankyu's refreshed non consolidated earnings forecast may shape the investment narrative for the business.
Scan how Sankyu's revised earnings outlook compares with other businesses updating guidance and shortlist potential ideas with the 71 high quality undiscovered gems.
What Is Sankyu's Investment Narrative?
The core belief with Sankyu is that you are backing a logistics and plant engineering platform that earns its keep through execution rather than big headline growth. Earnings have been growing, net margins sit in the mid single digits, and the stock trades on a P/E of 12.1x, which is below both peer and industry averages. The revised non consolidated forecast for the year to March 2027 simply makes explicit what management thinks is realistic on volumes, pricing and project work, rather than resetting the story.
In the short term, the guidance update points you to a business aiming for ordinary profit of ¥37,500 million on sales of ¥446,500 million, with earnings per share of ¥113.71. Those targets frame the near term catalysts around contract quality, plant engineering utilization and the capital intensity needed to support on site operations. Risks still sit around modest forecast earnings growth of 3.3% a year, slower expected revenue growth than the wider JP market, board turnover and reliance on external borrowing, and the latest guidance does not remove those.
That said, the real tension for Sankyu shareholders is whether this mix of steady logistics, capital heavy engineering and only moderate growth can offset the fact that ...
There's only one way to know the right time to buy, sell or hold Sankyu. Head to Simply Wall St's company report for the latest analysis of Sankyu's Fair Value.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Sankyu research is our analysis highlighting 6 key rewards that could impact your investment decision.
- See our latest analysis for Sankyu. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sankyu's overall financial health at a glance.
Looking For More Investment Ideas Beyond Sankyu?
If Sankyu's updated guidance has sharpened your thinking about quality and pricing power, it can be useful to line it up against other opportunities using focused stock lists built from the same underlying data.
- For investors who care most about paying less for strong fundamentals, start by scanning companies that screen as attractively priced through the 15 high quality undervalued stocks.
- If resilience and capital strength matter more to you than headline growth, filter for businesses with robust finances using the list of solid balance sheet and fundamentals (22 results).
- Income focused readers who want yield backed by real cash flows can review potential payout candidates through the 27 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com