


Kroger (KR) moved back into the spotlight after agreeing to buy Giant Eagle in a proposed US$1.65b cash and stock deal that would reshape its data rich grocery and pharmacy footprint.
The Kroger share price has climbed 13.9% over the past month and 15.6% across 90 days, a sharp contrast with more modest year to date gains of 6.0%. A 5 year total shareholder return of 75.8% points to momentum that has built over a longer horizon as investors reassess Kroger’s growth plans, data assets and risk profile around deals like Giant Eagle and its shift toward everyday low prices and higher e commerce penetration.
Scan how other grocery and retail stocks with strong data assets and e commerce plans stack up against Kroger using the 18 high quality undiscovered gems.
After a 13.9% one month jump and a US$1.65b Giant Eagle deal on the table, does Kroger still offer an appealing risk reward entry, or has the easy upside already been priced in ahead of valuation work?
Most Popular Narrative: 1.7% Overvalued
Kroger last closed at $66.76 against a most-followed narrative fair value of $65.65, so the stock screens as slightly rich with investors still focused on execution in e-commerce, media and cost savings.
The central narrative tension of the latest call is the gap between two clean stories: cost discipline working exactly as committed, and the sales line missing the guidance range. Foran’s response was to present these as compatible, a demonstration that the financial model works even when top-line conditions don’t cooperate. “These results demonstrated the strength and flexibility of our operating model in a challenging sales environment” was the direct formulation. This is a real argument, not a deflection, because the cost savings mechanism did hold. But the argument requires the listener to accept that a sales miss is a stress test passed rather than a signal worth investigating on its own terms.
See why 3 investors see Kroger as 2% overvalued.
Result: Fair Value of $65.65 (OVERVALUED)
Still, Kroger’s narrative could be challenged if cost savings slow or if softer tickets and unit trends persist, even with increased value and e-commerce investment.
Find out about the key risks to this Kroger narrative.
Another View On Kroger’s Value
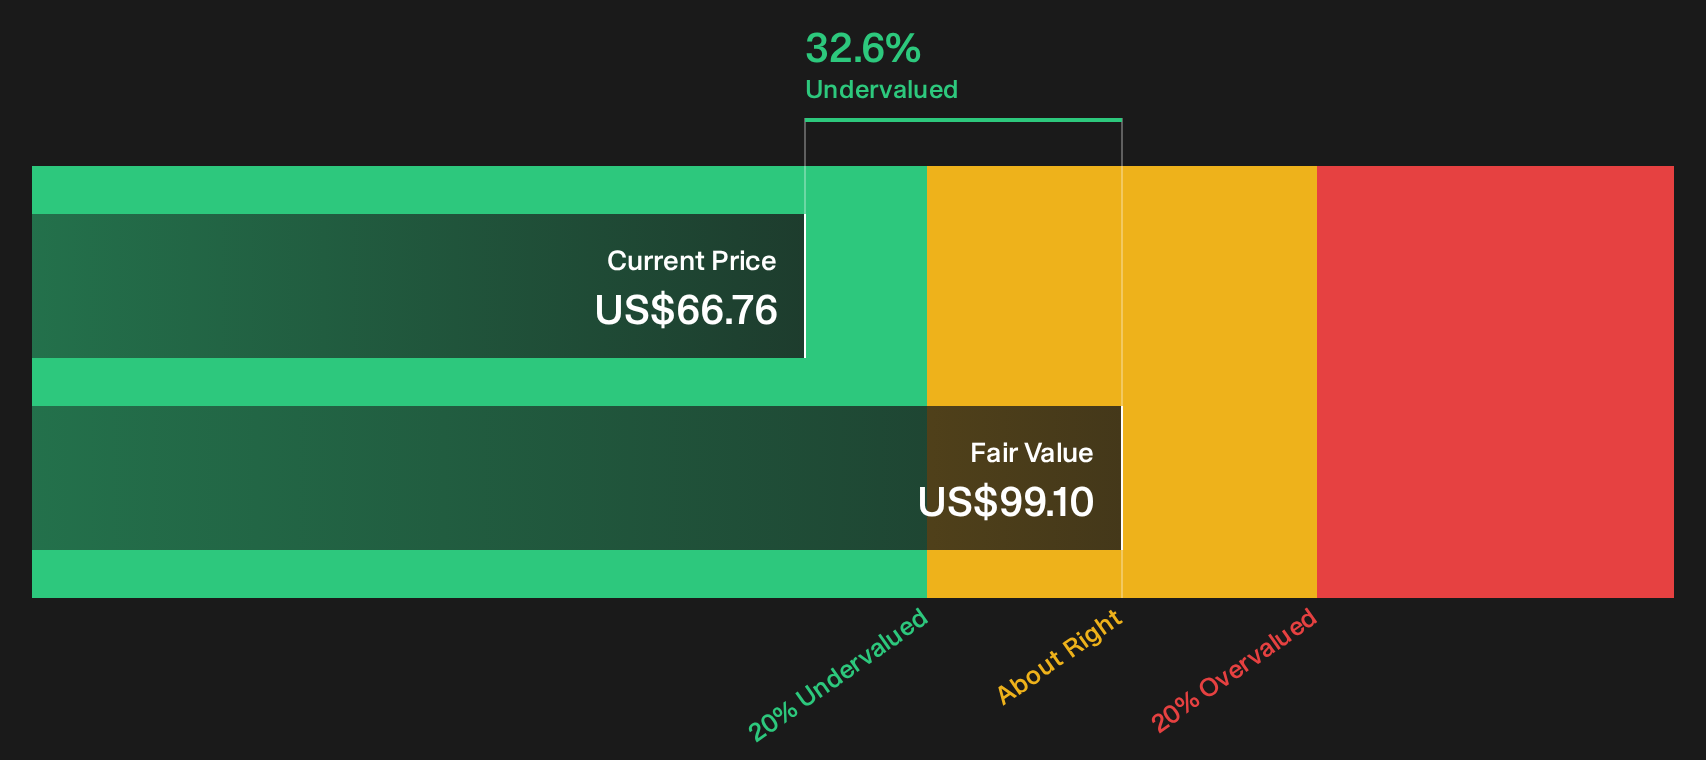
The community narrative pegs Kroger at 1.7% above its fair value of $65.65, yet the SWS DCF model points in the opposite direction. On that framework, the shares at $66.76 are trading below an estimated future cash flow value of $99.10, which screens as undervalued.
If the narrative says slightly expensive but the cash flow math says cheap, which lens do you lean on for a Giant Eagle sized bet?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kroger for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed views on Kroger’s value and deal risk are clear. Move quickly, review the underlying data, and weigh the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Kroger?
If Kroger has sharpened your focus on pricing power, data and balance-sheet strength, broaden your watchlist now with a few targeted idea lists built for different goals.
- Target reliable cash generators by scanning a 5 dividend fortresses that focuses on income potential backed by meaningful yield and financial resilience.
- Hunt for quality at a discount through the 29 high quality undervalued stocks that highlights businesses where fundamentals and valuation may not yet line up in the market.
- Prioritize capital protection first by reviewing a 30 resilient stocks with low risk scores that surfaces resilient companies with lower overall risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com