


CoreCivic has seen its share price move sharply over recent years, which puts a spotlight on whether the current valuation is adequately supported by the company’s earnings power. With that backdrop, the key issue for you is whether the recent share price level can be explained by what the business is actually generating in profit.
- Over the past 5 years, CoreCivic has delivered a 222.7% total return, which raises the question of how much of that performance lines up with the underlying earnings profile.
- The business model is heavily tied to long term contracts and facility utilization, which can shape how reliably CoreCivic converts reported profit into cash and how investors think about the durability of its earnings base.
- There is a second opinion on CoreCivic worth weighing. See what analysts think CoreCivic's shares could be worth.
The stock’s next move may depend on whether CoreCivic’s earnings are strong and resilient enough to make today’s share price look well supported.
If you are weighing whether CoreCivic’s earnings justify its recent share price run, it can help to compare that question with other companies screened for 29 high quality undervalued stocks
Does CoreCivic Look Pricey on Earnings?
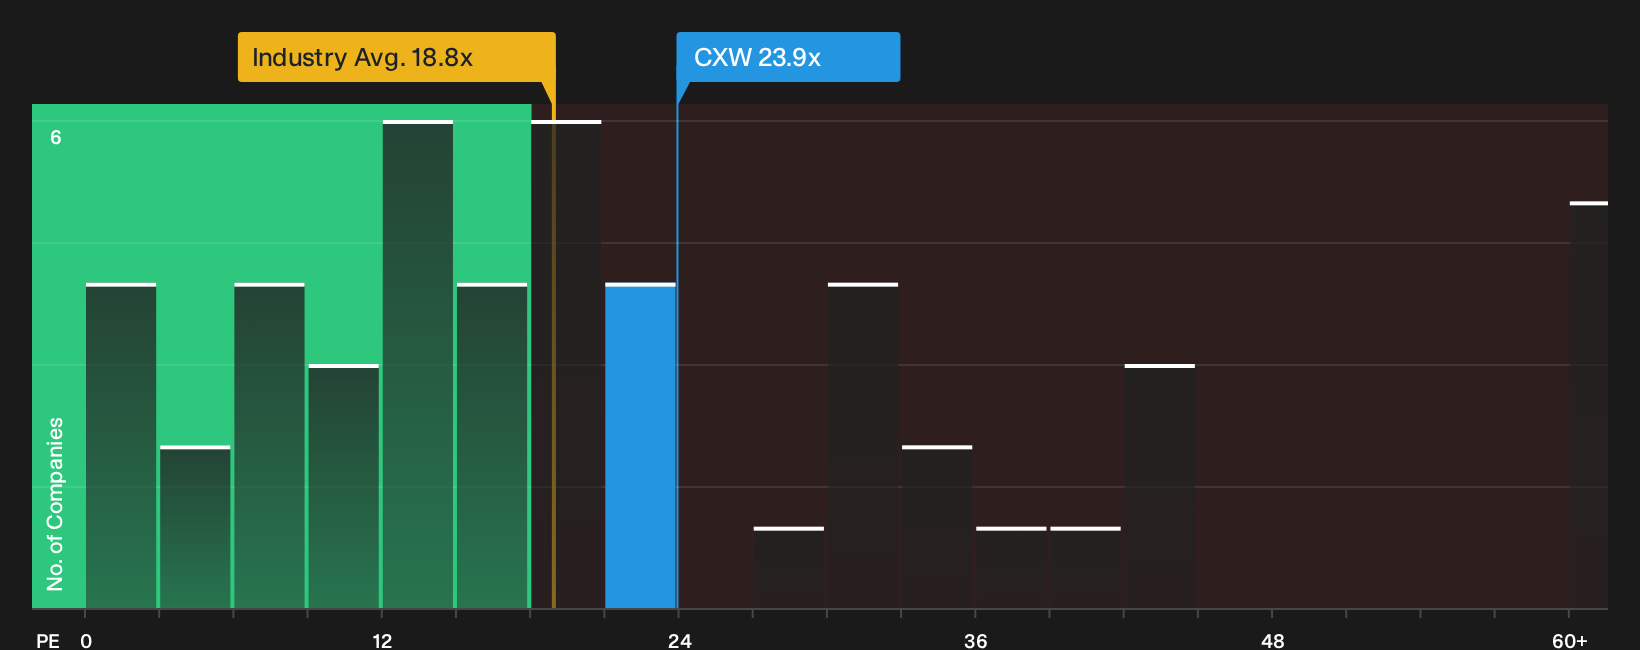
The P/E ratio is a useful lens for CoreCivic because earnings are a key yardstick for a contract driven operator. Right now the stock trades on roughly 23.9x earnings, compared with about 18.8x for the wider Commercial Services group and around 18.4x for peers in its comparison set. That is a clear premium to what investors are paying, on average, for similar businesses in the sector.
A tailored model that weighs CoreCivic’s margins, risk profile and scale points to a lower P/E as a more typical level for this kind of earnings stream. On this framework, the current multiple screens as overvalued. The gap is large enough that the model is effectively highlighting how much investors are willing to pay for the existing profit base, rather than offering a precise target level for the shares. If you are comfortable with that trade off, the current valuation may still make sense in your portfolio. Explore the numbers behind CoreCivic's P/E valuation.
The CoreCivic Narrative: What Would Justify Today's Price?
CoreCivic’s current P/E question sets up the role of Simply Wall St Narratives. These walk through the specific future path for CoreCivic's earnings, margins and growth expectations that would need to hold for the stock to trade meaningfully above or below today’s price. Where a single ratio or model gives one figure, they unpack the future scenario that figure rests on so you can watch how reality lines up.
One of the top community narratives on CoreCivic: 26% undervalued
"The combination of roughly US$1b of expected cash, reduced debt of about US$739.1 million, sizeable revolver capacity and a remaining US$755.8 million buyback authorization gives CoreCivic room to deploy capital into further share repurchases..."
Discover why this Narrative puts CoreCivic at 26% undervalued.
One more CoreCivic factor that deserves your attention
Before you lean too heavily on the earnings and multiples story for CoreCivic, it is worth checking the specific cautions our broader checks have flagged for this business. Take a closer look at 3 warning signs (2 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com