


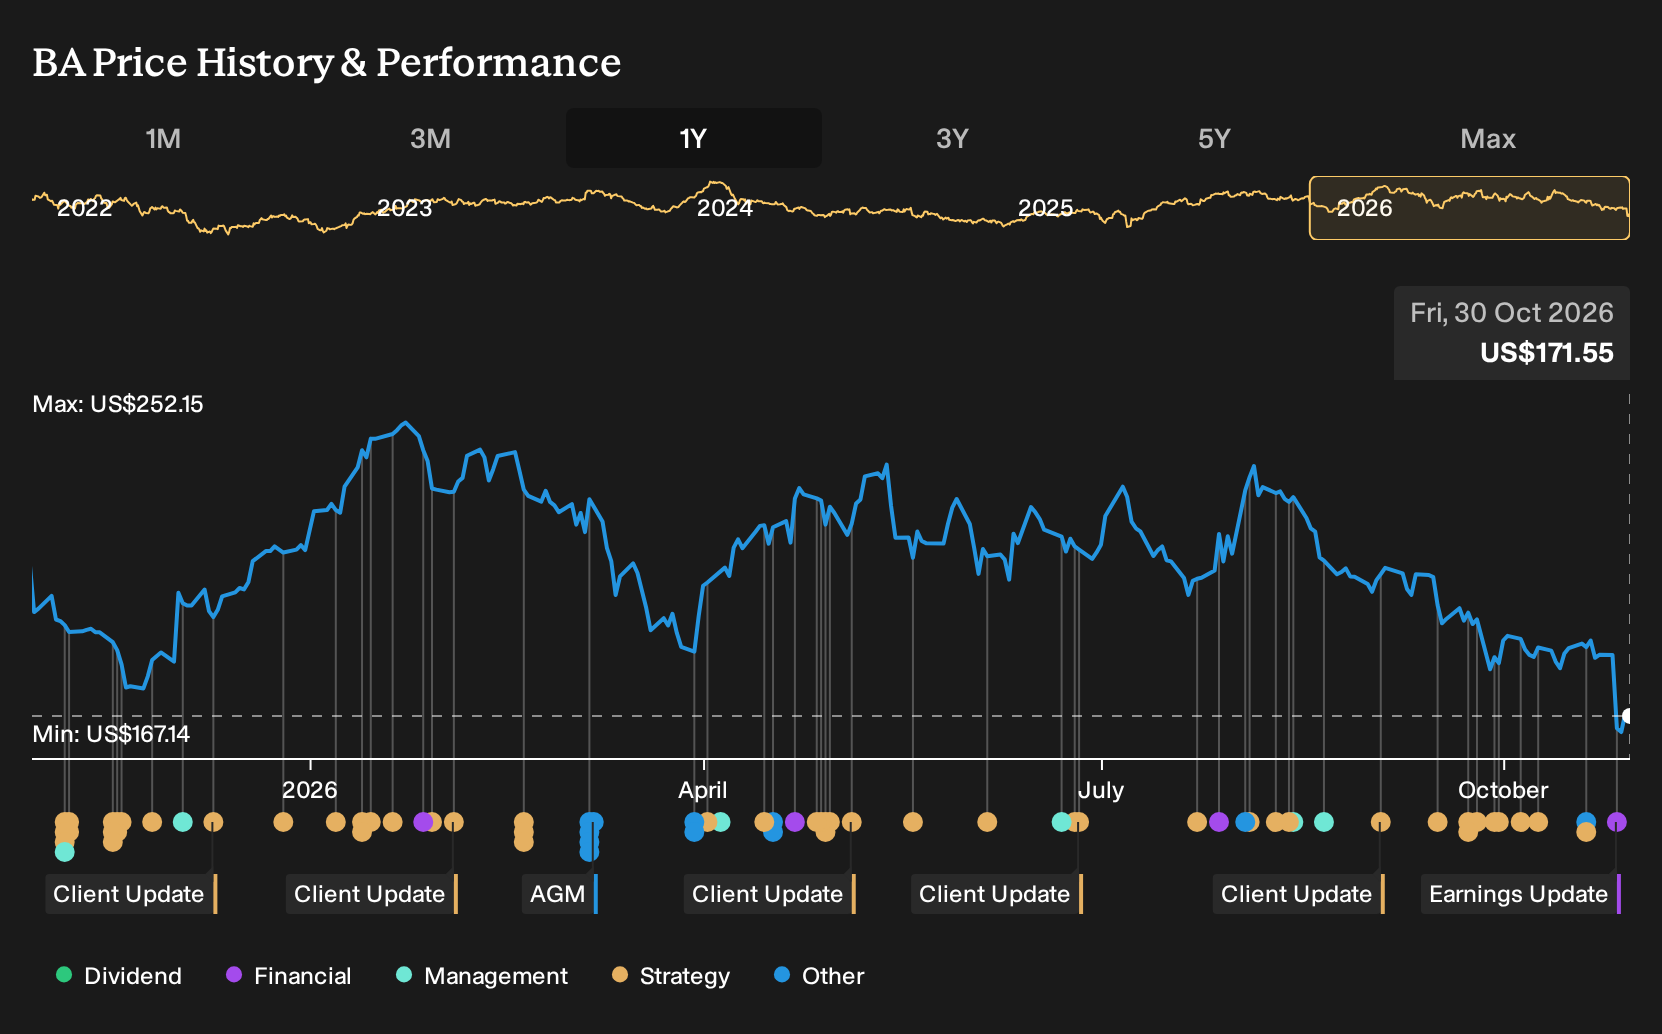
- Boeing reported a Q3 2026 basic and diluted loss per share from continuing operations of US$0.26, compared with US$7.14 a year earlier, while management discussed continued production and supply chain issues, particularly around the 737 program.
- Despite a record backlog and solid defense and air cargo demand indicators, Boeing's delayed free cash flow ambitions and slower 737 stabilization underline that execution pressure, cost control, and manufacturing reliability now sit at the center of the story.
- We will look at how Boeing's investment narrative is tested by ongoing 737 production delays and the pushout of long term cash targets.
Boeing Investment Narrative Recap
To own Boeing, you need to believe that a record backlog in commercial jets, a growing services arm, and a larger defense footprint can eventually outweigh the current production headaches and cash strain. The latest quarter still showed a loss per share from continuing operations, although far smaller than a year ago, which keeps the focus squarely on execution and cash conversion.
The near term catalyst remains credible progress on stabilizing 737 output and turning that backlog into deliveries without fresh quality or regulatory setbacks. The biggest risk is that supply chain friction, program losses in Commercial Airplanes, and heavy debt continue to drag on operating cash flow longer than management expects.
The most relevant recent development for this story is FAA certification of the 737 10. That decision closes a long running certification overhang and completes the 737 MAX family, with the 737 10 representing more than 30% of Boeing's unfilled 737 MAX orders and over 1,500 aircraft in the book.
That approval gives Boeing a clearer path to start delivering a high capacity, lower per seat cost narrowbody at a time when the firm already faces delays ramping 737 production. Turning those 737 10 commitments into on time handovers now sits alongside free cash flow delivery as a practical test of management's ability to manage risk, support the backlog, and keep future earnings targets credible.
Boeing's narrative projects US$125.6b revenue and US$7.9b earnings by 2029. That outlook is built on analysts assuming 10.9% yearly revenue growth and an earnings increase of about US$6b from US$1.9b today.
Uncover why Boeing's fair value indicates a 42% potential upside to its current price, which could narrow quickly as execution risks ease.
Exploring Other Perspectives
One alternate lens on Boeing focuses on margins rather than backlog. The most pessimistic analysts already pencilled in revenue of about US$124.0b and earnings of roughly US$6.3b by 2029, well below the consensus US$125.6b and US$7.9b path. Those pre Q3 views could shift when comparing fresh 737 production headlines with these older margin assumptions.
Explore 5 other Boeing fair value estimates, including one that suggests it could be worth just $221.36.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Boeing research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Boeing. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Boeing's overall financial health at a glance.
Looking for more Boeing investment ideas?
If Boeing is on your radar because of its scale, backlog, and moving parts, it can help to compare it with other businesses that share some of those traits or offer a very different risk profile. The Simply Wall St Screener lets you filter for exactly the mix of quality, balance sheet strength, and potential you are comfortable with.
- For investors who want upside potential with less financial strain, start with companies that pair steady operations with strong balance sheets using this list of solid balance sheet and fundamentals (25 results).
- If your focus is on resilient businesses that aim to limit downside risk, you can look at more defensively positioned opportunities by checking this 30 resilient stocks with low risk scores.
- For readers who like the idea of finding the next Boeing before it is widely followed, scan through this 18 high quality undiscovered gems and compare the fundamentals side by side.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com