


If you only skimmed the headlines on Jackson Financial over the past year, you saw strong annuity demand and product awards sitting next to a GAAP loss, fresh credit lines, and even short-seller reports questioning a key reinsurer. Investors who held Jackson Financial over the past year are up 38.1%, including dividends. If you had been weighing that kind of return against concerns about solvency metrics and hedging losses, what should have mattered most at the start?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
Jackson Financial has already moved. See which of 29 high quality undervalued stocks still trade below our estimates.
The Two Jackson Financial Stories Investors Had To Weigh
The shares cost US$98.59 at the start of the period, so anyone looking at Jackson Financial then had to decide which narrative felt more realistic.
The bullish view put Fair Value at US$116 and leaned on long-term retirement trends. It treated expanding annuity demand and Jackson’s diversified suite, including variable annuities and RILAs, as the engine for higher fee-based earnings.
The more cautious narrative set Fair Value at US$88. It focused on pressure from variable annuity net outflows and the risk that higher lapse rates could strain cash flow and future earnings stability.
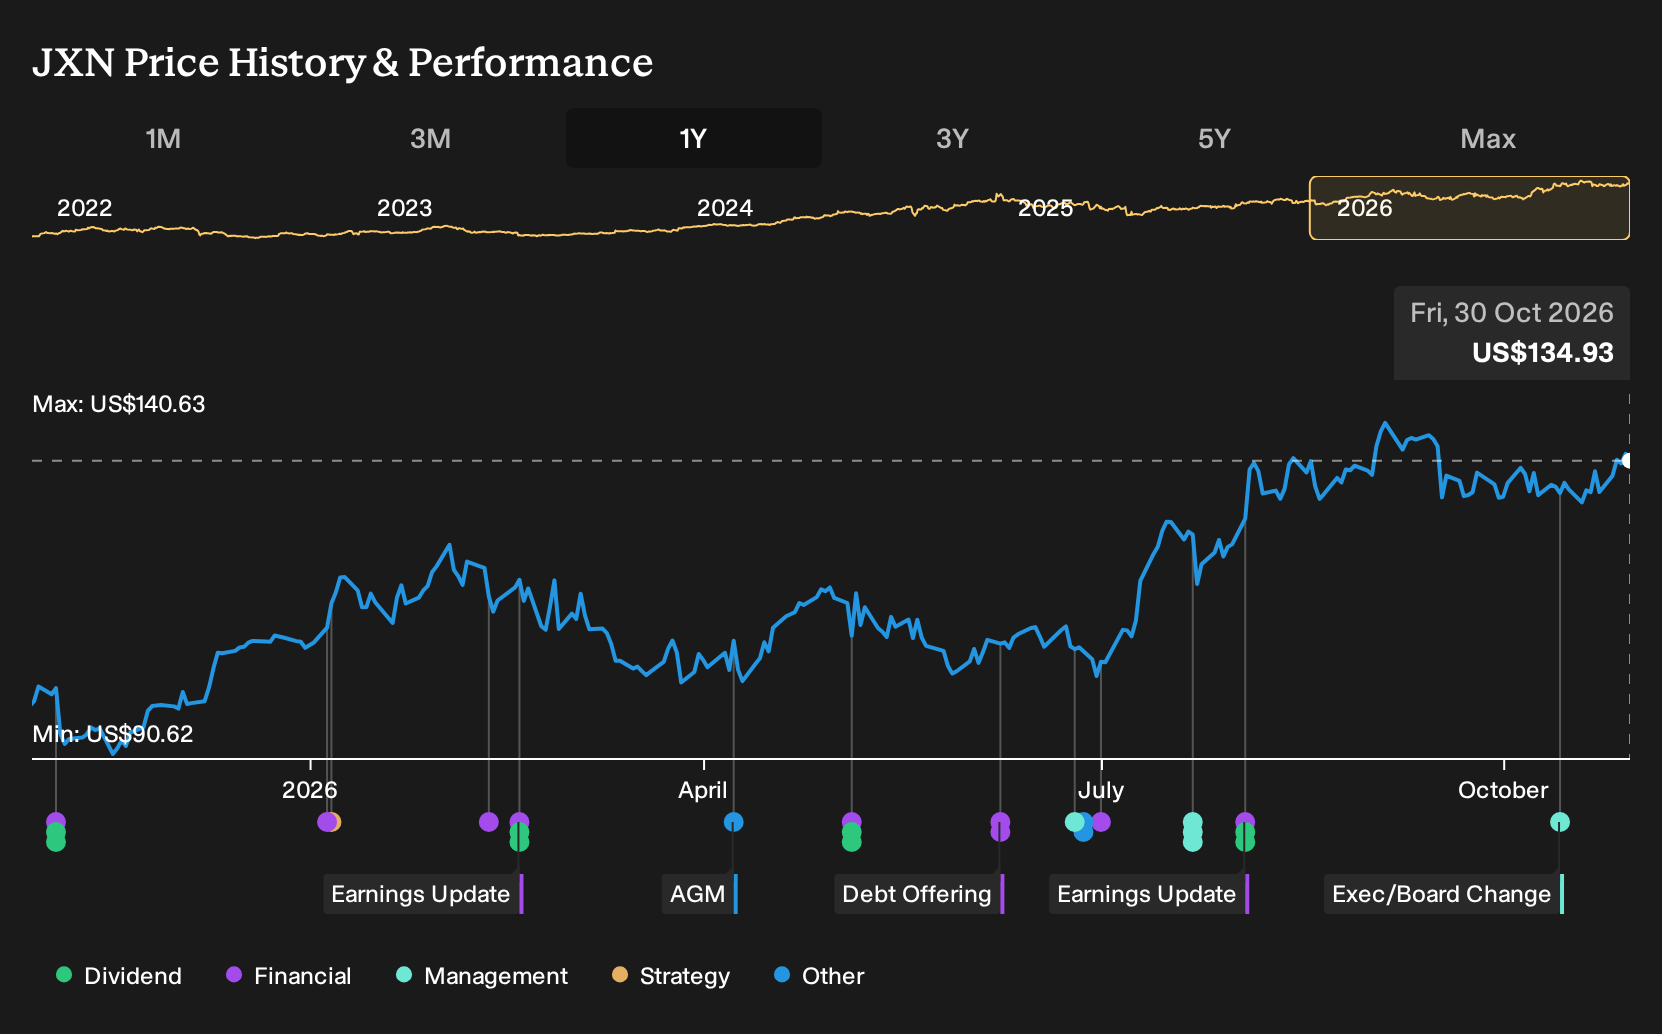
What The Results Changed For Jackson Financial
Jackson Financial’s Q2 2026 results showed revenue at US$168 million and net income at US$644 million, compared with US$471 million lower revenue and US$168 million profit a year earlier. Strong retail annuity sales, new RILA and fixed index products, and awards supported the demand narrative. Short-seller reports and the Pomerantz investigation around Brooke Re raised questions about solvency metrics, so the evidence pointed in both directions.
The main lesson is simple. When a thesis leans on capital strength and hedging, it is important to track reported solvency ratios, reinsurance terms, and any external scrutiny of those numbers for every insurer you research.
What Jackson Financial’s Price Implies Today
Jackson Financial now trades at US$135. The selected Narrative’s Fair Value sits above the current price and leans on strong statutory and free capital generation supporting ongoing capital returns.
For that higher figure to be reached, a buyer today would need to believe Jackson can keep managing variable annuity hedging and captive reinsurance risks within a conservative balance sheet.
"The main factor is that Jackson Financial continues to generate strong statutory and free capital while managing variable annuity hedging and captive reinsurance risks within a conservative balance sheet. The numbers imply that Jackson Financial’s current share price does not fully reflect the scale of its capital generation, liquidity and capital returns to date."
The price and this Narrative do not agree. → Uncover what this Narrative says Jackson Financial is actually worth
Go Straight To The Source
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 30% below our estimate - embeds AI across infrastructure, productivity software and developer tools for recurring demand.
- Company 2 - 48% below our estimate - converts a large project backlog in data center and modular builds into greater capacity utilization.
- Company 3 - 35% below our estimate - targets demand for data center GPUs as customers expand AI workloads alongside power needs.
Those are three of them. See all 25 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com