


Extreme Networks (EXTR) just paired a stronger first quarter with fresh guidance and a new push into on premises enterprise AI. Revenue reached US$341.09 million, with net income at US$15.98 million.
The share price reaction has been mixed. Extreme Networks is up 36.7% on a year-to-date share price return and the 1-year total shareholder return is 18.9%. However, the stock is down about 25% over the past three months as investors reassess how the new AI roadmap and fresh guidance change the risk and reward balance around US$22.61 a share.
Scan other AI infrastructure plays that are lining up behind Extreme Networks' on-prem push by checking our hand-picked 54 AI infrastructure stocks, which is built around the same enterprise compute and networking theme.
Bulls point to Extreme Networks’ higher earnings, on premises AI roadmap, and the discount to analyst targets. Bears focus on recent share price volatility and execution risk on new products. Which case does the current valuation lean toward?
Most Popular Narrative: 32.5% Undervalued
The most followed narrative puts Extreme Networks' fair value at $33.50, well above the last close at $22.61. This frames current pricing as a steep discount tied to how investors view the AI platform rollout and recurring revenue story.
Successful roll-out and growing adoption of AI-powered Extreme Platform 1 and automated cloud management solutions position the company to capitalize on the acceleration of edge computing, automation, and AI-driven networking, which should drive higher SaaS ARR growth, recurring revenue, and improved net margins.
See why 14 investors see Extreme Networks as 33% undervalued.
Result: Fair Value of $33.50 (UNDERVALUED)
Still, the story around Extreme Networks can change quickly if large government deals become less frequent, or if bigger rivals squeeze pricing and pressure margins.
Find out about the key risks to this Extreme Networks narrative.
Another View: Extreme Networks And Richer Multiples
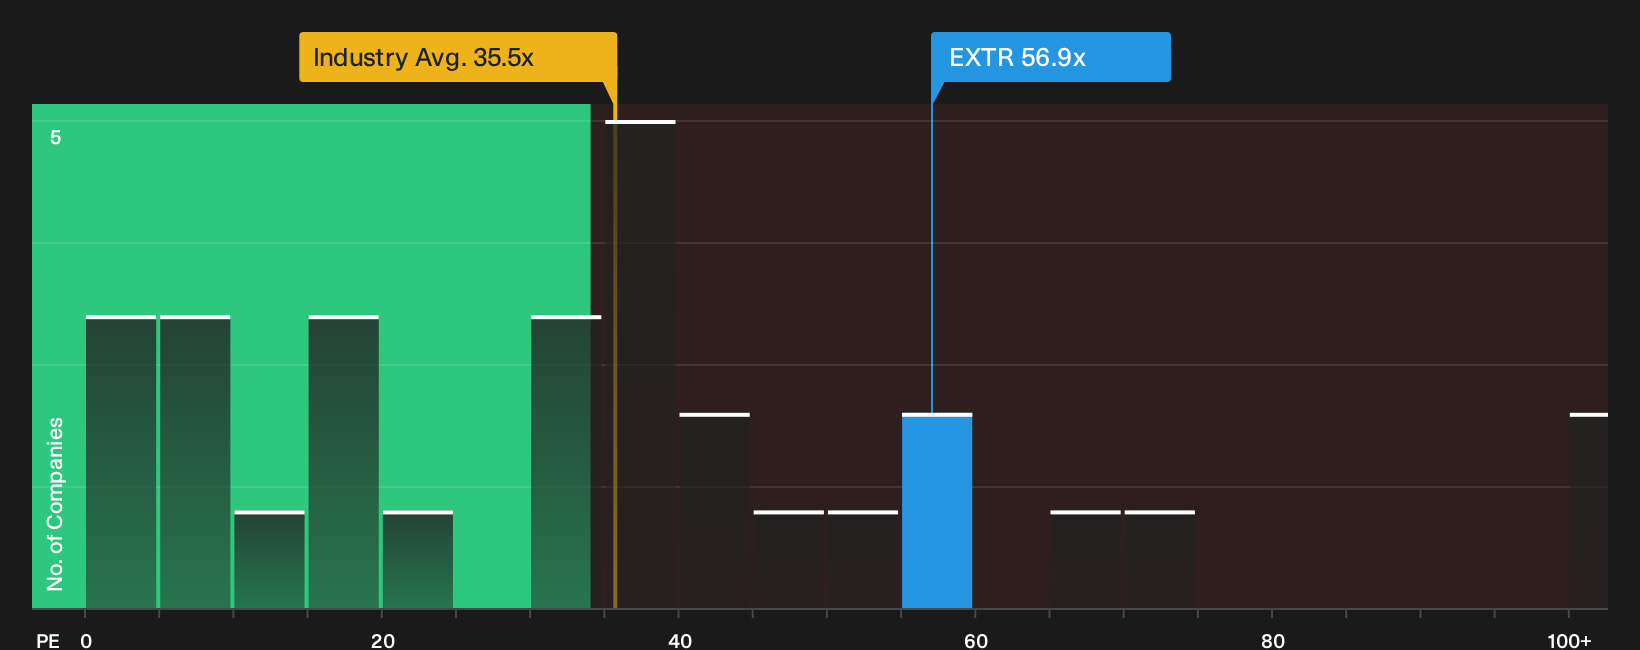
The fair value narrative for Extreme Networks leans on discounted cash flows and long term forecasts. A different lens looks at what investors are paying right now. On a P/E of 56.9x, compared with a peer average of 35.3x and a fair ratio of 25.1x, the stock carries a hefty premium that could amplify any disappointment.
If you put more weight on this kind of earnings multiple, the high gap to both peers and the fair ratio points to valuation risk rather than a clear bargain. The question is which signal you trust most when expectations are already this full.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
So after all this, are you leaning bullish or cautious on Extreme Networks, or still undecided and watching how the thesis evolves? To pressure test the optimism that some investors already see in the story, take a closer look at the 4 key rewards
Looking for more investment ideas beyond Extreme Networks?
If Extreme Networks has sharpened your thinking on valuation and risk, do not stop here. Broader context across sectors can really tighten your decision making.
- Target potential upside in quality names that trade below analysts’ implied worth by running a focused search through the 29 high quality undervalued stocks.
- Prioritize resilience and sleep-better-at-night holdings by scanning the 30 resilient stocks with low risk scores, which filters for businesses with sturdier risk profiles.
- Spot under-the-radar opportunities before the crowd arrives by checking the 18 high quality undiscovered gems, a tool that highlights strong fundamentals hiding in plain sight.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com