


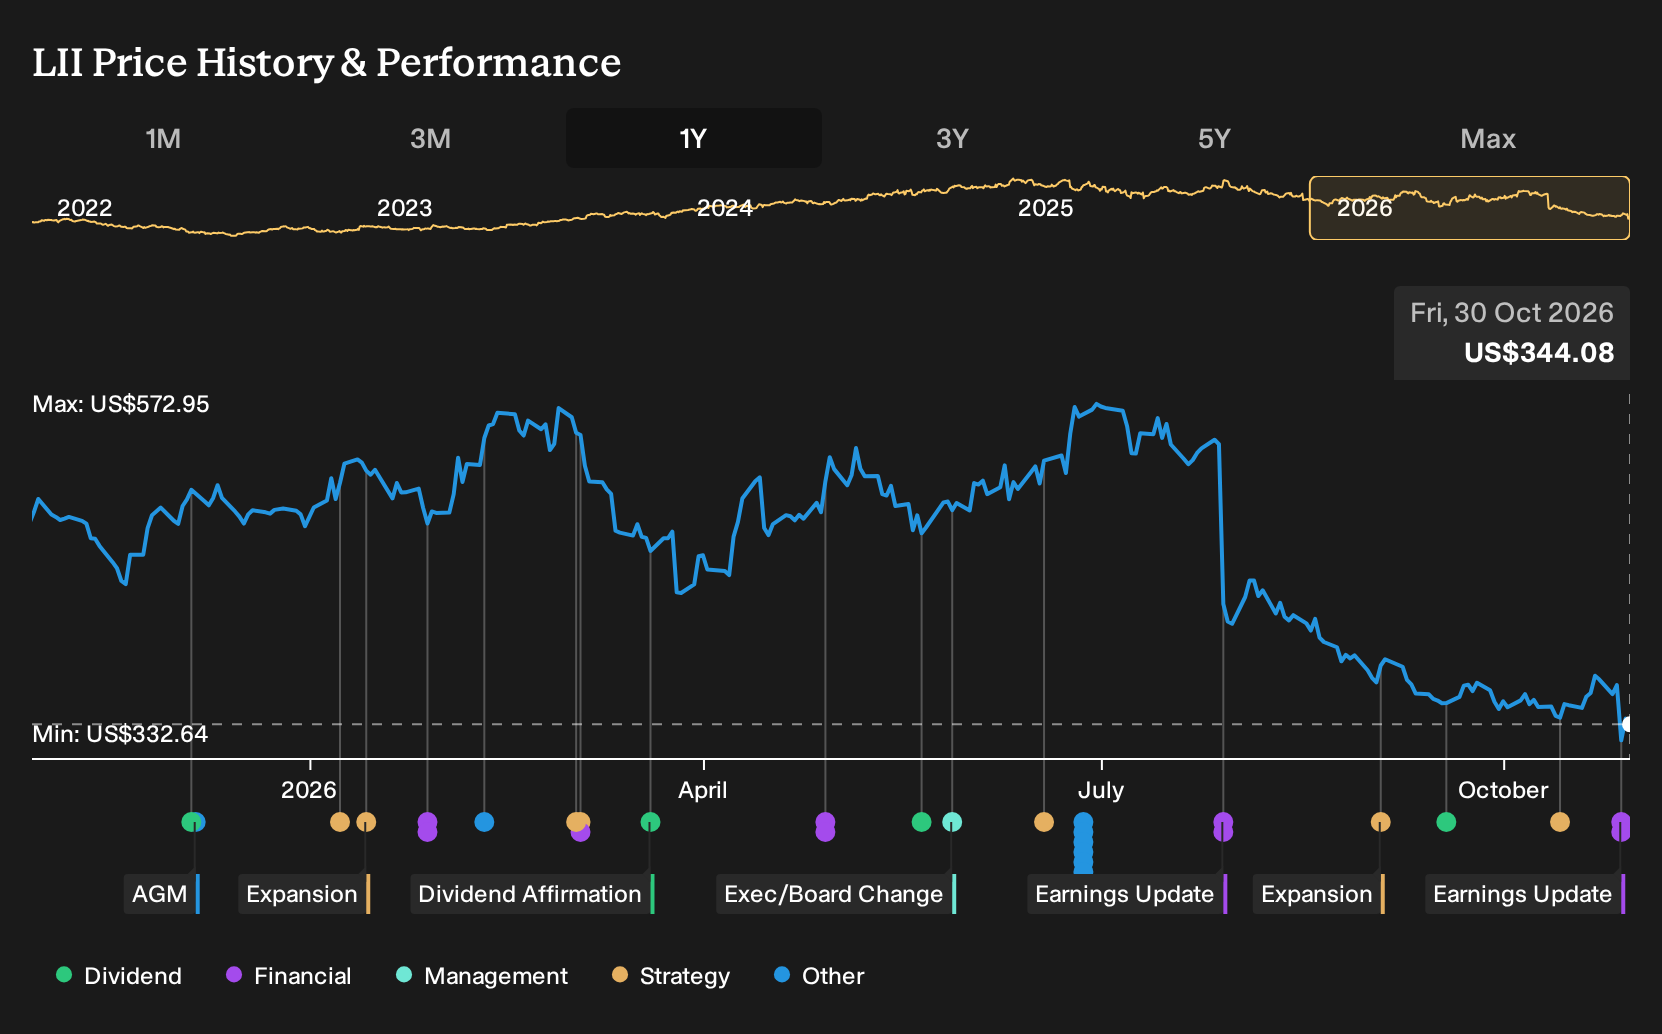
Lennox International’s brutal summer came into focus when its Q2 2026 earnings miss and lower guidance were followed by a single day drop of almost 20% after the update. Holding Lennox International over the past year would have meant a 31.1% loss, including dividends. If you had committed fresh capital in late October 2025, that is the experience you would now be trying to explain. The key question is whether today’s pressures point to a temporary squeeze or a deeper reset in how this business earns its money.
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
The easy part of this move is behind Lennox International. Zero in on 29 high quality undervalued stocks for companies trading below our estimates.
The Two Stories Investors Were Weighing On Lennox International
The shares cost US$496 at the start of the period, and anyone looking at Lennox International then had to pick between two very different stories about where value might sit.
On the bullish side, the narrative pointed to a fair value of US$637, built on assumptions such as 4.2% revenue growth and a 16.8% profit margin, supported by AI-based pricing tools and share buybacks.
The more cautious view argued for a fair value of US$470, emphasizing risks such as heavy North American reliance and the possibility that greater competition in energy-efficient technologies could compress pricing power.
What The Results Changed For Lennox International
The biggest new fact for Lennox International is that Q3 2026 revenue reached US$1.57b compared with US$1.43b a year earlier, which leans toward the optimistic growth case. Net income slipped from US$259.9m to US$221.2m and net margin moved from 18.2% to 14.1%. That profitability squeeze gave clear support to the cautious story about pricing power and competitive pressure.
The lesson is simple. When a thesis leans on margin strength, do not just watch sales. Track net margin and segment profit in each report to see whether pricing and costs are actually holding up.
What A Buyer Of Lennox International Is Really Paying For Today
Lennox International now trades at US$344, down 31.1% over the past year. The selected Narrative places its Fair Value above that level, based on confidence in higher margin commercial HVAC, services and heat pump exposure despite recent pressure on profitability and sentiment.
This view leans on one big assumption you would need to judge. Commercial and aftermarket expansion must keep adding enough higher quality earnings to offset weaker residential demand and factory under absorption.
"The main priority is continued execution on expanding higher margin commercial HVAC, parts and services, and heat pump offerings while managing residential demand softness and factory absorption headwinds. The current valuation is described as not fully reflecting the margin expansion already delivered, the cash flow outlook, or the potential earnings contribution from commercial growth and acquisitions, which is why this narrative characterizes Lennox International as undervalued with a bullish view."
One Narrative disagrees with today's price. → See where this Narrative says Lennox International should trade
Go Straight To The Source
Passing on this one could have spared you a loss. Where might you find the opposite surprise? Start looking for companies whose prices leave room for a better outcome than investors expect. These three trade below our estimated value.
- Company 1 - 36% below our estimate - turns shorter brownfield tieback cycles into subsea equipment and services revenue growth.
- Company 2 - 30% below our estimate - ties cloud infrastructure, office software and AI assistants into one recurring subscription platform.
- Company 3 - 48% below our estimate - converts a record backlog of data center and modular builds into ongoing service contracts.
Those are three of them. See every one of the 25 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com