


- Bank OZK reported third quarter 2026 results with net interest income of US$402.99 million and net income of US$168.36 million, both lower than the same period in 2025, while diluted EPS from continuing operations came in at US$1.50.
- The nine month numbers show net income of US$499.1 million and diluted EPS of US$4.43, which may sharpen investor focus on how Bank OZK manages profitability pressures across lending and fee businesses.
- Next, the focus turns to how Bank OZK's investment narrative holds up against softer net income in the latest quarterly report.
See how Bank OZK compares with other regional banks managing earnings pressure by reviewing the hand picked list of solid balance sheet and fundamentals (25 results) in the current rate backdrop.
Bank OZK Investment Narrative Recap
To own Bank OZK, you need to be comfortable with a real estate heavy lender that is trying to rebalance toward more diversified Corporate and Institutional Banking and fee income. The third quarter figures, with net interest income and net income both soft versus 2025, keep the spotlight on how effectively that shift supports earnings resilience.
The most immediate swing factor is whether loan repayments in the Real Estate Specialties Group stay elevated and keep average earning assets under pressure. The biggest near term risk remains concentrated credit exposures in office and life science projects, where any rise in charge offs or provisions would add to the profit headwinds already visible in the nine month results.
Recent commentary around management’s plan to reduce Real Estate Specialties Group exposure by late 2026 or early 2027 ties directly into these earnings. With nine month net income of US$499.1 million and diluted EPS of US$4.43, investors are watching how quickly capital can be reallocated toward more diversified commercial and Corporate and Institutional Banking portfolios.
The same narrative around Corporate and Institutional Banking buildout, with multiple lending verticals and fee opportunities, matters more after a quarter of softer net interest income. Execution on that expansion, plus progress in growing fee based services such as treasury, wealth and trust, sits alongside credit quality in large office and life science loans as the key operational test after this latest earnings update.
What The Current Analyst Framework Implies For Bank OZK
Bank OZK now has a fairly clear analyst playbook attached to it. The forecasts link the CIB buildout, RESG runoff and fee push directly to where revenue and profit might land over the next few years, and that in turn shapes how some investors think about the stock today.
Consensus assumptions point to annual top line expansion of 9.5% over the next three years. At the same time, analysts model profit margins easing from 43.5% earnings today to 33.8% by 2029. That combination bakes in faster revenue progress than profit progress and reflects the cost and mix trade offs involved in shifting away from a real estate heavy loan book toward a broader Corporate and Institutional Banking and fee mix.
On the earnings line, analysts currently estimate profit of US$675.1 million, with a consensus path toward US$690.2 million by 2029. That is an earnings increase of about US$15.1 million over the period. For context on per share metrics, forecasts call for EPS of US$6.93 by 2029 and a share count that gradually declines by roughly 2.54% a year over the next three years, supported by ongoing repurchases.
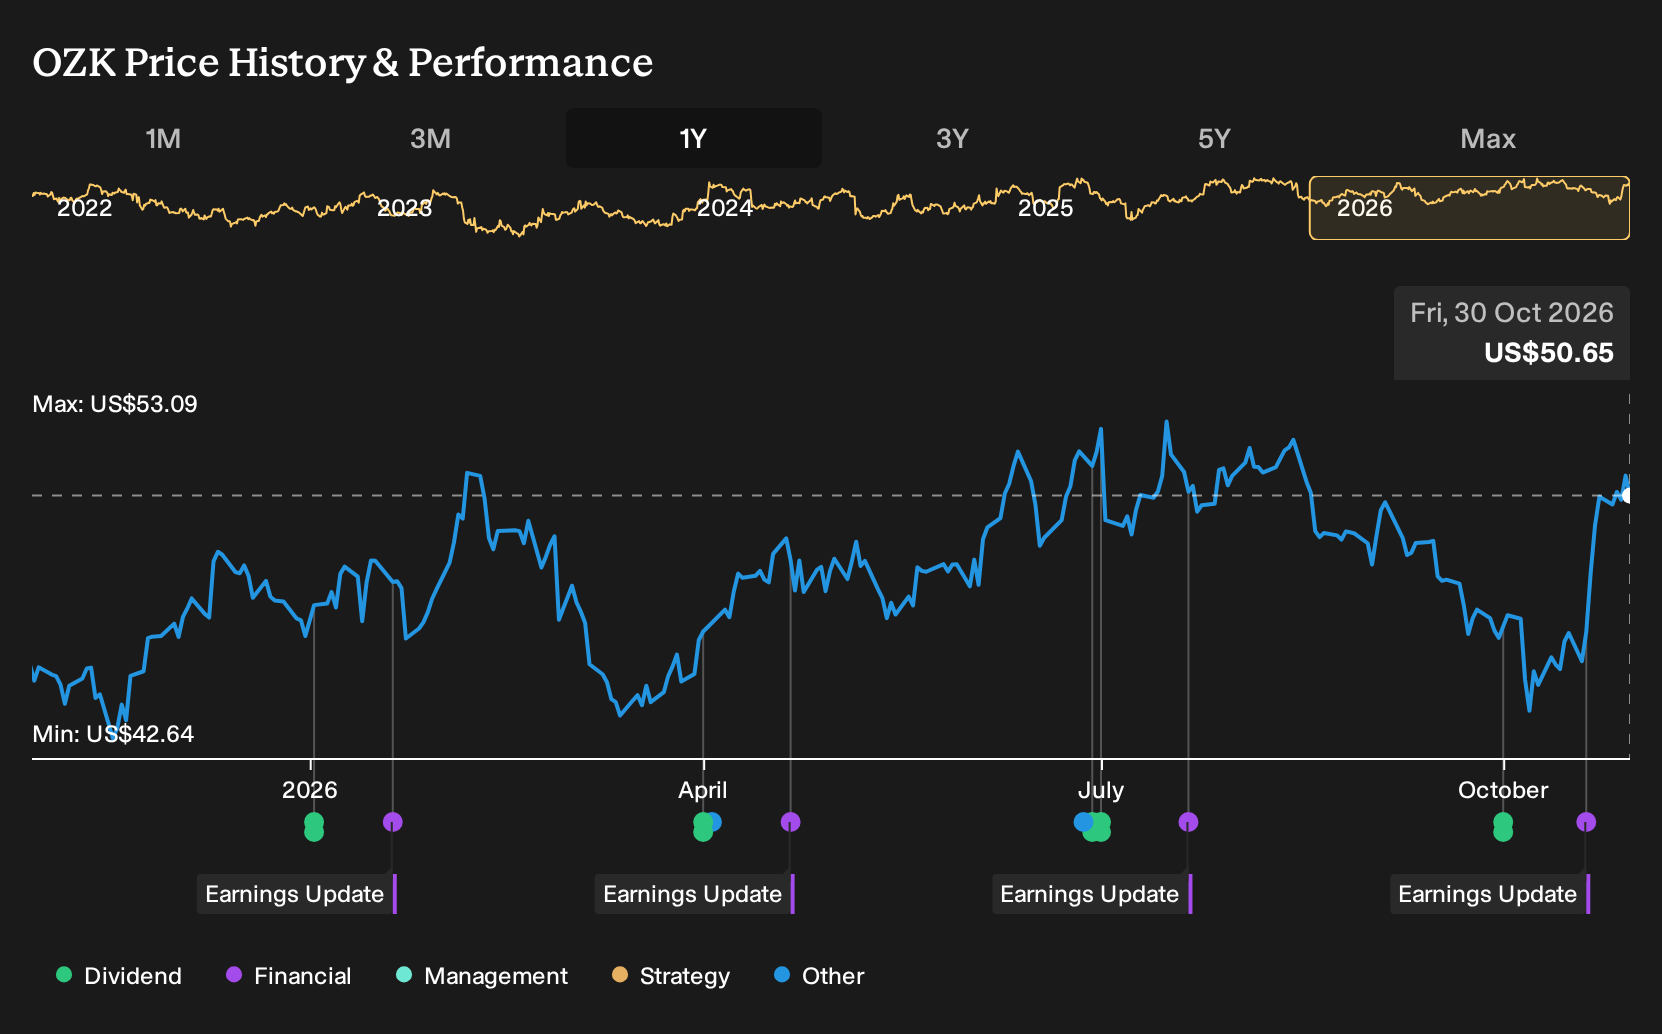
The valuation bridge then ties these operating assumptions back to what some investors are willing to pay. The analyst group is using a discount rate around 7.2% to 7.24% and a future P/E multiple of 9.7x applied to those 2029 earnings, compared with a current P/E they quote at 7.0x and an industry level around 11.4x. That puts a consensus price target at US$53.78, with a bullish view at US$65.00 and a cautious view at US$40.00, versus a spot share price reference of US$43.56 in the report.
For anyone tracking whether that framework feels realistic, the moving parts are clear. Revenue growth assumptions rely on Bank OZK turning its Sun Belt presence, CIB platform and fee franchises into higher earning assets and steadier noninterest income. Profit margin compression depends on RESG runoff, deposit costs and loan pricing trends, along with how much investment is needed to keep building out corporate, wealth, mortgage and treasury capabilities. The P/E re rating case then hinges on whether earnings quality and growth look stronger or weaker as the CRE concentration comes down.
Bank OZK's narrative projects US$2.0b revenue and US$690.2 million earnings by 2029. This requires 9.5% yearly revenue growth and an earnings increase of about US$15.1 million from current earnings of US$675.1 million.
Uncover why Bank OZK's fair value indicates a 6% potential upside to its current price, a gap that could narrow quickly if sentiment turns.
Exploring Other Perspectives
One bullish angle on Bank OZK leans heavily on the new US$200 million buyback program as a potential catalyst. Those optimistic analysts were penciling in revenue of about US$2.1b and earnings near US$674.3 million by 2029 before this weaker quarter. You can treat today’s softer results as a prompt to compare those upbeat expectations with more cautious views, then decide which story now feels closer to reality.
Explore 4 other Bank OZK fair value estimates, including one that suggests as much as 140% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Bank OZK research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Bank OZK. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bank OZK's overall financial health at a glance.
Looking For More Investment Ideas Beyond Bank OZK?
Once you have a view on Bank OZK, it can help to widen the lens and compare it with other businesses that share similar qualities or offer different types of opportunities. The Simply Wall St Screener groups stocks by traits that matter to you, so you can build a watchlist that actually fits your approach.
- For investors who want potential upside without ignoring quality, take a look at a hand picked selection of 29 high quality undervalued stocks that combine stronger fundamentals with more modest expectations baked into the price.
- If capital preservation and steadier profiles are a priority, consider scanning a curated 30 resilient stocks with low risk scores that focuses on businesses with more resilient characteristics.
- Readers hunting for earlier stage opportunities can review a focused 9 elite penny stocks with strong financials that filters for stronger financials within the lower priced part of the market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com