


- WesBanco reported third quarter 2026 net interest income of US$226.88 million and net income of US$89.51 million, with basic earnings per share from continuing operations at US$0.89.
- Across the first nine months of 2026, WesBanco’s net income reached US$270.82 million and basic earnings per share from continuing operations was US$2.69, providing a clearer view of year to date profitability.
- Investors can now observe how WesBanco's higher nine month earnings per share may influence the existing investment narrative around expansion and efficiency.
Scan how WesBanco's earnings story compares with other regional lenders by checking a curated list of solid balance sheet and fundamentals (25 results) that echo similar profitability and balance sheet profiles.
WesBanco Investment Narrative Recap
For WesBanco, the core belief as a shareholder is that management can convert its commercial expansion, especially in newer markets like South Florida, into consistent earnings while keeping funding costs and credit quality in check. The latest results, with third quarter net income of US$89.51 million and basic EPS of US$0.89, support that operating story without radically changing it.
The key short term catalyst remains how effectively WesBanco grows that record commercial pipeline into higher quality interest income, while keeping the efficiency ratio around current levels. The biggest watchpoint is still loan growth running ahead of largely flat deposits, since heavier use of wholesale funding could pressure net interest margin if conditions stay the same.
The third quarter and nine month earnings announcement is the clearest reference point for those catalysts right now. Net interest income of US$226.88 million in the quarter and US$664.44 million year to date, alongside basic EPS of US$2.69 for the first nine months, gives you a cleaner read on how the lending and deposit mix is feeding into profitability.
Year to date net income of US$270.82 million, compared with US$132 million in the prior period, also matters for assessing execution on branch consolidation, digital tools and South Florida hiring. If you are tracking WesBanco, this update helps you judge whether higher operating expenses, commercial real estate payoff activity and funding choices are being offset by better pricing, volumes and noninterest income momentum.
WesBanco's current analyst narrative points to forecast 2029 revenue of US$1.3b and projected earnings of US$399.0 million, based on revenue growth assumptions of 6.4% per year and an earnings increase of about US$67.0 million from current earnings of US$332.0 million.
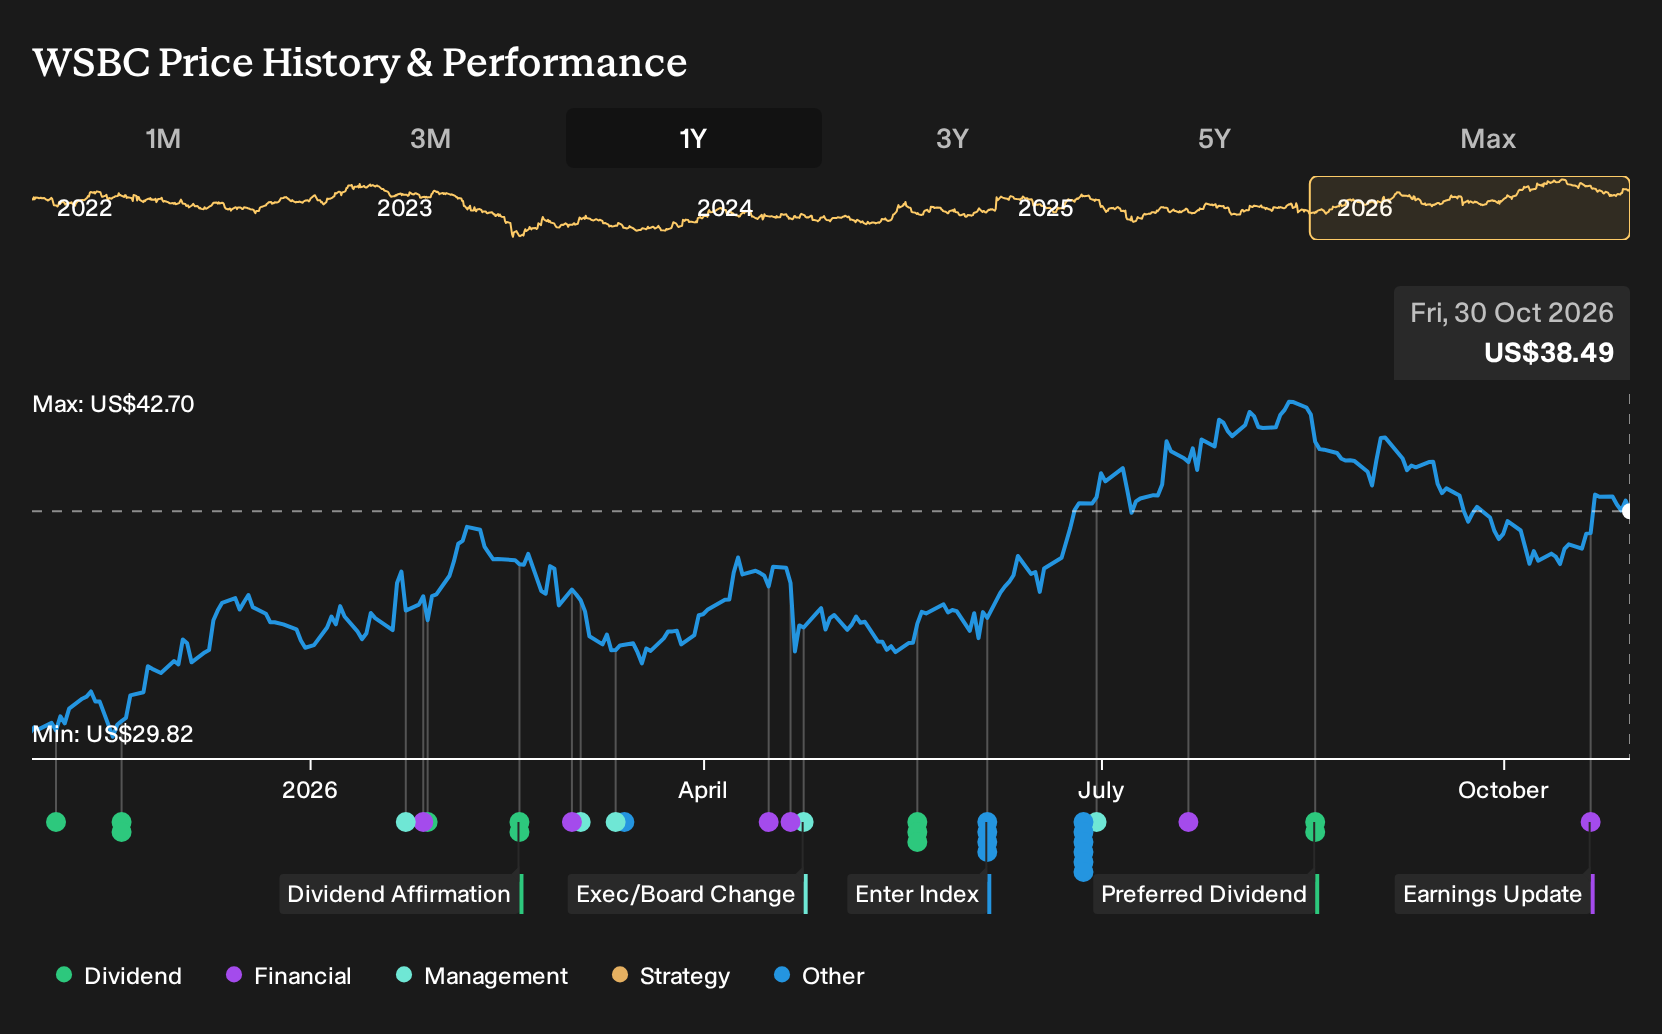
Uncover why WesBanco's fair value indicates a 16% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community bracket WesBanco between about US$44.50 and roughly US$63, with views spread across the full range of buckets. That spread sits alongside risks around wholesale funding costs and commercial real estate paydowns, which shows how sharply opinions can diverge and why exploring multiple community viewpoints matters.
Explore another WesBanco fair value estimate, including one that suggests as much as 64% potential upside from the current price.
Form Your Own Verdict
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your WesBanco research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for WesBanco. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate WesBanco's overall financial health at a glance.
Looking For More Ideas Beyond WesBanco?
If you want to stress test your thesis on WesBanco, it helps to line it up against other businesses with different balance sheet strength, payout profiles and valuation setups.
- For investors who care most about balance sheet resilience and steady fundamentals, scan a curated list of solid balance sheet and fundamentals (25 results) that share similar capital strength and funding discipline.
- If your priority is value for money, weigh WesBanco against a 29 high quality undervalued stocks that screen well on both quality and pricing.
- Income focused readers can compare WesBanco with a 5 dividend fortresses that couple higher yield with an emphasis on stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com