


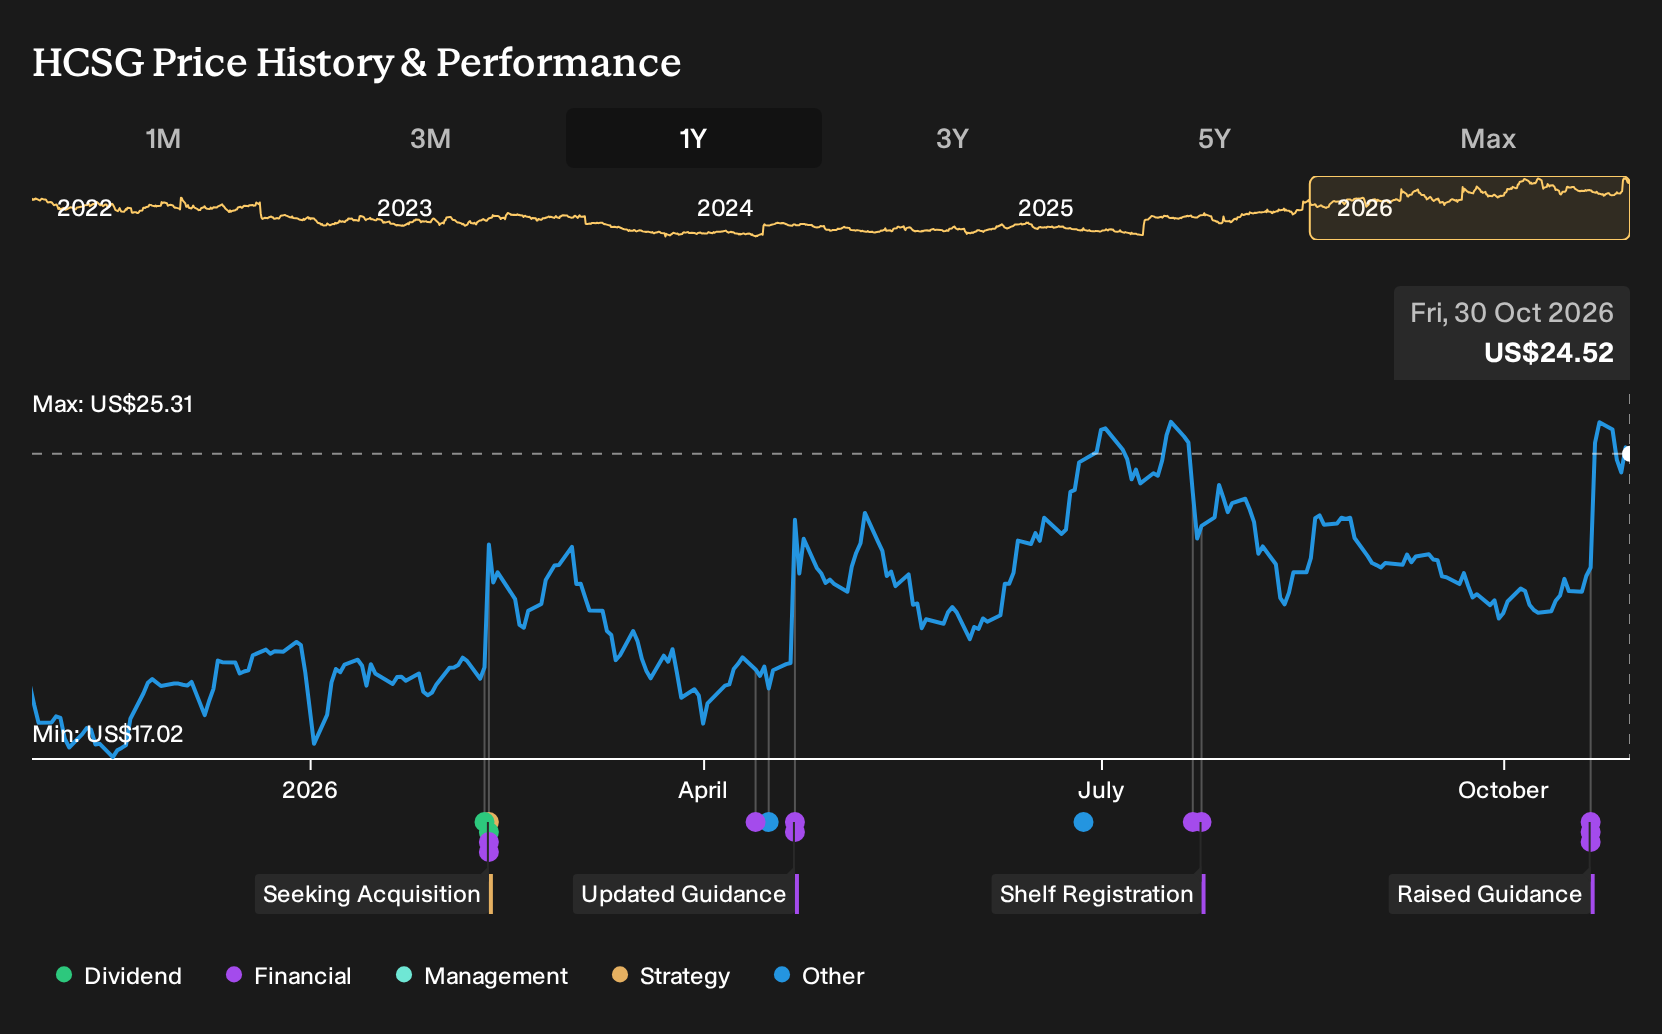
- Healthcare Services Group reported third quarter 2026 sales of US$479.6 million and net income of US$24.88 million, issued fourth quarter revenue guidance of US$535 million to US$545 million, and provided updated figures for the first nine months of the year.
- The company combined higher year to date net income with an upgraded 2027 revenue growth outlook to low double digits and ongoing share repurchases totaling 2,267,333 shares for US$47.34 million, which highlights a focus on both operating improvement and capital return.
- We will examine how Healthcare Services Group's higher 2027 revenue growth outlook may reshape the investment narrative that investors have been using.
Compare Healthcare Services Group's guidance shift with other companies sharpening their outlooks by scanning our curated list of 29 high quality undervalued stocks.
Healthcare Services Group Investment Narrative Recap
For Healthcare Services Group, the core belief is that outsourced housekeeping and dietary services remain essential to long-term and post-acute facilities, and that better contracts and collections translate into steadier earnings. The raised 2027 revenue growth outlook to low double digits aligns with that view, while the Q3 net income drop keeps near-term profitability quality in focus.
The key short-term catalyst remains execution against the higher 2027 growth guidance and the fourth quarter revenue range of US$535 million to US$545 million. The biggest risk still lies in client concentration and legal or compliance issues, so this latest update does not materially change the risk profile.
The most relevant update is the higher 2027 revenue growth outlook, raised from mid single digits to low double digits. That sits alongside Q3 sales of US$479.6 million and nine-month sales of US$1,413.18 million, which provides a clearer run rate to compare against the new guidance range.
On catalysts, stronger top-line guidance puts more emphasis on Healthcare Services Group converting contract wins and service day billing into consistent cash generation. The risk is that if outsourcing adoption slows or facility customers come under pressure again, the raised outlook could be difficult to meet and earnings volatility could return.
What The 2029 Analyst Forecasts Assume For Healthcare Services Group
Healthcare Services Group's long term story now has two different growth pictures. Management is talking about low double digit revenue gains into 2027, while the analyst model points to a more modest 5.9% yearly top line increase over the next three years. That split matters because pricing, contract wins and facility volumes all need to line up with whichever trajectory you think is more realistic.
On earnings, the consensus view is more cautious than the 2027 revenue message suggests. Analysts are working off current net income of US$123.0 million and see profit margins compressing from 6.6% today to 3.4% in three years. On those assumptions, forecast earnings of US$74.7 million by 2029 would represent a value decline of about US$48.3 million from earnings today, even as revenue is expected to expand.
The valuation overlay is where the story tightens. To get to the US$27.0 consensus price target, the stock would need to trade on a P/E of 28.3x those 2029 earnings, compared with 11.8x today and above the current 18.4x for the broader US Commercial Services group. Analysts also bake in shrinking share count, with outstanding shares expected to fall 2.59% a year for the next three years as Healthcare Services Group continues buybacks.
Healthcare Services Group's narrative projects forecast revenues of US$2.2b and forecast earnings of US$74.7 million by 2029. This assumes 5.9% yearly revenue growth and an earnings decrease of about US$48.3 million from current earnings of US$123.0 million to the 2029 consensus level.
The gap between the macro story and the model matters for anyone tracking this stock. Analysts still expect long term demand for outsourced housekeeping and dietary services, yet their numbers factor in thinner profitability and lower absolute earnings. That combination implies more weight on volume growth, pass through pricing and working capital discipline to support cash flow, rather than a simple margin recovery story.
Uncover why Healthcare Services Group's fair value indicates a 10% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community cluster between US$27.00 and about US$33.29, which indicates that private investors already span a fairly tight yet meaningful range on Healthcare Services Group. When you weigh that against client concentration, legal exposures and the 2027 guidance upgrade, it becomes clear that opinions can diverge sharply. You may therefore be better served by comparing several community viewpoints before forming your own stance.
Explore another Healthcare Services Group fair value estimate, including one that suggests as much as 36% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Healthcare Services Group research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Healthcare Services Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Healthcare Services Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Healthcare Services Group?
Once you have a handle on Healthcare Services Group, it can help to set it in context by looking at other businesses with different income profiles, balance sheets and risk levels using the Simply Wall St Screener.
- If you want to focus on financial strength first, start with a list of solid balance sheet and fundamentals (25 results) that can handle shocks and still fund growth.
- For investors who care most about resilience, scan a 30 resilient stocks with low risk scores that scores well on volatility, leverage and earnings quality.
- If you prefer to hunt for under-the-radar prospects, check out a 18 high quality undiscovered gems that pair robust fundamentals with limited market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com