


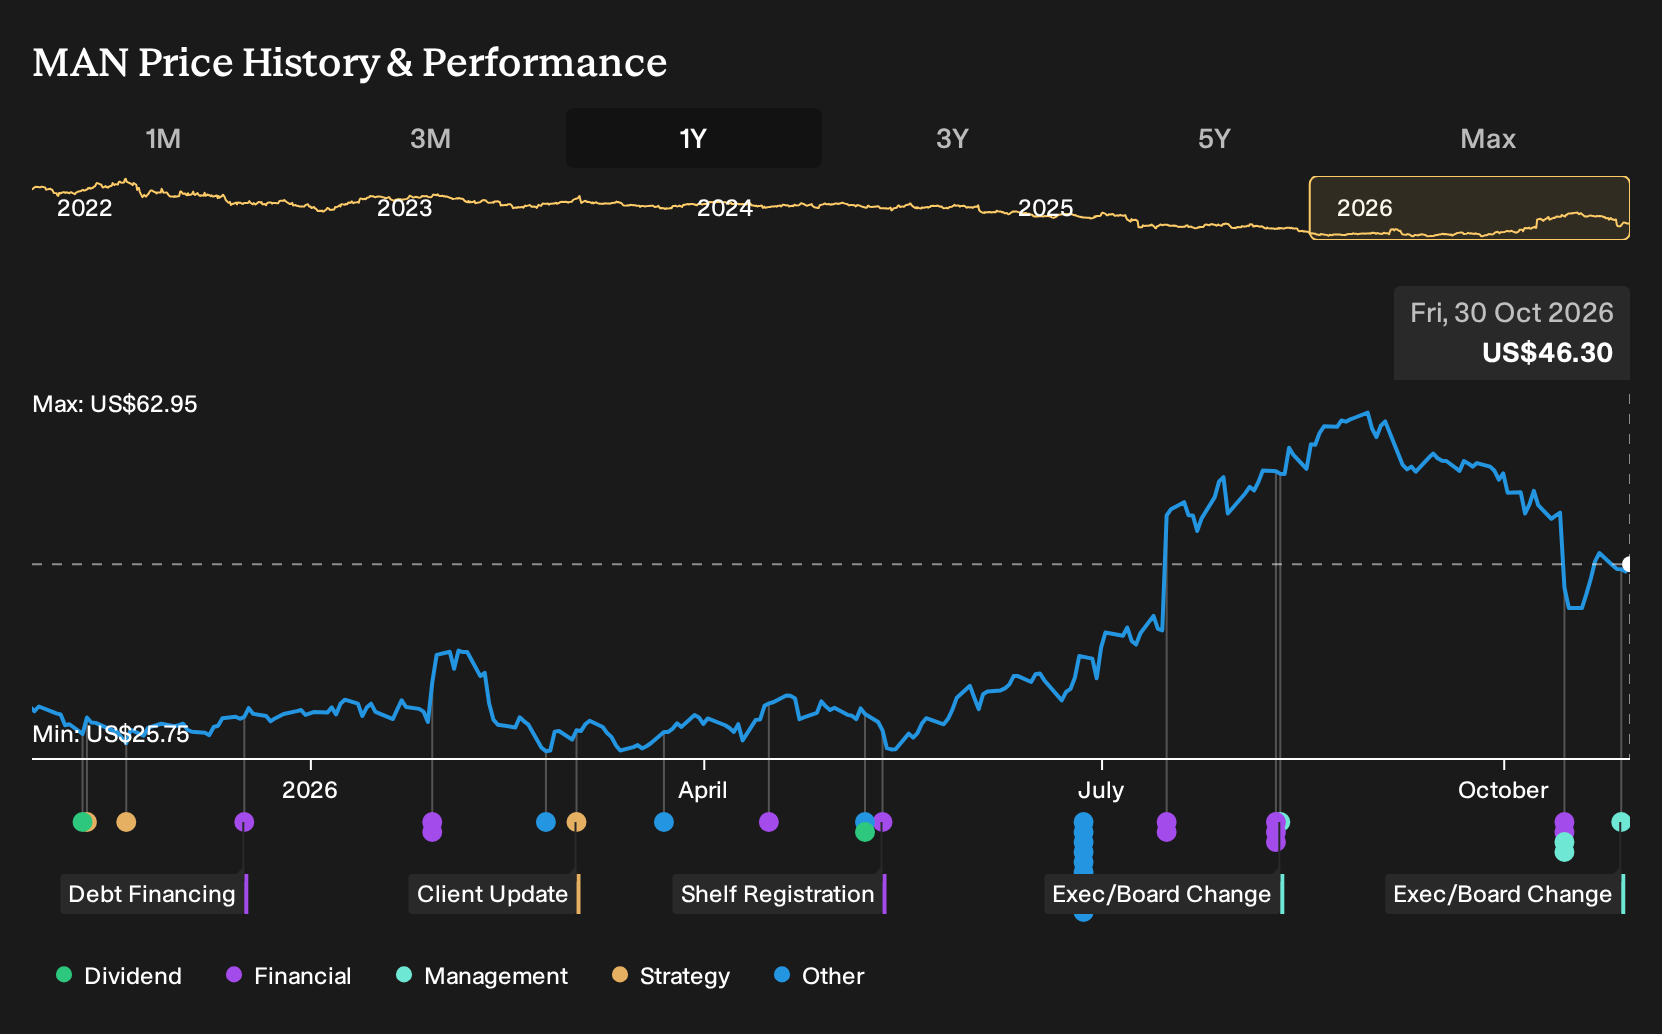
- ManpowerGroup recently elected Lidia Fonseca, former Executive Vice President and Chief Digital and Technology Officer at Pfizer, to its Board of Directors effective November 1, 2026. She brings extensive experience in AI, digital innovation, and large-scale process change across healthcare and diagnostics.
- Her background in building an enterprise AI program from scratch at Pfizer and overseeing business process excellence suggests a focus on operational efficiency, automation, and technology-led workforce solutions that align with ManpowerGroup’s cost and transformation priorities.
- We will examine how ManpowerGroup's investment narrative is influenced by adding an enterprise-scale AI architect to its board.
Scan how ManpowerGroup’s boardroom AI upgrade compares with peers already leaning into automation by reviewing our curated list of 54 AI infrastructure stocks.
ManpowerGroup Investment Narrative Recap
To own ManpowerGroup, you need to believe the transformation story around AI, Experis and Talent Solutions can translate into structurally better margins on a roughly US$18.9b revenue base. The key near term swing factor is execution on the multi year cost program and AI rollout, while keeping staffing mix pressures from further eroding gross profit.
The biggest risk today sits in profitability quality and cash generation. Earnings only recently moved back into positive territory, margins remain modest and free cash flow is sensitive to working capital and transformation spend. Adding Lidia Fonseca to the board does not, on its own, change those near term pressures in a material way.
With no fresh operating announcements alongside Fonseca’s election, the most relevant reference point remains ManpowerGroup’s ongoing AI initiatives such as PowerSuite and Sophie AI. Management previously linked these to an AI powered sales engine and faster recruiting. That context matters because she has hands on experience scaling enterprise AI programs and large process change.
For you as a shareholder, the question is whether this board appointment increases the likelihood that ManpowerGroup executes on its existing catalysts, rather than creating new ones. Better oversight on AI deployment and transformation could help the firm pursue its targeted US$200m of annual cost savings and EBITA margin uplift, while still confronting risks around debt coverage, dividend funding and historically pressured returns on equity.
ManpowerGroup's current earnings of US$120.3 million are set against analyst projections for US$374.9 million of profit and US$21.1b of revenue by 2029. This implies a roughly 3.7% yearly increase in the top line and an earnings move of about US$254.6 million to hit that consensus target.
Uncover how ManpowerGroup's fair value indicates a 13% potential upside to its current price before the market closes the discount gap.
Exploring Other Perspectives
One alternate view centers largely on tax drag. The most pessimistic analysts were already assuming high effective tax rates and still only saw ManpowerGroup reaching about US$20.5b of revenue and roughly US$328.9 million of earnings by 2029. That is far below the bullish US$383.7 million figure. Fonseca’s appointment could nudge these narratives in new directions, so treat this as a prompt to explore both sets of assumptions yourself.
Explore 5 other ManpowerGroup fair value estimates, including one that suggests it could be worth just $45.19.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your ManpowerGroup research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for ManpowerGroup. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ManpowerGroup's overall financial health at a glance.
Looking For More Investment Ideas Beyond ManpowerGroup?
Once you have a view on ManpowerGroup, it can help to stress test that thinking against other opportunities using the Simply Wall St Screener. You can filter by balance sheet strength, income focus or potential mispricing to see how this stock stacks up against the wider market.
- If capital preservation is your priority, compare ManpowerGroup with companies screened for resilience and stability using our 30 resilient stocks with low risk scores.
- For investors hunting for value, set ManpowerGroup alongside candidates that combine quality fundamentals with a possible pricing gap by reviewing the 29 high quality undervalued stocks.
- Income focused portfolios can benchmark ManpowerGroup against reliable high yield payers by scanning the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com