


China Tower (SEHK:788) put profitability in the spotlight with its latest nine month update. Sales reached CNY 71,999 million, while net income came in at CNY 10,817 million, drawing fresh attention from investors.
The recent nine month earnings update arrived after a tough stretch for the shares, with the year to date share price return down 23.33% despite a 0.96% move higher over the last session and a 2.34% gain across the past week. While the 1 year total shareholder return has fallen 15.45%, longer term holders in China Tower are still sitting on a 39.56% total shareholder return over three years. This points to momentum that has cooled rather than a story that has completely reversed.
Scan how China Tower’s profitability story compares with peers by reviewing our hand picked list of list of solid balance sheet and fundamentals (203 results).
China Tower now trades at a steep discount to both analyst targets and some estimates of fair value, even after the recent bounce. Is that gap a simple mispricing, or is the market pricing in real risks around the business model and earnings mix?
Most Popular Narrative: 10% Overvalued
On the latest numbers, the most followed narrative pegs China Tower’s fair value at HK$8.11, which sits below the last close of HK$8.96. As a result, the story leans toward a market pricing that is slightly ahead of those expectations.
Although China Tower is growing Two Wings revenue through Smart Tower and Energy services, the 11.6% fall in EBITDA in 1H26 despite lower depreciation suggests that higher maintenance needs and lease terminations could absorb much of the incremental margin and limit future earnings growth from these newer lines.
See why 1 investors see China Tower as 10% overvalued.
Result: Fair Value of HK$8.11 (OVERVALUED)
Still, if China Tower continues to expand margins, pay a higher dividend and turn towers into edge computing hubs, this cautious fair value story could look conservative.
Find out about the key risks to this China Tower narrative.
Another View On China Tower’s Valuation
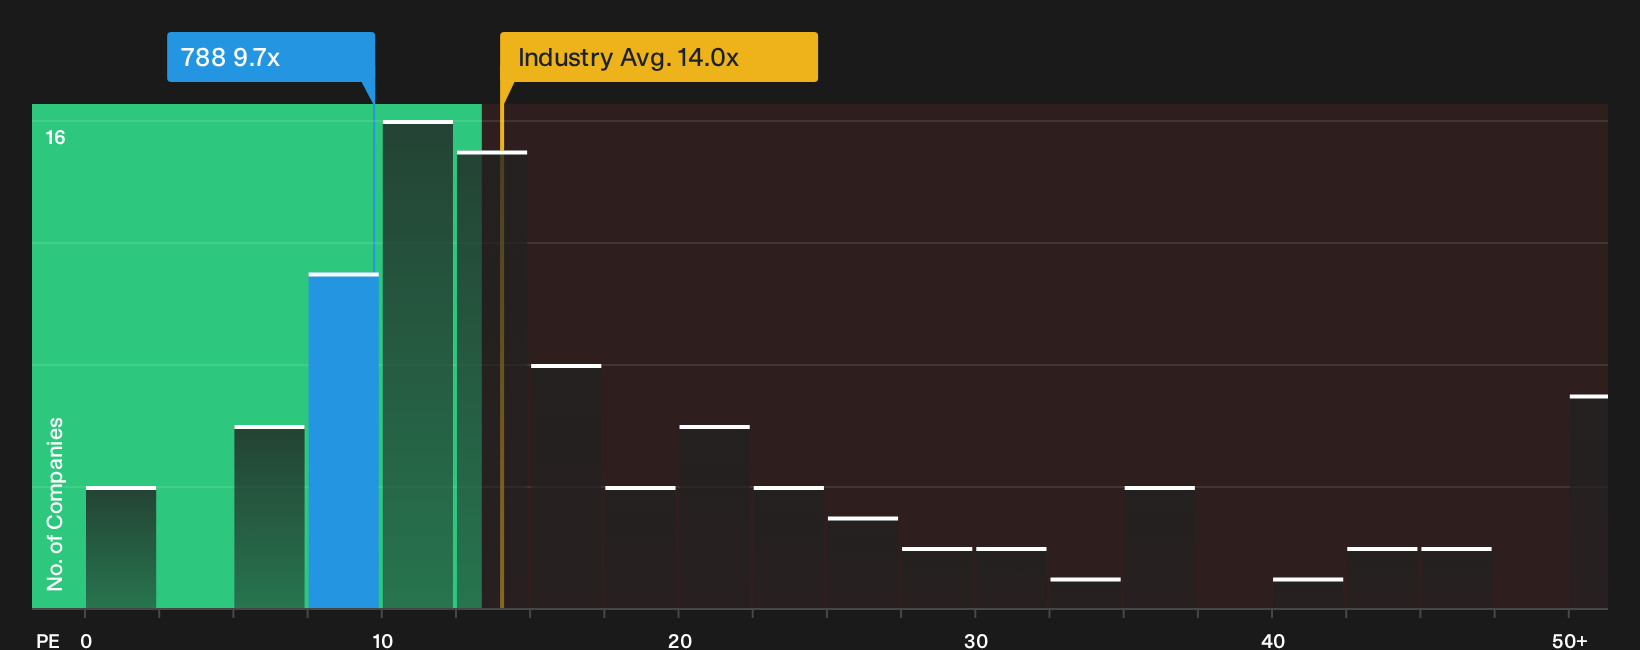
The fair value narrative for China Tower points to an overvaluation at around HK$8.11, yet the current P/E near 9.7x tells a different story. That multiple sits well below the Asian Telecom sector on 13.9x and the fair ratio of 13.2x. This implies the market is pricing in extra risk or discounting the earnings stream more heavily than peers. The question for you is whether that gap reflects real structural issues or an overly cautious mood.
See what the numbers say about this price in our valuation breakdown, then decide which story you find more convincing, the bearish fair value or the cheaper earnings multiple view, by reviewing the See what the numbers say about this price — find out in our valuation breakdown..
For a visual read on how China Tower’s valuation stacks up against its sector on this metric, take a look at the latest
Next Steps
Sentiment on China Tower clearly splits, with some investors focused on potential rewards and others wary of the risks, so move quickly, review the underlying figures, and stress test both sides of the story against the 5 key rewards and 1 important warning sign.
Looking for more investment ideas beyond China Tower?
If China Tower has sharpened your thinking, do not stop there. Broaden your watchlist and pressure test fresh ideas before the market moves ahead of you.
- Target potential mispricing by scanning companies that appear cheap against quality fundamentals through the 199 high quality undervalued stocks.
- Strengthen your income stream by reviewing yield focused opportunities in the 221 dividend fortresses.
- Dial down volatility by concentrating on financially resilient businesses highlighted in the 218 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com