


- NuScale Power announced a manufacturing contract with Doosan Enerbility for upper reactor pressure vessel and coolant system components, moving its NRC approved small modular reactor design from preparation into commercial scale production.
- The shift from material supply to full reactor module manufacturing provides clearer evidence that NuScale’s supply chain partners can build core equipment to specification, which is important for execution risk, delivery timing, and long-term project economics.
- We will examine how NuScale Power's investment narrative changes as this Doosan manufacturing contract clarifies the path to commercialization.
NuScale Power Investment Narrative Recap
To own NuScale Power, you need to believe small modular reactors can move from licensed technology into projects that actually sign contracts, break ground, and enter service. The Doosan manufacturing deal pushes the hardware side forward, but the key short term catalyst still sits with customer agreements like Tennessee Valley Authority and RoPower turning into firm, financed projects.
The biggest risk today is that commercial deployments slip while cash burn and shareholder dilution continue. This contract does not change the need for long term power purchase agreements, additional funding clarity, and NRC progress on the power upgrade. It mainly reduces uncertainty around whether suppliers can build the gear on spec and at scale.
Among the recent developments, the disclosure that NuScale Power holds about US$1.9b in cash against just US$75,000 in quarterly revenue is most relevant when you think about the Doosan move into production. That cash balance gives the business room to keep funding engineering, manufacturing preparation, and project development while it works to convert interest into signed contracts.
The combination of a large cash reserve and live manufacturing activity raises the stakes on execution. Outcomes around a potential TVA agreement, resolution of the RoPower situation in Romania, and timing on ENTRA1 linked opportunities now matter even more because they determine whether those funds turn into long term SMR fleets or prolonged pre revenue spend with ongoing dilution risk.
NuScale Power's narrative projects US$415.5 million revenue and US$46.7 million earnings by 2029. This implies a very large 238.7% yearly revenue growth rate and an earnings swing of about US$462.4 million, from a loss of US$415.7 million today to the forecast profit.
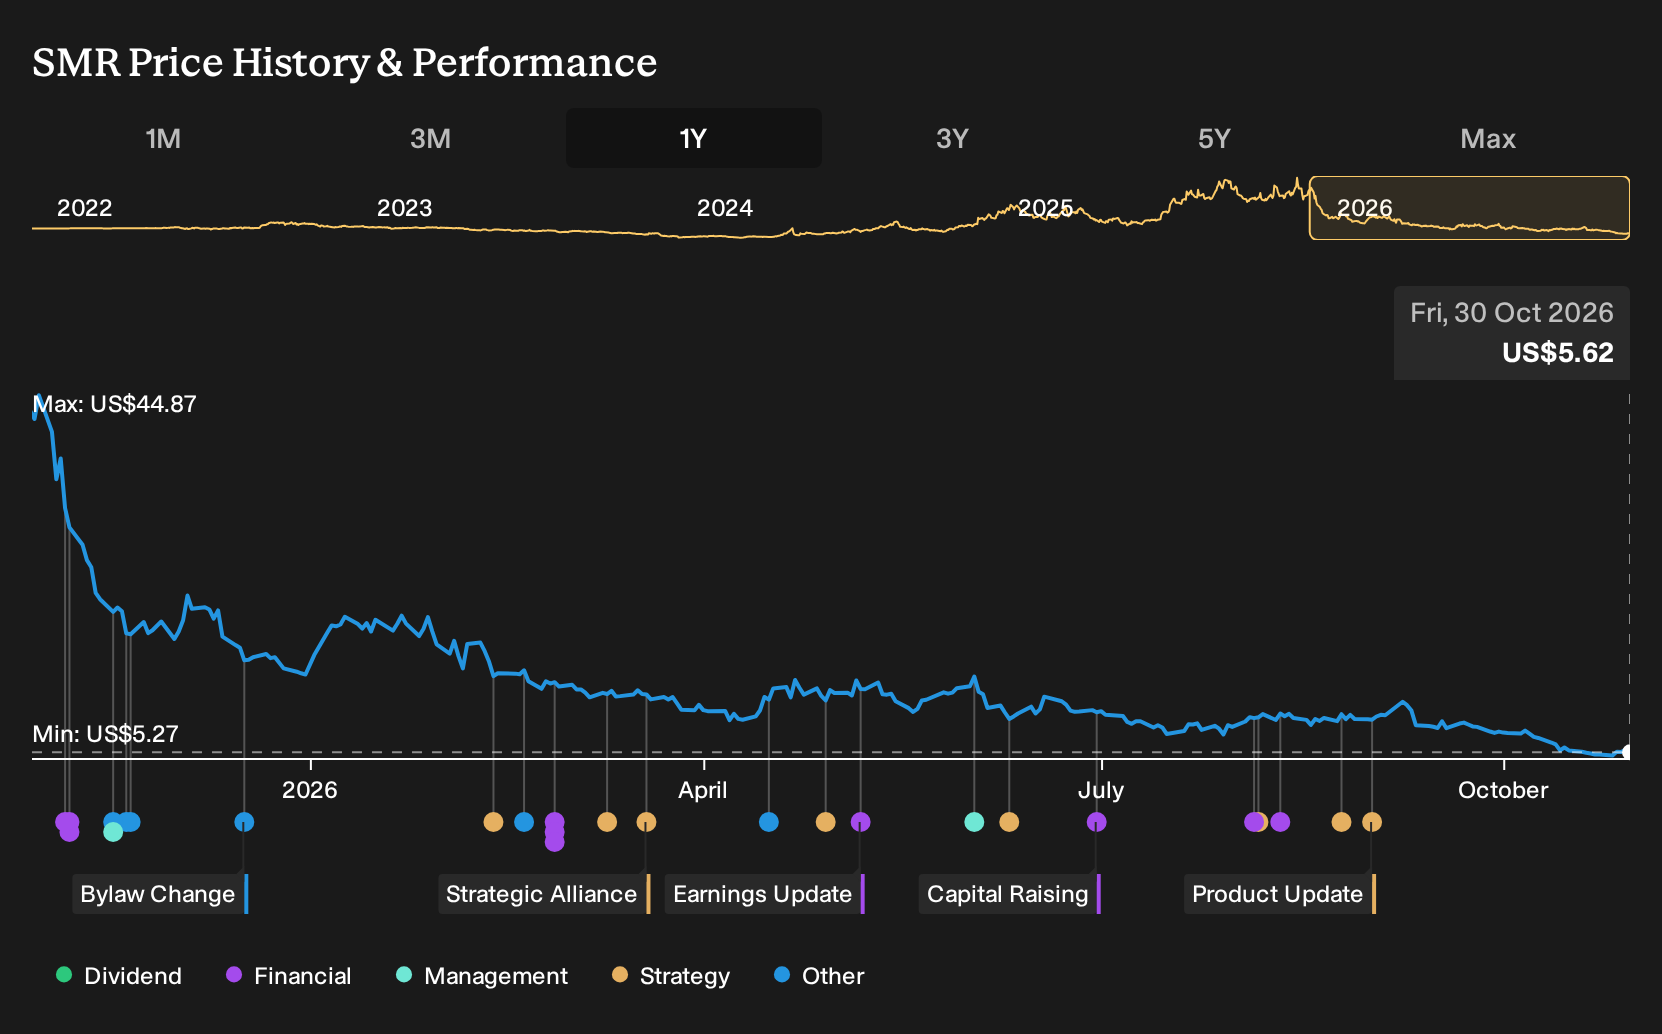
Discover how NuScale Power's fair value indicates a 102% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view on NuScale Power leans hard into execution risk at ENTRA1. The most cautious analysts were only pencilling in about US$158.2 million of revenue and US$17.8 million of earnings by 2029, even before this Doosan contract. That more pessimistic narrative could shift, so treat it as one of several viewpoints to test.
Explore 9 other NuScale Power fair value estimates, including one that suggests as much as 52% downside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own view.
- A great starting point for your NuScale Power research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for NuScale Power. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NuScale Power's overall financial health at a glance.
Looking for more NuScale Power sized ideas?
Once you have a view on NuScale Power, it helps to widen the lens and see how other companies stack up on quality, value, and resilience. The Simply Wall St Screener can surface a range of different profiles so you can compare NuScale Power to peers and potential alternatives in a structured way.
- If capital preservation and steadier profiles matter most to you, start with a set of 30 resilient stocks with low risk scores that score well on resilience and lower overall risk.
- For readers hunting for underappreciated opportunities with solid fundamentals, there is a tailored 18 high quality undiscovered gems that may not yet be widely followed.
- If you want balance sheet strength front and center, filter your universe with a list of solid balance sheet and fundamentals (25 results) to compare funding profiles and financial robustness alongside NuScale Power.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com