


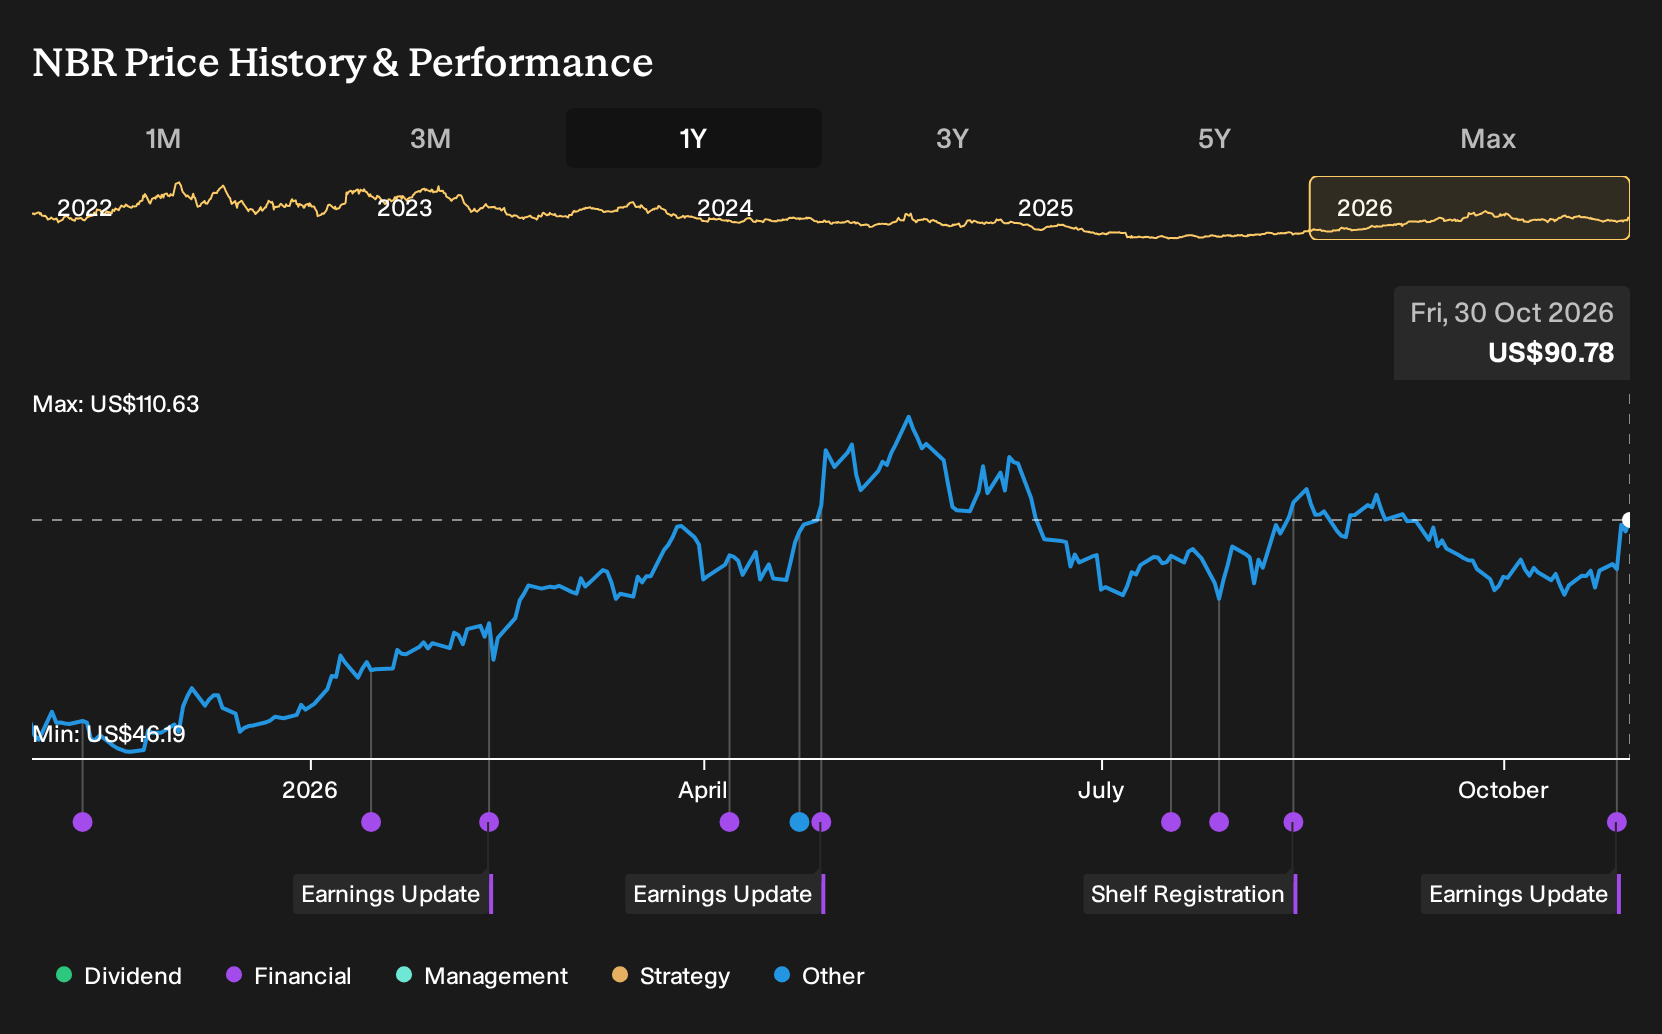
- Nabors Industries reported third quarter 2026 revenue of US$876.34 million and a net loss of US$11.17 million, with nine month revenue of US$2.48 billion and a loss of US$48.66 million, compared with profits in the prior year period.
- Management pointed to stronger than expected revenue, growing Latin America and U.S. Lower 48 activity, and greater use of technology solutions as key operational themes.
- The focus will now be on how Nabors Industries' investment narrative is affected by stronger than expected revenue alongside deeper technology adoption.
Nabors Industries Investment Narrative Recap
For a shareholder in Nabors Industries, the central idea is simple. You need to believe the rig fleet and technology platforms can stay meaningfully utilized across U.S. and international markets while the company works through losses. The latest quarter supports that view on activity, with revenue ahead of expectations and management highlighting healthier rig deployment in Latin America and the U.S. Lower 48.
The near term catalyst is execution on redeploying idle rigs and scaling drilling software and automation, since that is where any margin repair is likely to start. The biggest immediate risk is that contract renewals and softer customers in places like Mexico or Saudi Arabia keep pressuring day rates and utilization, which would make the current loss profile harder to improve.
The fresh reference point here is the third quarter 2026 report that showed US$876.34 million of revenue and a net loss of US$11.17 million, along with a nine month loss of US$48.66 million. For context, the same periods in the prior year were profitable, so you are looking at a business that has swung from earnings to losses while still growing total sales.
That mix matters when you think about catalysts. Management is leaning on geographic diversification, technology adoption and redeploying rigs into markets that are absorbing capacity. If those levers support steadier cash generation, the company is better placed to handle high capital needs and existing debt. If not, the combination of losses, capex demands and operator consolidation could keep risk elevated.
Nabors Industries' current analyst script points to forecast 2029 revenue of US$3.9b and projected earnings of US$353.3 million, based on an assumed 6.3% yearly revenue growth rate. This path implies earnings rising by about US$152 million from US$200.9 million today, with that forecast anchored to 2029 as the estimate year.
Uncover why Nabors Industries' fair value indicates a 20% potential upside to its current price that could close faster than many investors expect.
Exploring Other Perspectives
Some of the most optimistic analysts focus less on rig redeployments and more on Nabors Industries turning its technology and international work into higher quality cash flow. Before this earnings release, that group was assuming revenue could reach about US$4.2b by 2029 with earnings near US$51.5 million. You can treat this as one possible path, then compare it with more cautious views and decide which storyline feels closer to how you see the business after these results.
Explore 3 other Nabors Industries fair value estimates, including one that suggests potential upside of up to 136% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider using your own judgment.
- A great starting point for your Nabors Industries research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Nabors Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nabors Industries' overall financial health at a glance.
Looking for More Investment Ideas Beyond Nabors Industries?
If the Nabors Industries story has sharpened how you think about risk, cash flow and balance sheets, it can be useful to compare that thinking with other potential opportunities. The Simply Wall St Screener lets you quickly filter the market using fundamentals so you can find businesses that match your own criteria instead of relying solely on consensus narratives.
- If capital preservation sits high on your list, you can start with companies that screen well on resilience and stability by reviewing the 30 resilient stocks with low risk scores.
- For investors who care about financial strength before anything else, you can focus on robust balance sheets and solid fundamentals through the list of solid balance sheet and fundamentals (25 results).
- If you are searching for ideas that the broader market may be overlooking, it may be worth scanning a curated pool of quality opportunities in the 18 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com