


- Lindsay Corporation reported full year 2026 results with sales of US$635.86 million and net income of US$55.65 million, alongside a regular quarterly dividend of US$0.38 per share declared for payment on November 30, 2026.
- The gap between softer earnings and continued capital returns through dividends and a completed US$50 million buyback illustrates how Lindsay is balancing current profitability pressures with shareholder cash distribution.
- The focus now turns to how Lindsay's softer full year earnings profile could reshape the existing investment narrative around irrigation, infrastructure and technology.
Scan how Lindsay balances softer earnings with ongoing cash returns, then line it up against a curated 5 dividend fortresses that are also still writing regular checks to shareholders.
Lindsay Investment Narrative Recap
To own Lindsay, you need to be comfortable with a story built on irrigation, road safety projects and a growing tech layer, while accepting that near term conditions are soft. The latest full year numbers show pressure on sales and earnings, so the near term catalyst still hinges on execution in international irrigation and the large MENA project.
The biggest risk has not changed. Weak North American farm economics and lumpy Road Zipper style work can keep volumes and margins choppy, just as Project Fortify adds depreciation. The fresh results and updates influence timing more than thesis, since they do not yet show a clear turn in demand.
The dividend declaration of US$0.38 per share for November 30, 2026 is the most directly relevant update. It tells you Lindsay is keeping its regular cash return in place even as earnings from continuing operations step down year on year and net income sits at US$55.65 million on US$635.86 million of sales.
For you as a shareholder, that steady payout slots into the existing catalyst map. Management is committing to regular dividends while working through softer North American irrigation demand, project mix volatility in infrastructure and heavy spending on Project Fortify ahead of the new galvanizing facility and planned 2027 cost savings.
Lindsay Consensus Assumptions In Focus
Lindsay's current setup pairs softer reported earnings with a forward story that leans heavily on analyst expectations. Those projections frame how much patience the market is effectively willing to extend while irrigation and infrastructure projects work through a slower patch.
According to the latest stock analysis report, analysts are building their models on Lindsay growing revenue by 3.8% each year over the next three years. They are also assuming that profit margins rise from 8.8% today to 10.7% over that same window, helped by project execution, a richer technology mix and the payoff from Project Fortify spending.
On earnings, the consensus view points to profit of US$74.9 million by about 2029, compared with US$55.2 million today. That implies an earnings increase of roughly US$19.7 million from current levels, which is a useful sense check against Lindsay's latest full year net income and the capital being put to work in Nebraska and international irrigation.
Lindsay's narrative projects US$702.0 million revenue and US$74.9 million earnings by 2029. This requires 3.8% yearly revenue growth and an earnings increase of about US$19.7 million from current earnings of US$55.2 million.
Those same forecasts sit behind the consensus price target. For the analyst target of US$123.0 per share to add up, the models assume Lindsay reaches US$702.0 million of sales and US$74.9 million of earnings in 2029 and trades on a P/E of 17.9x at that point. That multiple would be lower than both Lindsay's current P/E of 20.9x and the present 24.3x P/E reference for the wider US machinery peer group.
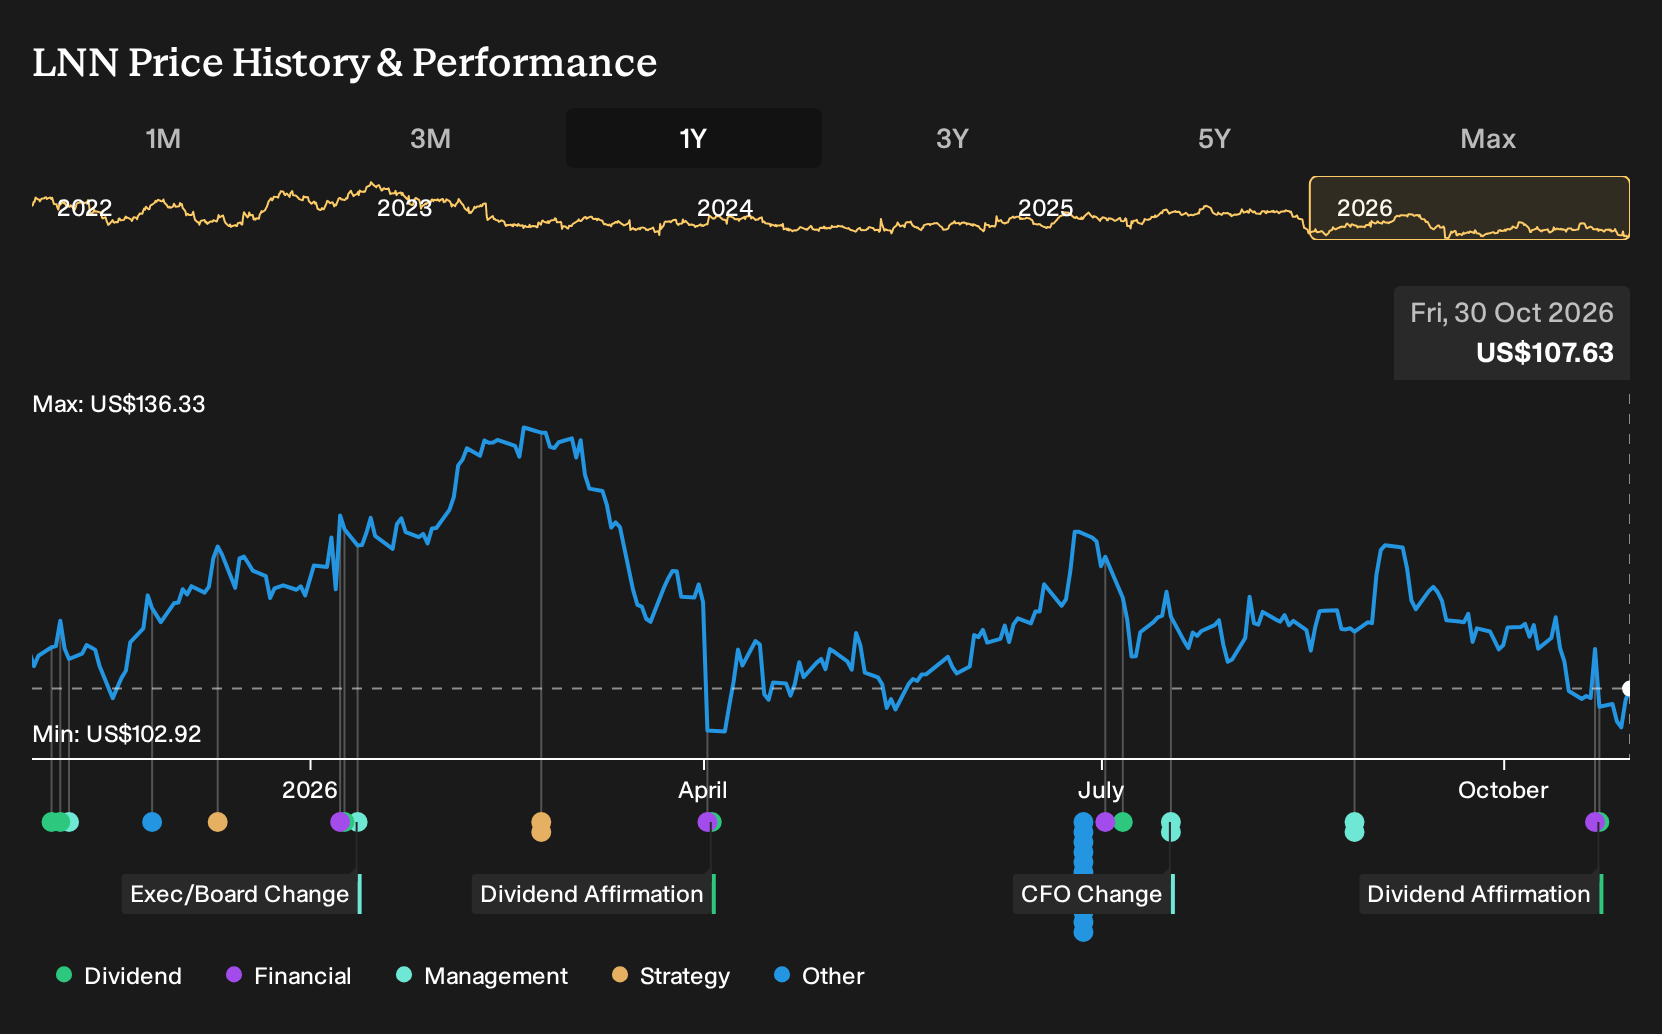
At a share price of US$113.33, the US$123.0 target is only 7.9% higher. This suggests the average analyst view sits close to "fairly priced" on these inputs. For you as an investor, the signal is not about a big upside gap. It is that the current quote already bakes in modest revenue growth, higher margins and a gradual earnings lift while Lindsay keeps returning cash through its dividend and buyback execution.
Uncover why Lindsay's fair value indicates a 14% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
The Simply Wall St Community adds two fair value views for Lindsay, clustering between US$123 and about US$138 per share, with one estimate at the low end and another pushing toward the upper bucket. You are also weighing softer recent earnings, continued dividends and a completed US$50 million buyback. That mix underlines how sharply opinions can diverge. Explore several of these community viewpoints before deciding how Lindsay fits into your own risk and return expectations.
Explore another Lindsay fair value estimate, including one that suggests there may be as much as 28% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Lindsay research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Lindsay. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lindsay's overall financial health at a glance.
Looking For More Investment Ideas Beyond Lindsay?
Once you have a view on Lindsay, it often helps to compare it with a wider bench of companies that match the kind of risk, income and quality profile you are aiming for. The Simply Wall St Screener can surface a targeted set of stocks that line up with what you care about most, whether that is resilience, income or undiscovered potential.
- If capital preservation comes first for you, start with companies that pair healthier balance sheets with steadier fundamentals through the list of solid balance sheet and fundamentals (25 results).
- If you would rather focus on mispriced quality, filter for businesses that combine stronger fundamentals with more modest valuations using the 29 high quality undervalued stocks.
- If hunting for under the radar potential suits your style, cast a wider net across candidates with stronger financial profiles that the market may be overlooking through the 18 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com