


- KLA Corporation reported first quarter fiscal 2027 results for the period ended September 30, 2026, with revenue of US$4.14b and GAAP diluted EPS of US$1.18, both ahead of analyst expectations.
- The business tied its record quarterly performance to heavy AI infrastructure and advanced packaging demand, reinforcing how rising process control intensity is feeding into KLA’s backlog, margins, and near term guidance.
- We now examine how KLA's record September quarter and AI driven demand could influence the existing investment narrative.
KLA Investment Narrative Recap
To own KLA stock, you need to believe AI driven chip complexity will keep pulling more process control tools into every fab, and that this long cycle will keep KLA’s US$12.5b backlog converting into systems, services, and cash. The latest quarter, with US$4.14b in revenue and US$1.18 in GAAP diluted EPS, supports that operating thesis rather than changing it.
The key short term catalyst is how efficiently KLA turns that backlog and elevated inspection intensity into sustained high margins despite supply tightness. The biggest near term risk still sits in tariffs, higher DRAM costs, and any renewed pressure on China spending that could squeeze gross margin and delay orders.
The most relevant fresh datapoint for that story is KLA’s guidance for the December quarter. Management is calling for revenue around US$4.7b, give or take US$200m, GAAP gross margin near 61.8% plus or minus 1%, and GAAP diluted EPS in a band of US$1.41, plus or minus US$0.11.
This outlook ties directly to the AI and advanced packaging catalyst investors are focused on. It shows how KLA expects current demand for wafer inspection and metrology to flow through the income statement while still absorbing tariff and DRAM headwinds, which gives you a clearer test case for execution, pricing power, and any early signs of order pushouts.
What KLA’s Long Range Forecasts Assume
KLA’s long range story in the analyst models leans heavily on high AI capex, but the numbers behind that view matter more than the buzzwords. Consensus assumptions tie the process control cycle to a compound revenue expansion of 21.3% per year over the next three years. Profitability in those forecasts rises from a margin of 36.2% today to 41.8% in three years, which implies the business would keep turning a larger share of every extra dollar of sales into profit even while tariffs and component costs remain a drag.
On the earnings line, the analyst set points in the Simply Wall St data show current profit of US$5.3b and a central forecast of US$10.8b by about 2029. That move represents a little more than a 2x increase in earnings over the modeled period. The same framework assumes KLA keeps shrinking its share count by around 0.65% a year for the next three years. As a result, any future profit would be spread over fewer shares, which magnifies per share outcomes if the operating targets are met.
The valuation bridge in those reports treats that forecast as a reference case rather than a guarantee. To line up with the consensus price target of US$225.08, analysts are effectively asking you to accept a 2029 revenue marker of US$25.9b and earnings of US$10.8b, with the stock trading on a P/E of 36.7x at that point compared with 41.6x today. That multiple would also sit below the current 45.2x P/E cited for the broader US semiconductor peer group. This framing suggests the debate is less about whether KLA can generate profits and more about how rich a valuation that cash flow should command several years out.
KLA's narrative projects US$25.9b revenue and US$10.8b earnings by 2029. This setup assumes revenue grows at 21.3% per year and earnings a bit more than double from US$5.3b today.
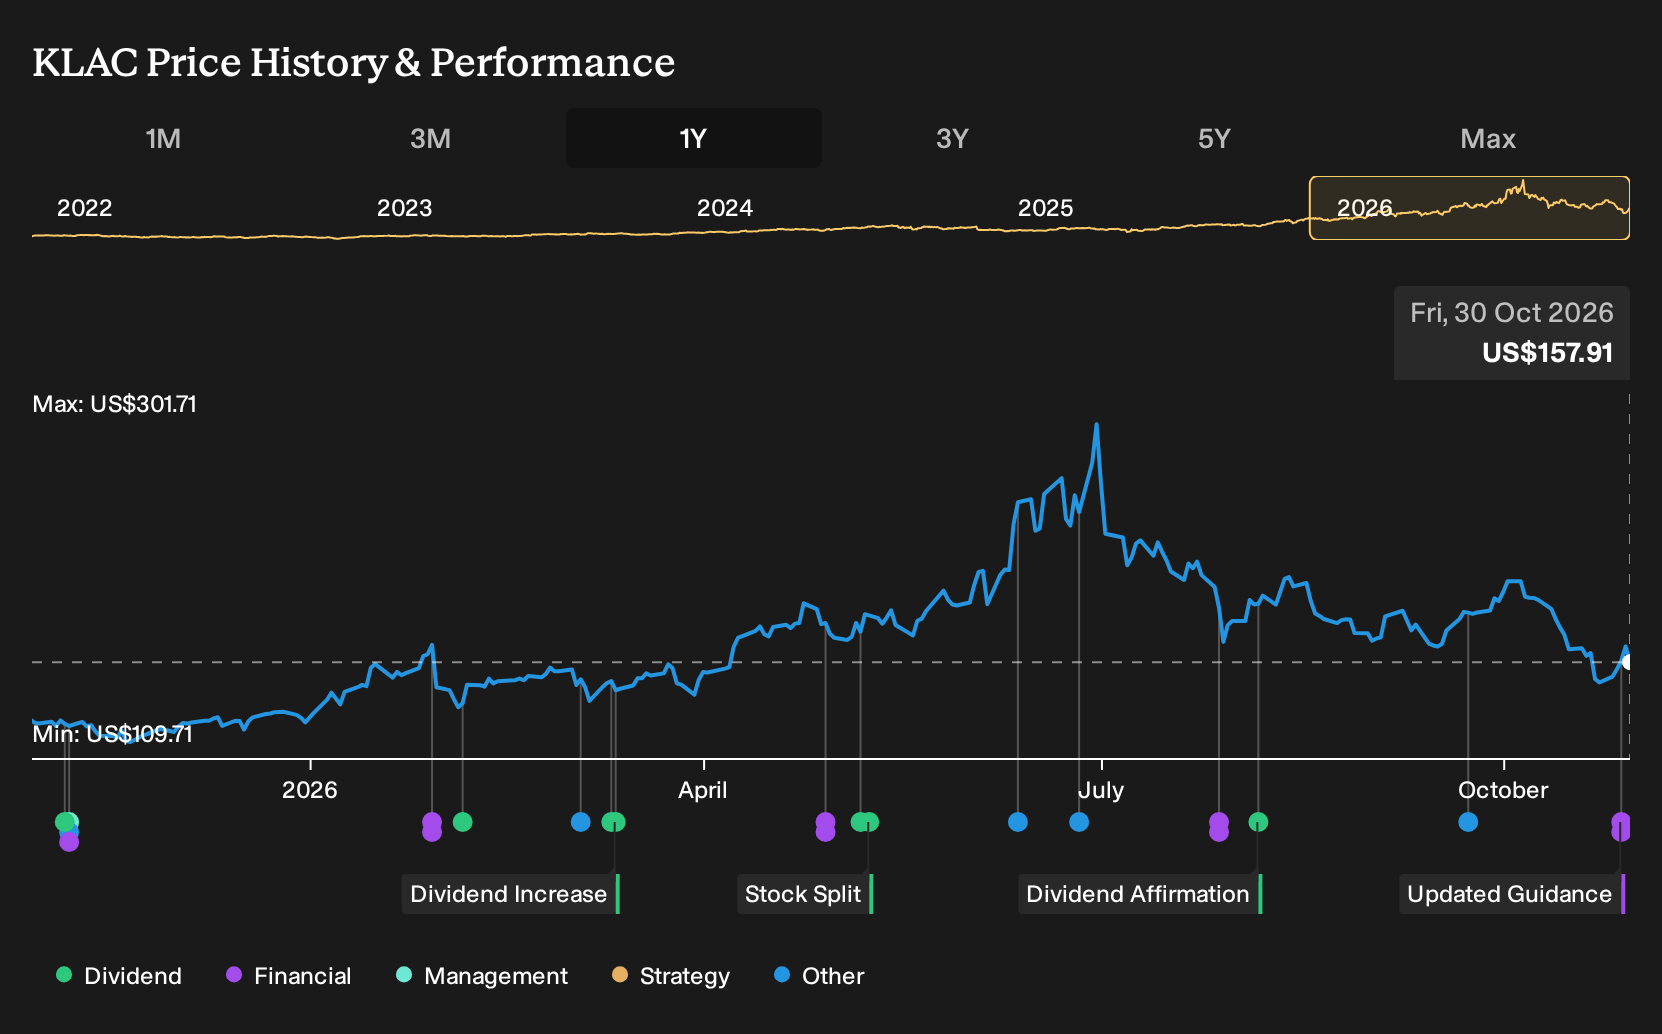
Uncover why KLA's fair value indicates a 43% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
You see one clear tension around KLA. The baseline view leans on AI demand, while the most bearish analysts fixate on stubborn cost pressure. Those cautious forecasts were built before this earnings beat and assumed revenue at about US$23.5b and earnings of roughly US$9.4b by 2029, which leaves plenty of room for opinions and future revisions to differ sharply.
Explore 5 other KLA fair value estimates, including one that suggests as much as 40% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your KLA research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for KLA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate KLA's overall financial health at a glance.
Looking for more investment ideas beyond KLA?
If the KLA story has sharpened your view on AI hardware and semiconductors, it can help to widen the lens and compare it with other opportunities that fit different risk, income, or balance sheet profiles using the Simply Wall St Screener.
- If you want stability first and upside second, start with financially resilient businesses through a 30 resilient stocks with low risk scores that may better match a cautious temperament.
- Income focused investors can hunt for high yield opportunities by scanning a curated set of 5 dividend fortresses that combine payout with size.
- For those hunting earlier stage potential, cast a wider net across a 9 elite penny stocks with strong financials that filters for stronger financials instead of pure speculation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com