


DRDGOLD (DRD) has given investors fresh data to consider, pairing new production guidance for the year to 30 June 2027 with quarterly figures on revenue, gold output, and yield.
DRDGOLD’s fresh guidance and quarterly figures landed against a weaker recent tape, with the share price down 6.8% on the day and 25.4% year to date. Even so, the 3 year total shareholder return sits around 167% and the 5 year figure is close to 185%, which suggests long term holders have still seen strong value creation despite the recent loss of momentum.
Compare DRDGOLD’s latest move with a curated pool of peers by scanning the 34 elite gold producer stocks for other producers reacting to similar production and pricing conditions.
After a sharp pullback on the latest guidance, the question for DRDGOLD now shifts. Is most of the easy upside already in the rear-view mirror, or does the current valuation still leave meaningful headroom ahead?
Preferred P/E of 7.7x: Is it justified?
DRDGOLD now trades at a P/E of 7.7x, and that sits well below both the broader US market and the US Metals and Mining group. This points to a market that is pricing its earnings at a discount to peers rather than paying up for recent performance.
The P/E ratio compares what investors pay for each dollar of profit to what they pay for other businesses. It therefore acts as a quick yardstick for how the market rates a miner's current earnings power. For a producer like DRDGOLD that focuses on retreating surface tailings, this metric anchors directly to underlying profitability rather than just top-line revenue swings that can be heavily influenced by commodity prices.
Relative to the US market P/E of 18.2x, the stock trades at less than half the multiple. This suggests investors are cautious about sustaining current earnings even with a reported return on equity of 33.4% and net profit margins of 38.1%. Versus the US Metals and Mining industry average of 17.2x, the discount is similarly large, implying the market is assigning DRDGOLD a lower valuation than peers even though its earnings growth over the past year and over the past 5 years has been positive and its profitability metrics have moved higher according to the supplied data.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 7.7x (UNDERVALUED)
Still, DRDGOLD’s story can quickly change if operational issues at its Ergo or FWGR segments emerge, or if local South African costs rise faster than expected.
Find out about the key risks to this DRDGOLD narrative.
Another View: SWS DCF model points the other way
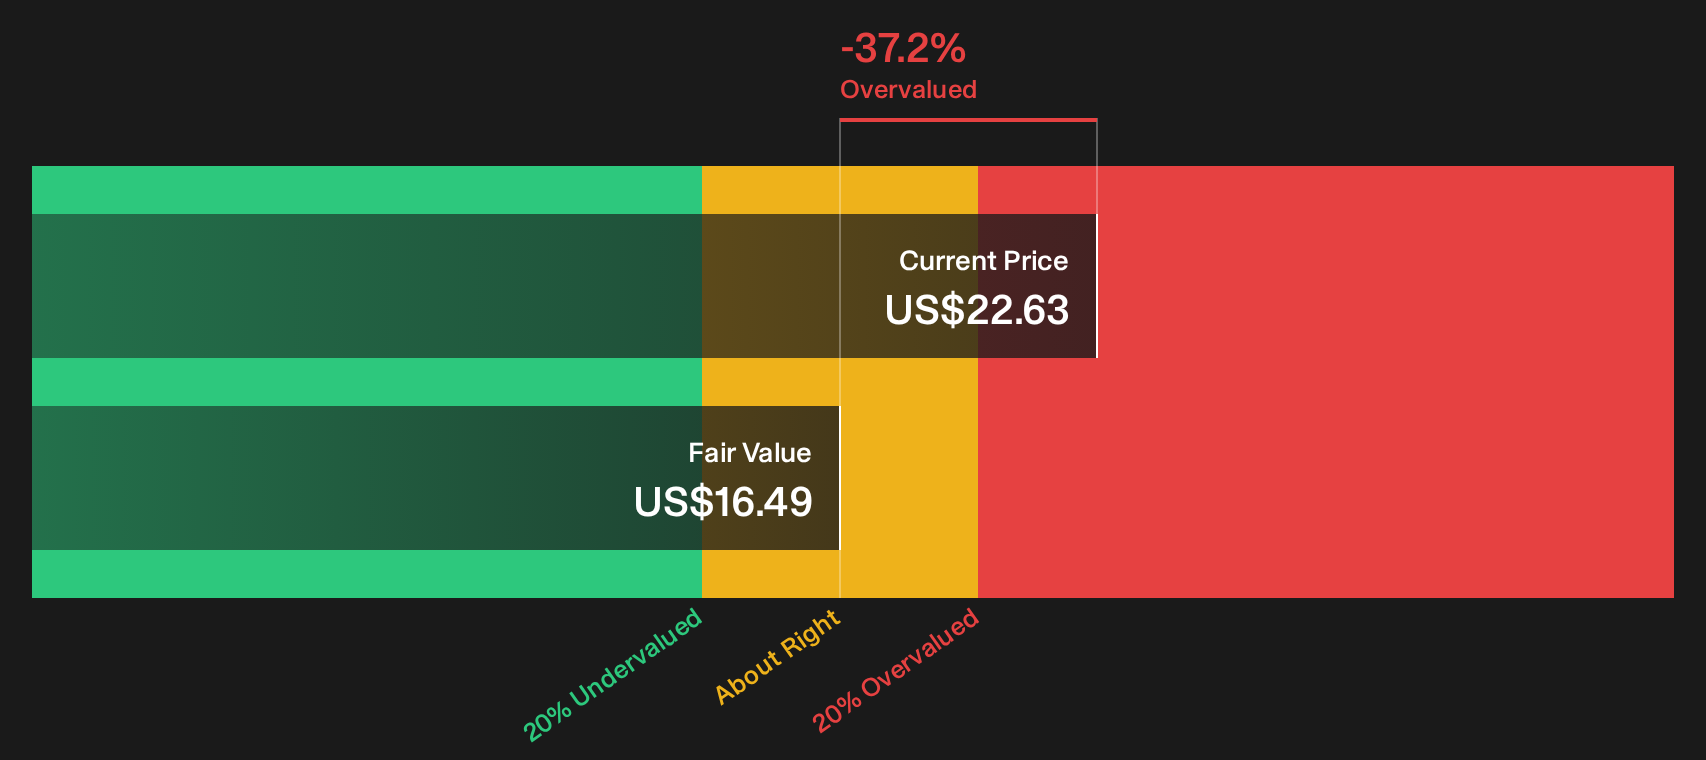
The low 7.7x P/E hints at DRDGOLD being inexpensive, yet the SWS DCF model tells a different story. On that cash flow view, an estimated value of $16.49 sits well below the recent $22.63 share price. This implies the stock screens as overvalued rather than cheap.
That kind of gap can cut both ways for you as an investor. It can mean the market is rewarding DRDGOLD for quality and returns that a strict cash flow model does not fully capture. It can also flag less protection if sentiment cools and the share price drifts back toward the model value.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out DRDGOLD for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around DRDGOLD can feel confusing, especially when valuation and cash flow stories point in different directions. Treat that tension as your cue to review the underlying numbers quickly, weigh both the cautious and optimistic angles, and then ground your own stance in the 2 key rewards and 2 important warning signs.
Looking for more DRDGOLD style investment ideas?
If DRDGOLD has you rethinking your watchlist, do not stop here. The next move often comes from a stock you have not checked yet.
- Target value first by scanning the 29 high quality undervalued stocks to find stocks that pair solid fundamentals with prices the market has not fully rewarded yet.
- Prioritise resilience by reviewing the list of solid balance sheet and fundamentals (25 results) to see companies with stronger finances backing their operations.
- Hunt for tomorrow's outliers through the 18 high quality undiscovered gems to identify quality businesses still flying under most investors' radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com