


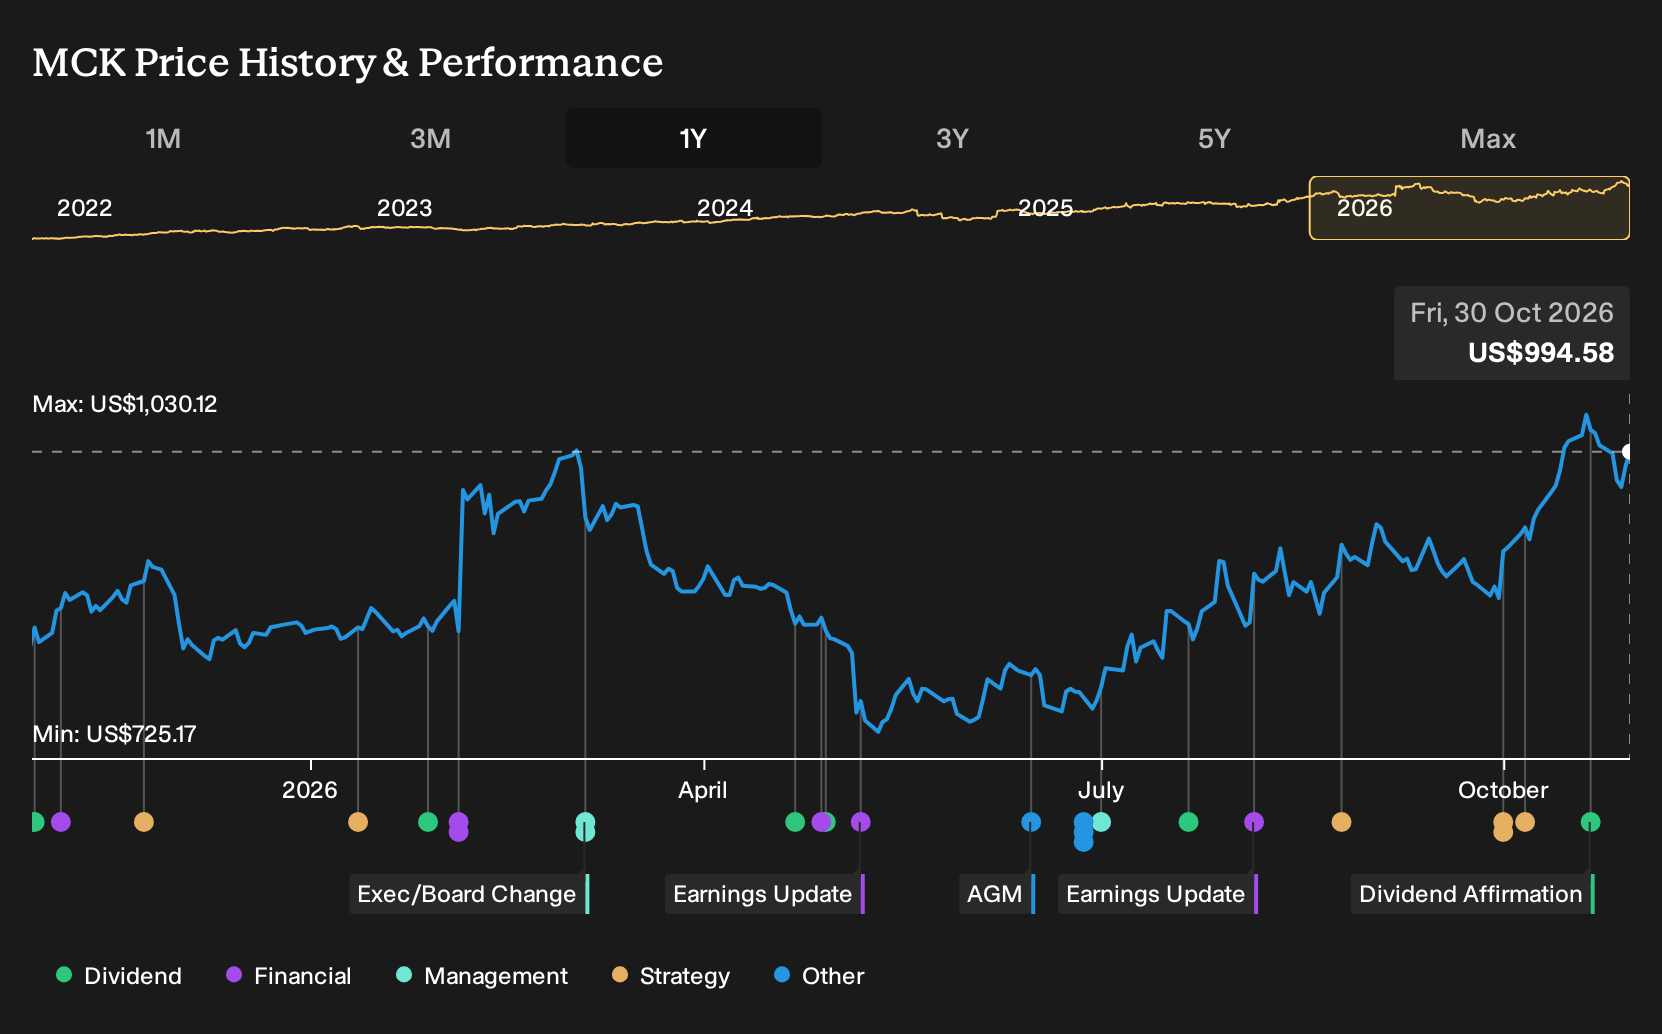
- McKesson's board has affirmed a regular dividend of US$0.94 per share, payable on January 4, 2027, to shareholders of record on December 1, 2026. This signals ongoing cash returns from its healthcare distribution and services operations.
- The combination of a maintained dividend and expectations for higher Q2 FY2027 earnings and revenue highlights how McKesson allocates cash generation between oncology and technology investments and direct payouts to investors.
- We will now look at how McKesson's affirmed dividend and expected earnings performance could shape the broader investment narrative.
Scan how McKesson's dividend and earnings story compares with other cash generative healthcare players by reviewing the list of solid balance sheet and fundamentals (25 results) in one pass.
McKesson Investment Narrative Recap
To own McKesson, you need to be comfortable with a healthcare distributor that leans into oncology services and prescription technology for its long term engine, while still running a massive, low margin core distribution machine. The affirmed US$0.94 dividend signals that, in the near term, management sees no disruption to cash generation from those operations.
The key near term swing factor sits in the upcoming Q2 FY2027 results, where investors will watch whether Oncology & Multispecialty and Prescription Technology Solutions continue to support earnings, alongside Medical-Surgical. The bigger risk is pressure on drug pricing and healthcare costs, plus any lingering cyber incident fallout. The dividend decision does not materially change those risks.
The regular dividend affirmation is the clearest recent announcement to tie directly into McKesson’s catalysts. It sits alongside plans for oncology growth, technology enabled access programs such as RxTS and CoverMyMeds, and the pending Precision Medicine Group acquisition. Together, those elements show how the group balances reinvestment needs with ongoing cash distributions.
For a shareholder, the key question is whether that US$0.94 payout still looks sustainable if regulatory pressure on drug pricing intensifies or GLP 1 related volumes through RxTS soften. The dividend, viewed alongside planned capital deployment and the company’s earnings profile, functions as an ongoing test of execution discipline rather than a directional signal on its own.
McKesson's narrative projects US$500.5b revenue and US$6.4b earnings by 2029. This is based on an assumed 6.8% yearly revenue growth and a US$1.8b increase in earnings from US$4.6b today.
Uncover why McKesson's fair value indicates a valuation gap that aligns with its current price.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community span roughly US$1,001 to US$1,678 per share, so you are looking at a very wide band. That spread sits alongside upcoming earnings, regulatory scrutiny on drug pricing, and cyber incident fallout, all of which could push opinions on McKesson even further apart. Explore several of these viewpoints before deciding how McKesson fits your portfolio.
Explore 2 other McKesson fair value estimates, including one that suggests up to 69% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your McKesson research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for McKesson. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate McKesson's overall financial health at a glance.
Looking For More Ideas Beyond McKesson?
If you want to put McKesson in context, compare it with other companies that match the type of portfolio you are trying to build. The Simply Wall St Screener lets you filter for quality, balance sheet strength, income potential, or undervaluation so you can line up McKesson against a broader watchlist that fits your own rules.
- For investors focused on quality at a reasonable price, review a curated set of companies through the 29 high quality undervalued stocks and see which ones deserve a closer look.
- If resilience matters most to you, start with a 30 resilient stocks with low risk scores and compare those steadier profiles with what McKesson brings to your portfolio.
- For anyone hunting for opportunities that the market may be overlooking, scan the 18 high quality undiscovered gems and build a shortlist to research next.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com