


Universal Technical Institute (UTI) is back in focus after appointing Joseph Dalto as Campus President for its upcoming Concorde Atlanta healthcare campus, a new Georgia facility slated to open in Summer 2027.
For investors, the leadership news arrives at a time when Universal Technical Institute’s shares have been volatile, with the 1-month share price return up 21.26%, the 90-day share price return down 42.41%, and the 1-year total shareholder return declining 23.82%, while the 3-year total shareholder return is up around 1.5x and the 5-year total shareholder return is a bit more than 2x. This suggests that longer-term holders may still be sitting on sizable gains despite recent pressure.
Compare Universal Technical Institute’s trajectory with other education-focused stocks by scanning our hand picked 18 high quality undiscovered gems that may be flying under most investors’ radar.
Universal Technical Institute operates as a growing education platform with new healthcare campuses planned, yet the share price has moved sharply this year. Is this still a solid business available at a sensible valuation today?
Most Popular Narrative: 42% Undervalued
On the widely followed narrative, Universal Technical Institute’s fair value of $38.83 sits well above the last close at $22.64. This puts the current share price at a steep discount if those long range assumptions hold up.
Ongoing campus expansion and program rollouts under the North Star plan, including recently opened sites in San Antonio and Atlanta that are tracking well ahead of internal start expectations and more than 20 new programs in fiscal 2026 across HVACR, aviation, electrical and multiple healthcare disciplines, create a larger physical and curricular footprint that can lift consolidated revenue and eventually margins as new locations approach mature student counts.
See why 2 investors see Universal Technical Institute as 42% undervalued.
Result: Fair Value of $38.83 (UNDERVALUED)
Still, the bullish Universal Technical Institute narrative could crack if high school auto and diesel enrollment conversion keeps lagging or if heavy capex fails to improve campus economics.
Find out about the key risks to this Universal Technical Institute narrative.
Another View: What Multiples Say About Universal Technical Institute
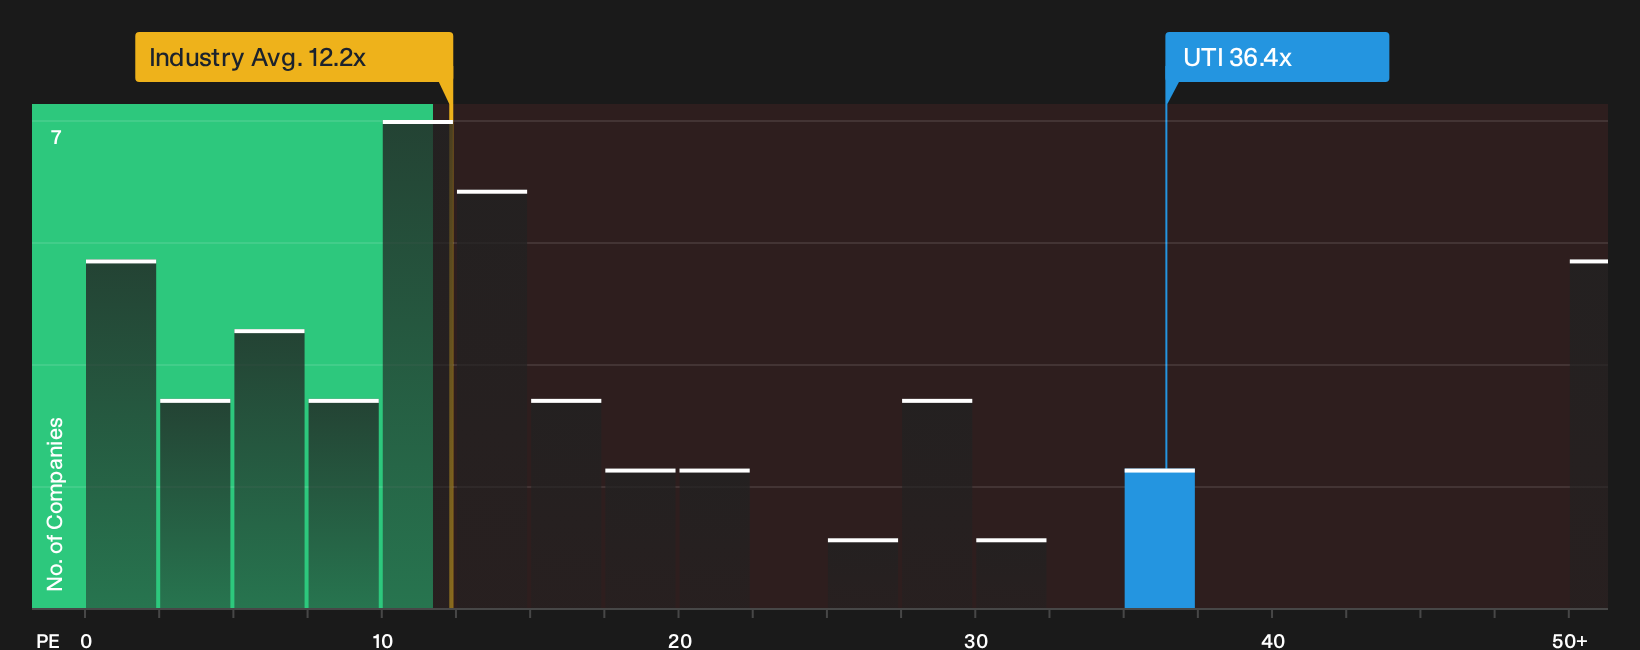
The story looks very different when you swap the detailed fair value model for a simple earnings multiple. Universal Technical Institute trades on a P/E of 36.4x, compared with 12.8x for the wider US Consumer Services group and 9.8x for closer peers, while the fair ratio points to 26.6x. That gap suggests investors are already paying a rich price for the growth case, which raises the question of how much upside is really left if sentiment cools.
To see how that premium lines up against the underlying numbers, and what it might mean for future valuation swings, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Universal Technical Institute can feel confusing, so move quickly, review the full data set yourself, and weigh both 2 key rewards and 3 important warning signs.
Looking for more Universal Technical Institute sized opportunities?
If Universal Technical Institute has sharpened your thinking, do not stop here. Broaden your watchlist quickly with focused stock ideas that fit clear objectives.
- Target potential mispricing by scanning companies our models flag as promising value opportunities through the 29 high quality undervalued stocks.
- Prioritise steadier capital preservation by reviewing a curated 30 resilient stocks with low risk scores built around resilience scores and balance sheet strength.
- Hunt for resilient compounders with strong finances using the list of solid balance sheet and fundamentals (25 results) so you are not late to quality opportunities.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com