


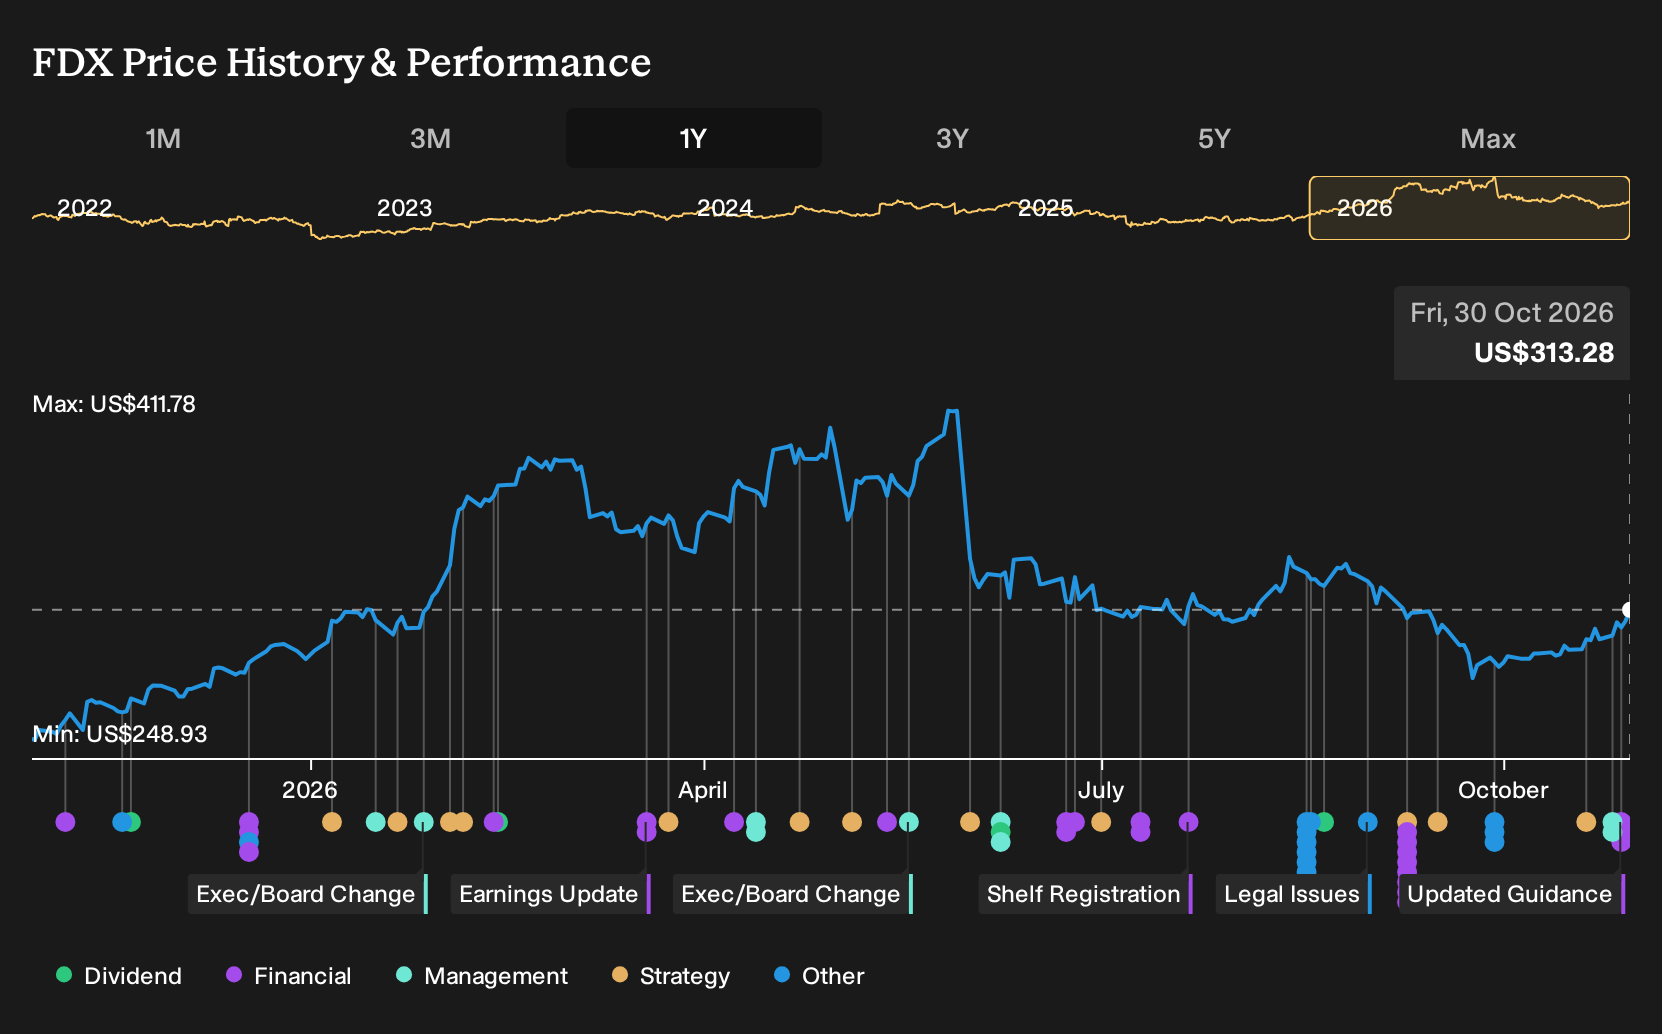
- FedEx reported third quarter 2026 sales of US$22,855 million with net income of US$290 million and raised full year 2026 earnings and revenue guidance, while also guiding to about 10% revenue growth for the fourth quarter.
- The uplifted outlook comes alongside progress on cost saving programs and portfolio simplification, including Network 2.0 actions and the sale of FedEx Supply Chain. Together, these changes reshape how FedEx earns and protects cash flow.
- We will examine how FedEx's raised full year guidance interacts with the prior investment narrative focused on cost transformation and free cash.
FedEx Investment Narrative Recap
For a shareholder in FedEx, the core belief is that Network 2.0, DRIVE and the tilt toward premium B2B and time critical freight can support healthier earnings and strong free cash flow despite a competitive parcel market. The raised full year 2026 revenue and EPS guidance reinforces that cost work and mix shift are showing up in reported numbers rather than just in slides.
The key short term catalyst is execution on cost savings while holding pricing power in premium segments as labor, fuel and outsourced transport costs stay elevated. The biggest risk remains volume or yield pressure if industrial demand softens again or international competition intensifies, and the latest quarter does not remove that concern.
The most relevant announcement for this story is FedEx lifting full year 2026 guidance to about 12% revenue growth and diluted EPS from continuing operations of US$35.30 to US$35.90, alongside an outlook for roughly 10% revenue growth in the fourth quarter. This sits on top of reported third quarter sales of US$22,855 million and net income of US$290 million.
For you, the link to catalysts is clear. Better guidance signals management confidence that Network 2.0 savings, portfolio simplification and growth in higher value verticals can offset cost and margin pressures identified in prior quarters. The risk side is that this bar is now higher. Any disruption from major contracts, weather events or a weaker industrial cycle would be judged against this upgraded outlook.
What The FedEx Consensus Is Really Pricing In
FedEx's narrative projects US$97.7b revenue and US$5.6b earnings by 2029, which analysts tie to a 1.0% yearly revenue growth rate and an uplift in earnings from US$4.4b today to that US$5.6b level.
Uncover how FedEx's fair value indicates a 13% potential upside to its current price before the discount window narrows.
Exploring Other Perspectives
You can see a very different angle when looking at the most bearish analysts. They worry that FedEx will struggle to offset higher fuel and labor costs, which is why they only penciled in about US$95.9b of revenue and US$5.3b of earnings by 2029 before this guidance news. That view is far more cautious than the baseline and highlights how widely expectations can spread. It also invites you to explore both sets of assumptions as fresh numbers and management commentary arrive.
Explore 3 other FedEx fair value estimates, including one that suggests it could be worth just $355.10.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that is truly your own.
- A great starting point for your FedEx research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for FedEx. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate FedEx's overall financial health at a glance.
Looking For More Investment Ideas Beyond FedEx?
If this FedEx story has sharpened how you think about earnings power and balance sheet strength, use that same framework to scan wider opportunities with the Simply Wall St Screener.
- For investors who want quality on sale, short list candidates with a 29 high quality undervalued stocks that combine solid fundamentals with more modest expectations baked into the price.
- If capital protection matters more to you than chasing every rally, focus on businesses that pass tighter risk filters with a 30 resilient stocks with low risk scores that flags more resilient profiles.
- When you care about financial footing first, filter for companies with cleaner leverage and liquidity metrics through a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com