


- CoStar Group reported Q3 2026 sales of US$952 million and net income of US$74 million, updated full year 2026 revenue guidance to US$3.75 billion to US$3.77 billion, and issued Q4 guidance of US$976 million to US$996 million.
- Management flagged sales force capacity issues, slower net new bookings and lower Domain and residential subscription revenue, alongside the planned Vexcel acquisition. Together, these factors highlight execution and workforce pressures behind the headline guidance raise.
- We will now look at how CoStar Group’s raised guidance but slower bookings could reshape the investment narrative from here.
CoStar Group Investment Narrative Recap
To own CoStar Group, you need to believe the platform can keep turning its deep data, marketplaces and AI tools into steadier profit, not just higher sales. The raised 2026 revenue guidance, alongside Q3 net income of US$74 million, keeps that margin story intact. The key near term swing factor is still sales execution, since management has flagged capacity constraints and softer net new bookings.
The biggest risk right now sits in that same engine room. If sales hiring, retention and residential monetisation do not improve, the guidance lift could matter less than slower future bookings. The latest update looks meaningful for earnings, but it does not fully resolve revenue growth concerns.
The Vexcel acquisition sits closest to this guidance story because it speaks directly to CoStar Group’s ability to deepen its data edge while tightening costs elsewhere. Folding high resolution aerial and street level imagery into the suite adds tens of billions of new data fields per property, which can support products across commercial, residential and risk analytics.
For you, the question is whether Vexcel becomes a real catalyst or just more complexity. If CoStar integrates this imagery cleanly into tools like Apartments.com, Homes.com and Debt Solutions, it strengthens the case that richer datasets can offset slower sales hiring. Poor execution would instead raise concern that acquisitions distract from fixing bookings and residential revenue softness.
CoStar Group’s current analyst playbook points to revenue of US$4.7b and earnings of US$678.0m by 2029, built on 8.4% yearly top line growth and an earnings increase of about US$499m from the US$179.0m reported today.
Uncover how CoStar Group's fair value indicates a 19% potential upside to its current price before other investors close that valuation gap.
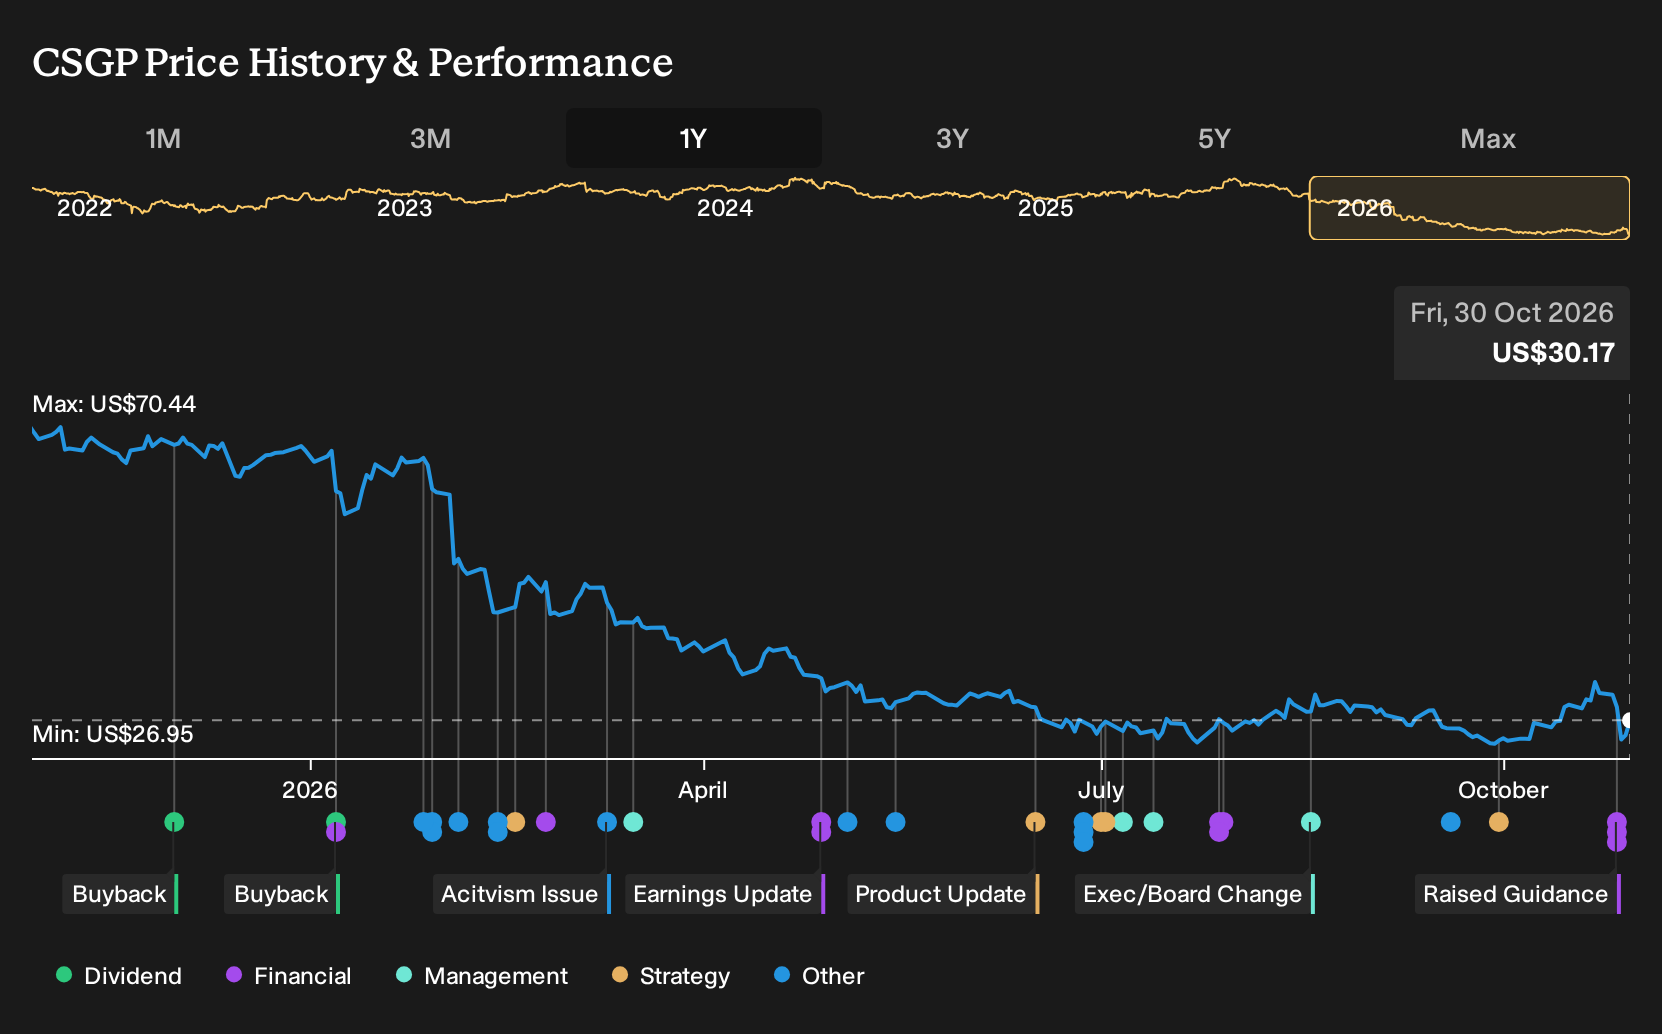
Exploring Other Perspectives
One alternative view puts Homes.com monetisation at the centre of the CoStar Group story rather than bookings risk. Before this guidance update, the most optimistic analysts were building in revenue of about US$5.2b and earnings of roughly US$821m by 2029. That is far more upbeat than consensus, and the latest guidance could push those scenarios to evolve.
Explore 4 other CoStar Group fair value estimates, including one that suggests as much as 157% potential upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your CoStar Group research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for CoStar Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate CoStar Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond CoStar Group?
Once you have weighed up CoStar Group, it can help to compare it with other companies that match your risk profile, income needs and preferred business models. The Simply Wall St screener lets you filter for very specific traits so you can quickly narrow a crowded market down to a short list that deserves a closer look.
- For investors who want quality at a discount, start with a focused list of 29 high quality undervalued stocks that currently trade below their estimated worth based on fundamentals.
- If capital preservation ranks high on your checklist, narrow the field to 30 resilient stocks with low risk scores that pair steadier financial profiles with lower risk scores.
- When balance sheet strength matters most, concentrate your research on a list of solid balance sheet and fundamentals (25 results) so you can focus on businesses with healthier leverage and liquidity.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com