


- Intuitive Surgical reported third quarter 2026 results with revenue of US$3.0b compared with US$2.5b a year earlier, while quarterly net income declined to US$522.8m from US$704.4m and diluted EPS from continuing operations moved to US$1.49 from US$1.95.
- Across the first nine months of 2026, Intuitive Surgical's revenue rose to US$8.7b compared with US$7.2b. Profit growth was comparatively modest, which suggests higher activity and system use are pulling in more sales, while costs or pricing are weighing on quarterly profitability.
- We will look at how Intuitive Surgical's investment narrative holds up against strong revenue momentum alongside softer third quarter net income.
Intuitive Surgical Investment Narrative Recap
To own Intuitive Surgical, an investor needs to be comfortable with a business that trades current profit pressure for procedure and platform expansion. The latest quarter shows strong revenue at US$3.0b but lower net income and EPS, so the short term focus is whether higher system use and geographic rollout can support earnings quality as costs run hotter.
The near term catalyst still sits in procedure growth and recurring instruments and service revenue, especially outside the US. The biggest operational risk right now is that pricing pressure, new robotic competitors and weaker hospital budgets in regions such as China slow new system placements and pull profitability away from recent trends.
The most relevant update is Intuitive Surgical’s nine month 2026 performance. Revenue reached US$8.7b compared with US$7.2b a year earlier, while net income moved to US$2.2b and diluted EPS from continuing operations reached US$6.07. That mix points to solid activity across da Vinci and Ion even as quarterly profitability looks softer.
For catalysts, those figures tie directly into the earlier thesis built on procedure growth, expansion in markets such as India, Europe and distributor regions, and a larger installed base that feeds recurring revenue. The earnings reset puts more attention on execution, particularly on cost discipline, pricing resilience against Johnson & Johnson and others, and how well new platforms and software rollouts convert into sustained operating margins.
Intuitive Surgical's narrative projects US$15.5b revenue and US$4.8b earnings by 2029. This aligns with analysts' assumption of 11.9% yearly revenue growth and implies a US$1.7b earnings increase from US$3.1b today.
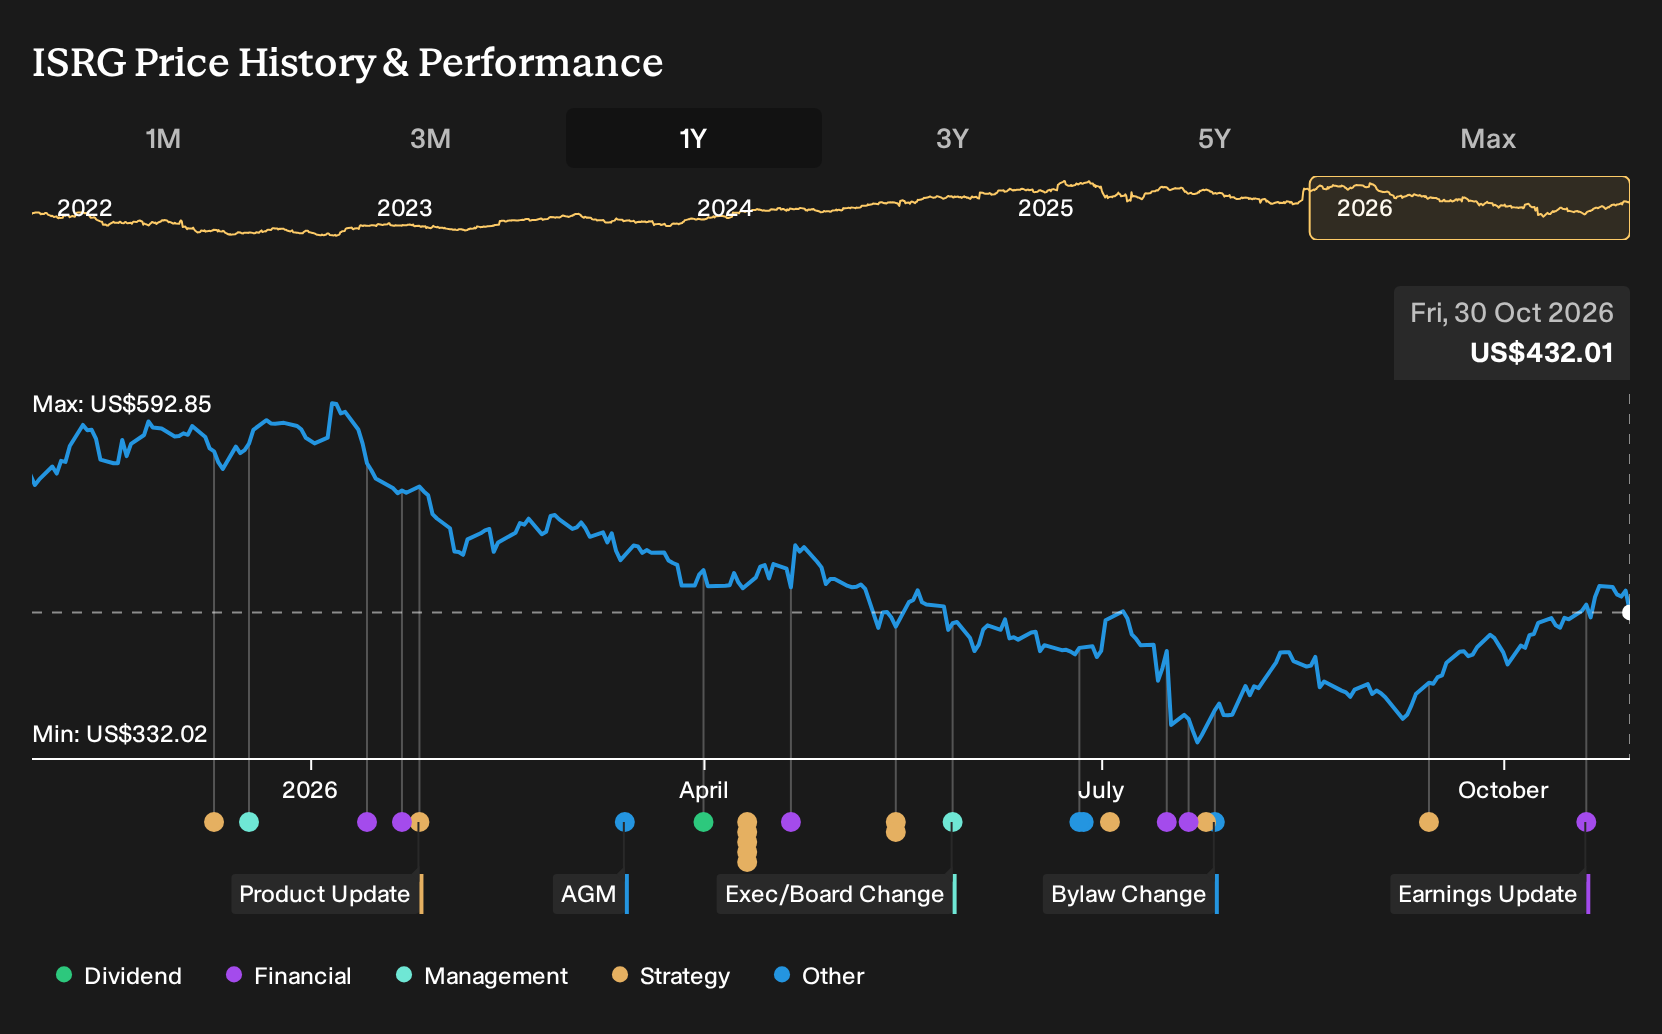
Uncover how Intuitive Surgical's fair value indicates a 10% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Here is where opinions really split. The most cautious analysts worry that Intuitive Surgical never fully converts its broader portfolio into stronger earnings. They were only pencilling in around US$14.9b of revenue and US$4.0b of profit by 2029 before this report, far below the more optimistic forecasts. That gap shows how sharply expectations differ. Treat this quarter as a fresh data point and explore several viewpoints before deciding what story you think now fits best.
Explore 8 other Intuitive Surgical fair value estimates, including one that suggests as much as 23% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Intuitive Surgical research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Intuitive Surgical. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Intuitive Surgical's overall financial health at a glance.
Looking for more investment ideas beyond Intuitive Surgical?
If this Intuitive Surgical update has sharpened your thinking, use the extra context to refresh the rest of your watchlist. You can stress test your current holdings or source completely new opportunities by scanning a few focused stock lists built around different risk and return profiles.
- If capital preservation is top of mind, start with a basket of companies that tend to show steadier fundamentals through volatility by reviewing 30 resilient stocks with low risk scores.
- For investors who want quality at a more appealing entry point, filter for stronger balance sheets and earnings support using the 29 high quality undervalued stocks.
- Income focused readers can zero in on dependable cash return potential by working through a curated 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com