


Old Second Bancorp (OSBC) just wrapped up a busy third quarter, with earnings, a completed buyback tranche, and a higher cash dividend all landing within days of each other for investors.
Despite the busy October news flow, Old Second Bancorp’s share price has eased in the short term, with the stock down 3.97% over 90 days. However, the year-to-date share price return of 24.67% and 1-year total shareholder return of 37.05% point to momentum that has built over a longer stretch as investors weigh improved earnings, capital returns and changing perceptions of risk around the bank’s credit profile.
Scan beyond Old Second Bancorp and explore how other capital return stories compare in our curated list of 29 high quality undervalued stocks at the crossroads of earnings power and balance sheet strength.
Old Second Bancorp appears to be a solid regional lender based on recent earnings and capital returns, but the share price has already moved a long way. The question is whether the current valuation still leaves enough value on the table.
Most Popular Narrative: 13% Undervalued
Old Second Bancorp’s most followed valuation storyline pegs fair value at $28 per share, compared with a last close of $24.29. This frames the current price as a discount that relies heavily on its lending engine and balance sheet mix holding together.
The growing national specialty lending and powersports portfolio, with APRs above 10% and contribution margins above 8% even with loss rates around 2%, provides Old Second Bancorp with a higher yielding engine that can support revenue and net margin resilience.
See why 1 investors see Old Second Bancorp as 13% undervalued.
Result: Fair Value of $28 (UNDERVALUED)
Still, the story around Old Second Bancorp can change quickly if elevated net charge offs linger, or if Illinois-focused exposure and digital competitors start to bite harder.
Find out about the key risks to this Old Second Bancorp narrative.
Another View On Old Second Bancorp’s Valuation
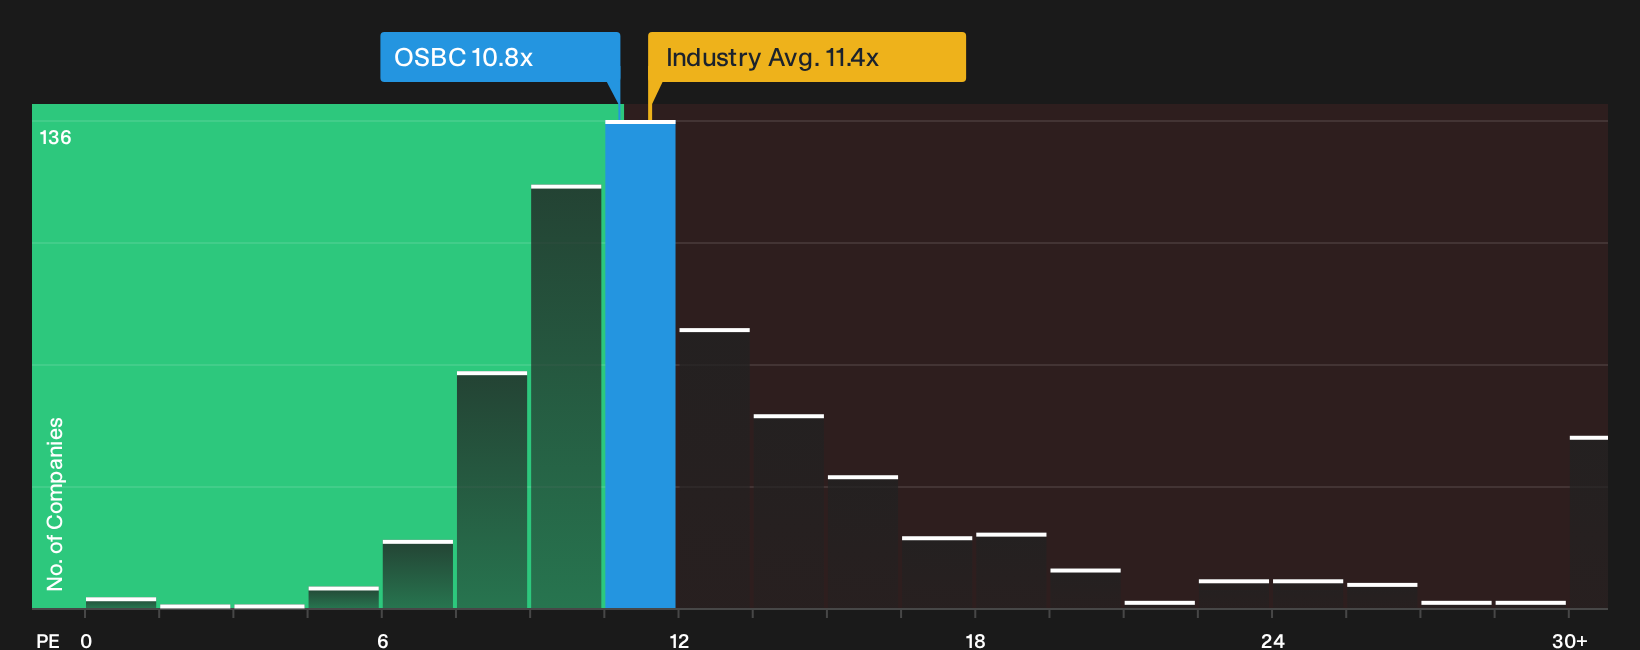
While the narrative fair value pins Old Second Bancorp at $28 per share, the P/E math sends a mixed message. The stock trades at 10.8x earnings, below the US Banks industry on 11.4x and peers on 13.5x, yet slightly above its own 10.4x fair ratio. That gap hints at some valuation cushion, but also suggests limited room for error if earnings or credit quality slip.
See what the numbers say about this price in more detail in our valuation breakdown, starting with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Curious whether Old Second Bancorp’s risk and reward mix lines up with your own tolerance and goals? Act promptly, review the data, and then weigh the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Old Second Bancorp?
Old Second Bancorp might fit your watchlist today, yet you leave real insight on the table if you ignore other opportunities filtered by balance sheet quality, value and resilience.
- Target durability in tougher conditions by zeroing in on companies screened for resilience using the 30 resilient stocks with low risk scores.
- Capture potential mispricings by scanning for quality companies trading below what their fundamentals suggest via the 29 high quality undervalued stocks.
- Strengthen your core holdings by focusing on financially sturdy businesses highlighted in the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com