


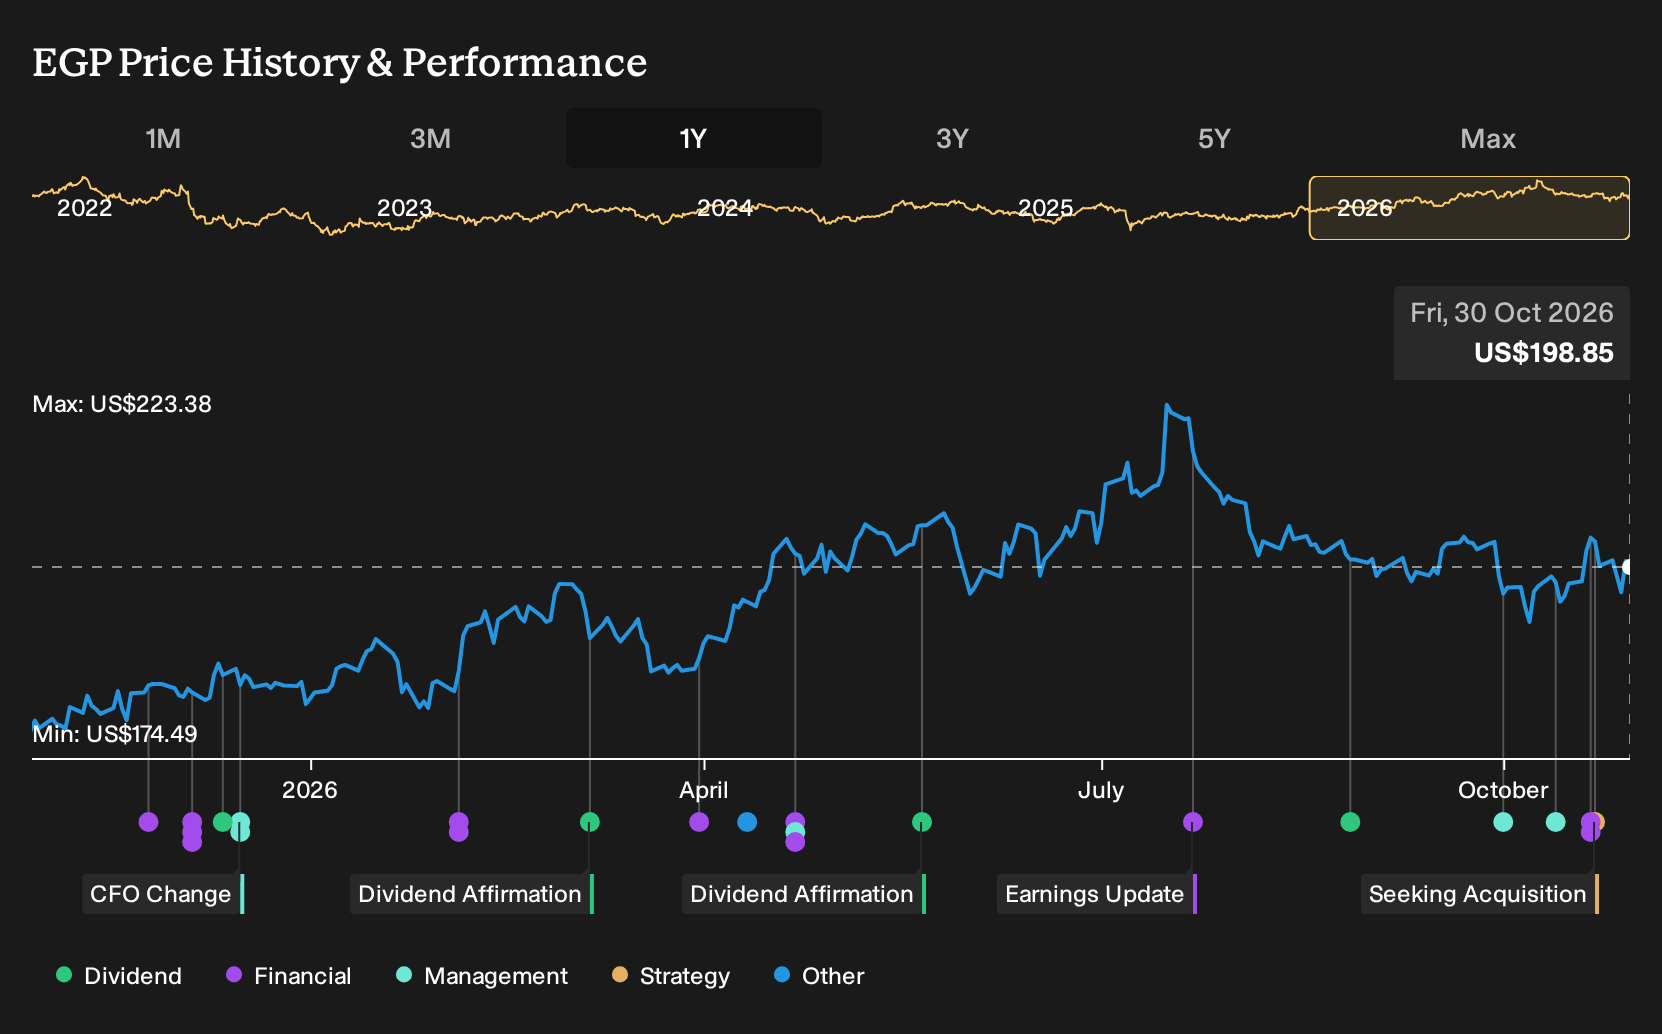
- EastGroup Properties reported third quarter 2026 revenue of US$199.44 million and net income of US$78.38 million. The company raised full year earnings guidance and lifted its 2026 acquisitions target to US$360 million, backed by US$485 million of forward equity funding and low leverage metrics.
- The combination of higher acquisition guidance, active development spending, and a balance sheet with debt to total market capitalization at 14.6% signals that EastGroup Properties is leaning into growth while keeping financial flexibility in focus.
- We will now look at how EastGroup Properties stepped up acquisition plans might reshape the investment narrative from here.
EastGroup Properties Investment Narrative Recap
To own EastGroup Properties, you need to believe its infill industrial focus in high growth US markets can stay leased at healthy rates while new developments and acquisitions convert into steady income. The higher 2026 acquisition guide and forward equity funding keep that growth plan in motion rather than resetting the story.
The key short term swing factor is execution on the much larger acquisition and development pipeline without eroding returns or leasing momentum. The biggest risk remains committing too much capital if tenant demand or re leasing spreads soften further. This update raises that exposure but does not materially change the near term risk profile.
The most relevant fresh datapoint is the third quarter 2026 earnings release. Revenue was US$199.44 million and net income was US$78.38 million, with full year net income guidance lifted to US$322.76 million to US$325.99 million, or US$5.99 to US$6.05 per diluted share.
That guidance ties directly into the acquisition push. Higher earnings expectations assume EastGroup Properties keeps leasing new projects and recently bought assets at levels that support cash flow, despite easing spreads and some softer West Coast markets. Any gap between that plan and actual leasing or occupancy is where the near term risk and catalyst now sit.
EastGroup Properties' narrative projects US$985.7 million revenue and US$367.7 million earnings by 2029. That profile rests on an assumed 9.5% yearly revenue growth and an earnings increase of about US$62.9 million from US$304.8 million today.
Uncover why EastGroup Properties' fair value indicates a 15% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Fair value estimates from three members of the Simply Wall St Community run from US$139.14 to US$228.08, so you are seeing a wide spread of opinions on EastGroup Properties before the latest guidance and acquisition push. Factor in the enlarged 2026 acquisition and development pipeline, and then ask how softer leasing or slower spreads could shift those views.
Explore 2 other EastGroup Properties fair value estimates, including one that suggests up to 30% downside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your EastGroup Properties research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for EastGroup Properties. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which helps you evaluate EastGroup Properties' overall financial health at a glance.
Looking for more investment ideas beyond EastGroup Properties?
If EastGroup Properties has sharpened your thinking about income, growth, and balance sheet resilience, it can be useful to line it up against other candidates built on different strengths. The Simply Wall St Screener lets you quickly filter for businesses that match the kind of risk, return profile, or dividend focus you want to lean into next.
- For investors who want a focus on strong finances before anything else, start with a list of solid balance sheet and fundamentals (25 results) that keeps financial resilience front and center.
- If you are looking for companies where the market price sits below fundamental quality, scan a 29 high quality undervalued stocks to compare against EastGroup Properties on potential mispricing.
- For readers who care most about income strength, use a 5 dividend fortresses that screens for higher yields backed by fundamental checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com