


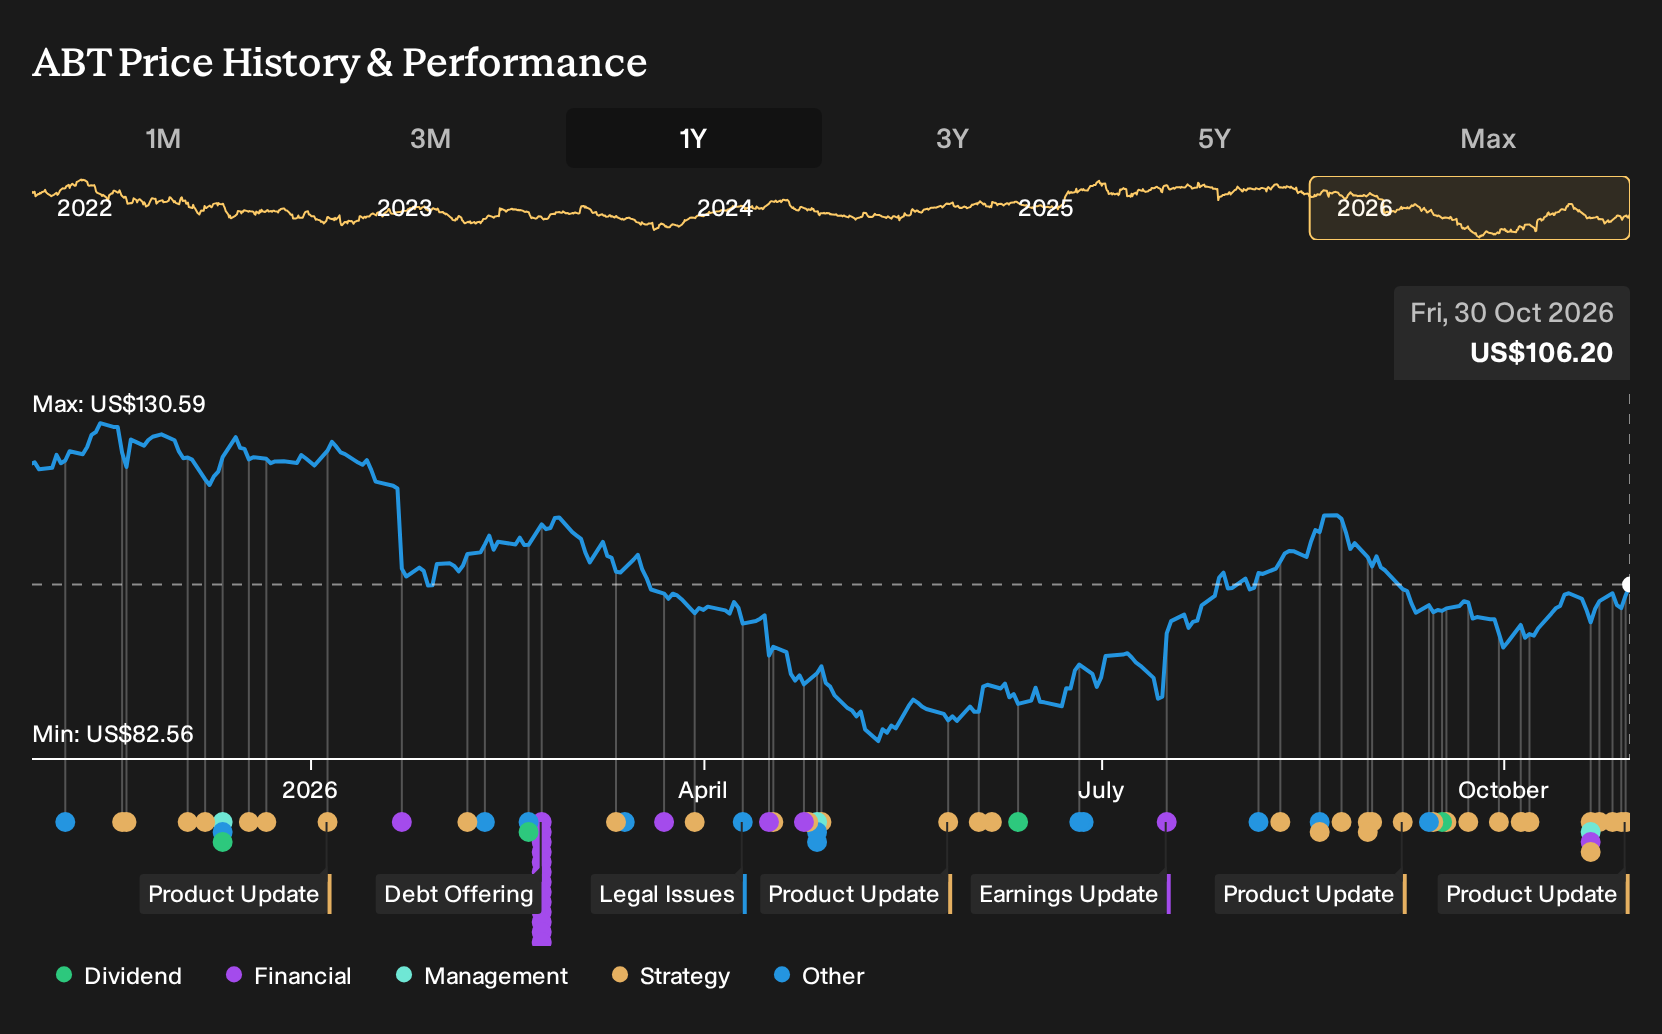
- Abbott Laboratories has outlined a plan to separate its Nutrition business into a standalone public company and, in parallel, reported multiple medical device and diagnostic product updates including FDA approval of the Amplatzer Paraclose PVL Occluder, initiation of the CROWN-MV Cephea mitral valve trial, and new whole genome Oncodetect MRD data.
- The split would shift Abbott Laboratories further toward medical technology and diagnostics, while the Nutrition spin-off would carry its own growth profile, cost structure and legal exposure, changing how investors think about cash flow mix and capital allocation across the two entities.
- We will look at how Abbott Laboratories' investment narrative is reshaped by the Nutrition spin-off and by execution across its medtech pipeline.
Abbott Laboratories Investment Narrative Recap
To own Abbott Laboratories, you need to believe the medtech and diagnostics engine can offset Nutrition legal overhangs and capital needs, while the Nutrition spin off simplifies the story over time. The near term hinge is execution in devices and diagnostics after Q3 2026, where sales reached US$13.0b but net income and EPS stepped down versus last year.
The biggest operational risk remains focused on margins and cash demands. Legal and settlement costs in infant formula, higher debt, and a dividend that is not fully covered by earnings limit financial flexibility. Recent device wins and diagnostics launches support the narrative but do not yet alter the margin and leverage profile in a material way.
The Amplatzer Paraclose PVL Occluder approval looks most directly relevant for Abbott Laboratories at this stage. It fits squarely into structural heart, a segment where the business already offers MitraClip and Tendyne, and it targets patients who might otherwise face repeat open heart surgery. That positioning can support procedure volumes if adoption becomes broad.
For investors monitoring catalysts, this approval adds an incremental, clinically specific driver alongside the larger Libre and Cancer Diagnostics franchises. Execution questions center on training centers, reimbursement, and how quickly cardiology teams shift PVL patients to a catheter based option, since each of those factors influences the extent to which this product supports revenue mix and margins.
Abbott Laboratories' narrative projects US$60.0b revenue and US$9.6b earnings by 2029. This assumes 8.8% yearly revenue growth and an earnings increase of about US$4.2b from US$5.4b today.
Uncover why Abbott Laboratories' fair value indicates a 13% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The four fair value estimates from the Simply Wall St Community span roughly US$119 to US$149 per share, so you are seeing a wide retail spread around Abbott Laboratories. Those views sit alongside unresolved Nutrition litigation risks and ambitious margin expectations, which create real execution pressure. Investor opinions clearly diverge. Explore several viewpoints before committing capital.
Explore 3 other Abbott Laboratories fair value estimates, including one that suggests as much as 40% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Abbott Laboratories research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Abbott Laboratories. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Abbott Laboratories' overall financial health at a glance.
Looking for more investment ideas beyond Abbott Laboratories?
Once you have a view on Abbott Laboratories, it can help to compare it with other opportunities that match your risk tolerance and income needs using the Simply Wall St Screener.
- If capital preservation sits high on your list, start with a set of stocks that show lower overall risk characteristics through the 30 resilient stocks with low risk scores.
- For readers focused on quality at a reasonable price, scan companies that pair solid fundamentals with valuations that may look appealing using the 29 high quality undervalued stocks.
- Income oriented investors can zero in on steady cash returns by reviewing a 5 dividend fortresses that might suit a yield focused approach.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com