


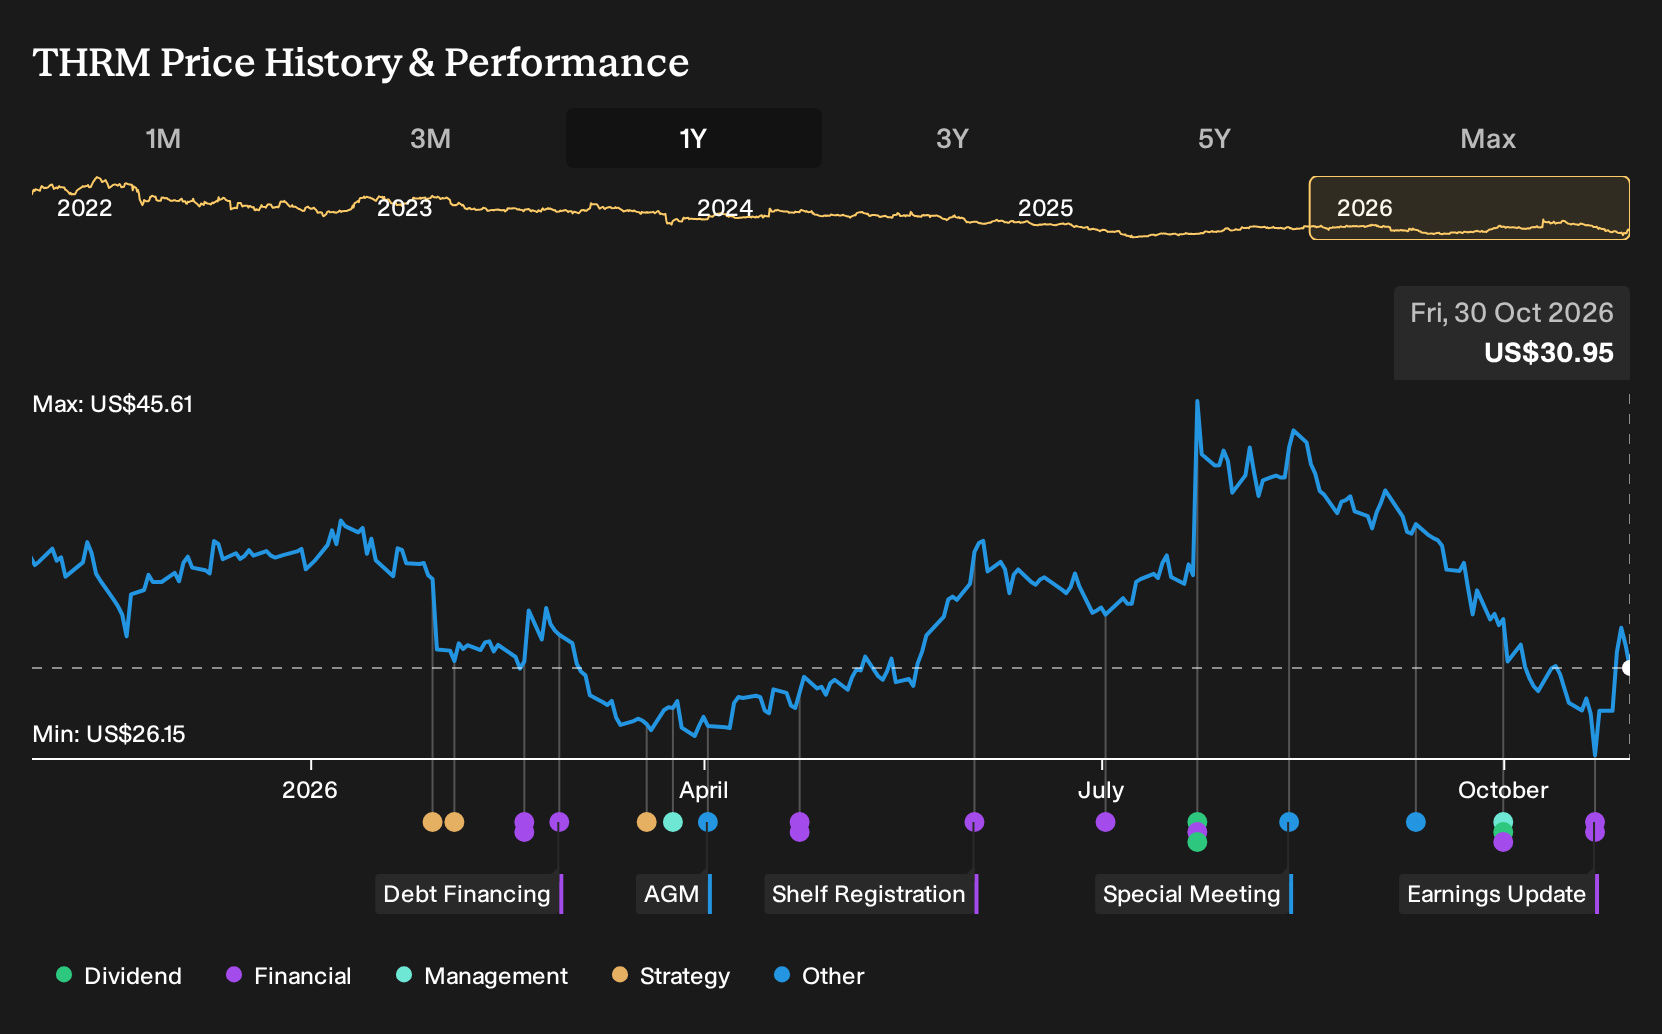
- Gentherm completed a US$60 million repurchase of 1,946,788 shares, or 6.34% of its equity base, and reported a third quarter net loss of US$2.59 million. The company also updated guidance, calling for 2026 product revenue between US$1.825b and US$1.925b.
- The combination of a sizeable buyback and a higher full year revenue outlook indicates that Gentherm management is prioritising long term demand visibility and capital return, even as earnings for the first nine months reached US$6.05 million, below the prior year period.
- Attention now turns to how Gentherm's investment narrative evolves in light of the higher 2026 product revenue guidance and the completion of the repurchase.
Gentherm Investment Narrative Recap
To own Gentherm, you need to be comfortable with a story built on higher content per vehicle and a bigger role in furniture and medical thermal solutions, while auto remains the anchor. The raised 2026 product revenue outlook points to management seeing solid demand visibility, although the recent quarterly loss and margin pressure keep execution risk front and center.
The main short term swing factor is whether Gentherm can stabilize profitability while absorbing inflation, logistics costs and integration work. The biggest risk is that cost recovery and footprint realignment trail expectations. The latest quarter highlights that margins remain fragile, so progress on efficiencies and product mix will likely matter more than headline revenue.
The most relevant update for that thesis is the new full year 2026 product revenue guidance of US$1.825b to US$1.925b, up from US$1.55b to US$1.65b. That is a sizable shift in expected activity across thermal comfort, valve systems and medical products, and it sits against a quarter that moved from profit a year ago to loss.
For you, the tension is clear. Gentherm is pointing to a larger top line built on auto content and newer end markets, while current earnings, margins and a Zacks Rank #5 label flag near term pressure. How cleanly the business converts that higher revenue run rate into cash and improved profitability remains the key catalyst and the key question.
Gentherm's narrative projects US$2.4b revenue and US$191.1 million earnings by 2029. This is based on an assumed 15.6% yearly revenue growth and an earnings increase of about seven times from the current US$26.6 million level.
Uncover why Gentherm's fair value indicates a 55% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate angle on Gentherm focuses less on near term margin strain and more on the chance that footprint consolidation really does lift profitability. The most optimistic analysts were penciling in about US$3.8b of revenue and US$302.7 million of earnings by 2029 before this update. Those forecasts reflect a far more upbeat path than consensus, and today’s buyback plus raised guidance could push some models closer to that upper band. You do not need to agree with that view, but it is worth comparing it with your own expectations and exploring how both bullish and cautious narratives might shift as fresh data lands.
Explore 3 other Gentherm fair value estimates, including one that suggests as much as 154% potential upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Gentherm research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Gentherm. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Gentherm's overall financial health at a glance.
Looking For More Investment Ideas Beyond Gentherm?
Once you have formed a view on Gentherm, it can help to widen the lens and compare it with other companies that fit different risk, income, and balance sheet profiles. The Simply Wall St Screener is built for exactly that, letting you quickly surface opportunities that match your own style and constraints.
- If you want potential upside with a small starting price tag, scan for compact businesses that still have meaningful financial strength using the 9 elite penny stocks with strong financials.
- For investors who care most about quality at a reasonable entry point, filter for resilient businesses trading below their estimated worth through the 29 high quality undervalued stocks.
- If capital preservation and stability are front of mind, focus on companies with sturdy finances and clean balance sheets by running the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com