


Whirlpool (WHR) is under closer scrutiny after a tough third quarter. The appliance maker moved from profit to a net loss and sharply cut its full year outlook, and it is also facing a credit rating downgrade.
Whirlpool shares have gained 6.5% over the past week following the earnings release and credit downgrade. However, the 90-day share price return of 20.2% and the year-to-date share price decline of 59.8% indicate that momentum has been fading for some time.
Scan Whirlpool's recent volatility alongside a curated shortlist of resilient alternatives in the same market cycle by checking the 30 resilient stocks with low risk scores right after reviewing this earnings shock.
The rebound after Whirlpool’s earnings shock and credit downgrade forces a blunt choice. Is this the moment to lean into the selloff, or does it make more sense to wait for a cheaper entry once the valuation is unpacked next?
Most Popular Narrative: 72% Undervalued
Whirlpool closed at $29.94, while the most followed narrative pegs fair value at $106.31 using a 12.54% discount rate. This frames the recent bounce against a much higher long term earnings story.
The SDA Global business is already running at around 12% EBIT margin with double digit sell through and high teens point of sale growth. If Whirlpool can scale this model further in stand mixers, espresso machines and blenders, the company could tilt its overall mix toward higher margin revenue and support a re rating of earnings power.
See why 3 investors see Whirlpool as 72% undervalued.
Result: Fair Value of $106.31 (UNDERVALUED)
Still, the bullish Whirlpool story can quickly fray if higher interest costs keep biting into cash generation, or if EBIT margins stall below internal ambitions.
Find out about the key risks to this Whirlpool narrative.
Another View: Whirlpool Through The SWS DCF Lens
The bullish narrative points to a fair value for Whirlpool around $106.31, yet the SWS DCF model paints a very different picture. On that cash flow view, WHR at $29.94 trades above an estimated future cash flow value of $14.33, which implies overvaluation rather than a bargain.
This split between earnings driven optimism and a more cautious cash flow model leaves a practical question for you as an investor: Which yardstick feels more reliable for a cyclical, capital intensive appliance maker that is currently loss making?
Look into how the SWS DCF model arrives at its fair value.
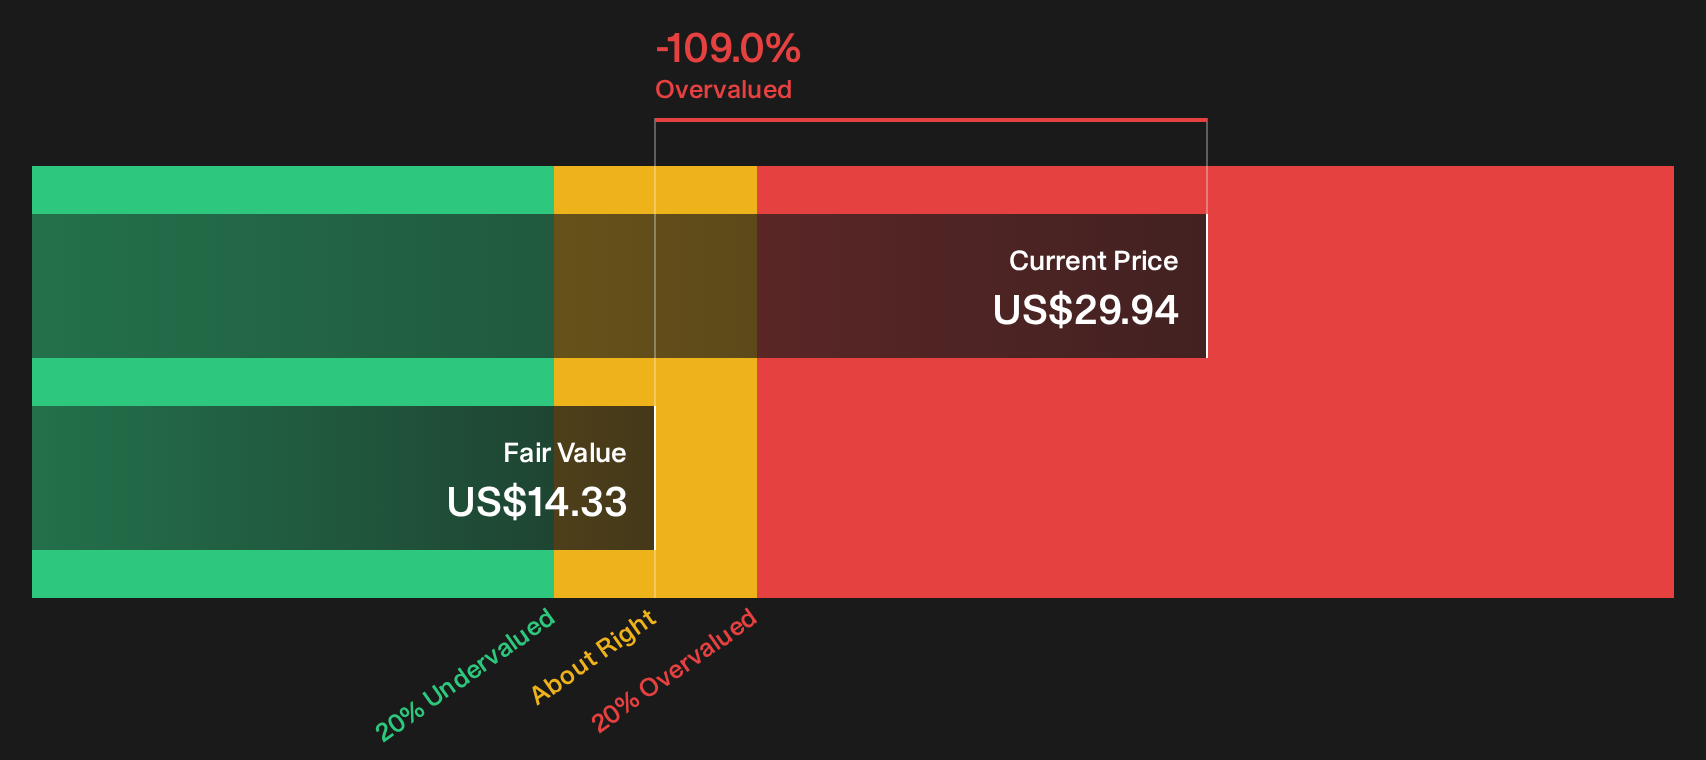
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Whirlpool for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Whirlpool are already forcing strong opinions, so consider the latest information carefully and build your own view by weighing the 2 key rewards and 2 important warning signs.
Ready For More Whirlpool Investment Ideas?
If Whirlpool has your attention after this volatility, do not stop here. Use the Simply Wall Street Screener to line up your next potential moves before the market does.
- Target resilient value by scanning companies that combine quality fundamentals with appealing pricing using the 29 high quality undervalued stocks.
- Build a sturdier core for your portfolio by focusing on financially robust businesses through the list of solid balance sheet and fundamentals (25 results).
- Hunt for lesser known opportunities with strong underlying metrics before they are widely talked about by checking the 18 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com