


BrightSpring Health Services (BTSG) just posted third quarter 2026 results that topped analyst expectations on both revenue and earnings, raised its full year outlook, and underlined confidence in organic growth into 2027.
BrightSpring Health Services shares reacted sharply to the earnings surprise, with a 1-day share price return of 11.08% and a 30-day share price return of 17.87%, helping push the stock to US$66.89. Momentum has been building for some time, as year to date the share price return is 74.19% and the 1-year total shareholder return is 102.39%. This suggests that investors are reassessing both growth prospects and risk around the story.
Compare how BrightSpring Health Services stacks up against other healthcare plays with strong momentum and fundamentals by reviewing the list of solid balance sheet and fundamentals (25 results) in the same bracket.
For BrightSpring Health Services, this surge now leaves a clear fork in the road. Are you paying up for sentiment, chasing an earnings beat, or for a business whose new guidance and earnings profile still leave room on valuation?
Most Popular Narrative: 5.2% Undervalued
BrightSpring Health Services is trading at $66.89 while the most followed narrative pegs fair value closer to $70.59, which puts the current enthusiasm against a backdrop of only a modest discount.
The real business is not home health. It is pharmacy.
Roughly 80% of revenue comes from specialty and institutional pharmacy services.
This is where the structural moat exists.
Patients are not “customers” in the retail sense; they are clinically managed cases. Once a patient enters an infusion or specialty pharmacy program, switching providers is rare because:
This creates low churn, recurring revenue, and embedded payer relationships.
See why 7 investors see BrightSpring Health Services as 5% undervalued.
Result: Fair Value of $70.59 (UNDERVALUED)
Still, the BrightSpring Health Services story can be knocked off course if reimbursement terms tighten or if pharmacy contracts are renewed on less favorable economics.
Find out about the key risks to this BrightSpring Health Services narrative.
Another View: BrightSpring Health Services Looks Expensive On Earnings
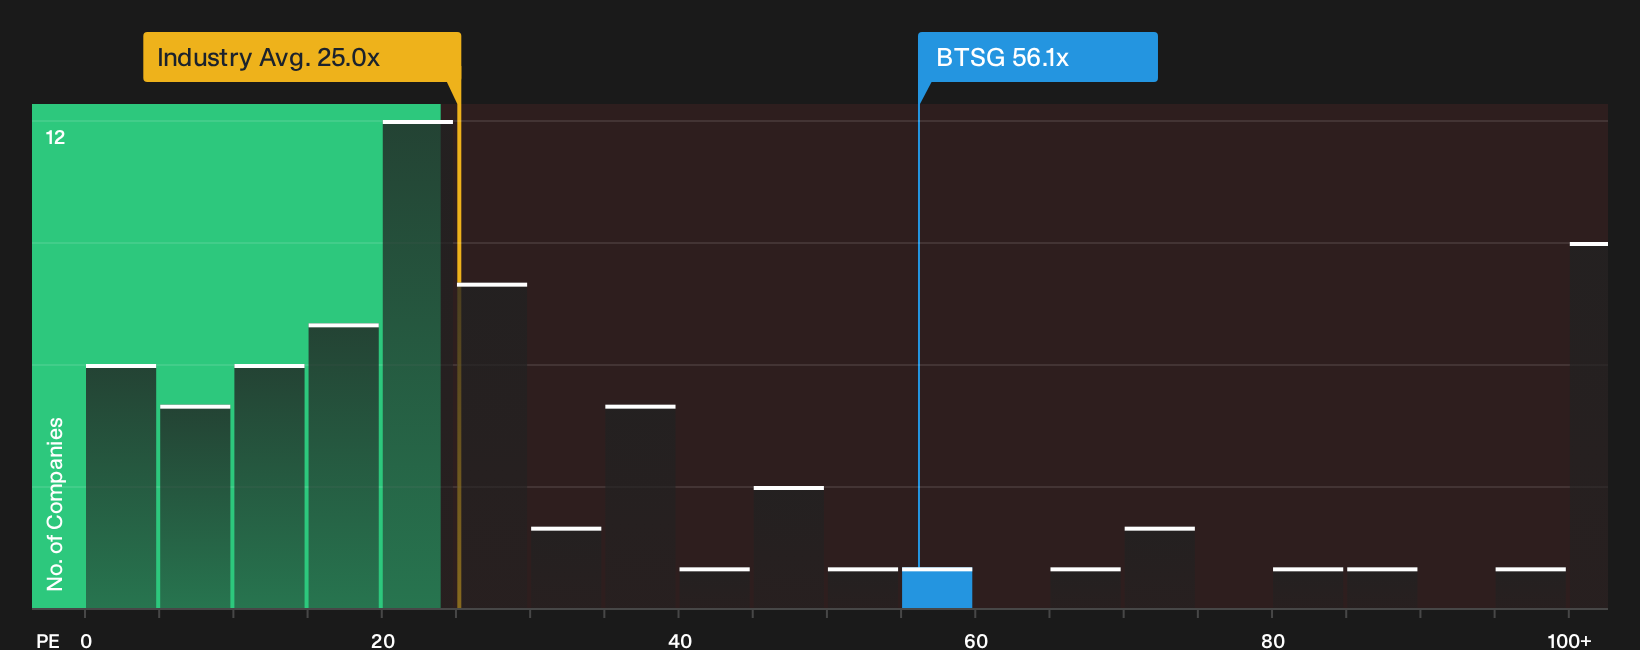
There is a very different picture when you look at BrightSpring Health Services through its P/E ratio. The stock trades at 56.1x earnings, compared with 37.1x for peers and 25.3x for the wider US Healthcare group. The fair ratio is estimated at 35.4x. That gap points to meaningful valuation risk if sentiment cools or growth expectations reset.
For investors who want to see how this compares with a cash flow view, it can help to step through the SWS DCF model in full. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling torn between the enthusiasm around BrightSpring Health Services and the valuation risks just laid out is reasonable. Treat this as your cue to move quickly, dig into both sides of the story, and then anchor your own stance using the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond BrightSpring Health Services?
If BrightSpring Health Services has sharpened your focus on quality, do not stop here. Broaden your watchlist and pressure test your thesis against other opportunities.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced quality by reviewing the 29 high quality undervalued stocks before the market closes the gap.
- Spot companies that quietly compound with fewer shocks by checking the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com