


- United Parcel Service raised its fourth quarter and full year 2026 guidance, projecting about US$25.7b in Q4 revenue, US$92.6b for the year, operating profit of roughly US$3.3b in Q4 and US$8.75b for 2026, alongside third quarter revenue of US$22,853m and goodwill and asset impairment charges of US$182m.
- UPS is pairing higher 2026 earnings guidance with a planned US$5.4b dividend outlay and a focus on premium logistics segments such as healthcare and AI data centre projects. This highlights a push toward higher value services even as reported net income for recent periods reflects impairment charges and a mixed earnings picture.
- We will look at how United Parcel Service's investment narrative is shaped by raised 2026 guidance and a push into higher value logistics.
Scan for other logistics and infrastructure stocks pursuing higher value niches like UPS by checking the hand picked 54 AI infrastructure stocks that could benefit from the AI data centre build out.
United Parcel Service Investment Narrative Recap
To stay comfortable as a United Parcel Service shareholder, you need to believe the pivot to higher value segments, automation and the AI data centre and healthcare logistics opportunity can support the earnings profile that management is now guiding to. The raised 2026 outlook gives a clearer revenue and profit marker, but it also tightens the bar the business will be measured against.
The most important near term swing factor is execution on efficiency targets while keeping service quality intact as volumes shift and facilities consolidate. The biggest risk is that high dividends and a meaningful debt load constrain flexibility if trade flows soften or the expected cost savings and mix benefits arrive more slowly than planned.
The raised 2026 guidance is the announcement that really matters here. UPS is now pointing to US$25.7b of Q4 2026 revenue and US$3.3b of operating profit, plus US$92.6b of full year turnover and US$8.75b of operating profit, which implies diluted EPS of about US$7.28.
Those figures sit alongside a Q3 where revenue reached US$22,853m while net income and EPS were lower than a year earlier and included US$182m of goodwill and asset impairment charges. For you as an investor, that combination puts the focus squarely on whether premium logistics growth, AI data centre work and ongoing automation can turn today’s operational reshaping into the earnings and cash flow that this guidance outlines.
What The Analyst Forecasts Assume For United Parcel Service
Analyst models for United Parcel Service lean heavily on a few clear levers. Revenue is projected to rise by 3.7% each year over the next three years, helped by a shift toward higher value shipments rather than simply chasing volume at any price.
Earnings today are put at US$4.4b, with the consensus pointing to US$7.3b of profit and US$101.8b of revenue in 2029. That implies an earnings increase of about US$2.9b over the period, which is a sizeable step up that assumes margin expansion from 4.8% to 7.2% as the network automation and mix changes bed in.
United Parcel Service's narrative projects US$101.8b revenue and US$7.3b earnings by 2029. This requires 3.7% yearly revenue growth and an earnings increase of about US$2.9b from US$4.4b today.
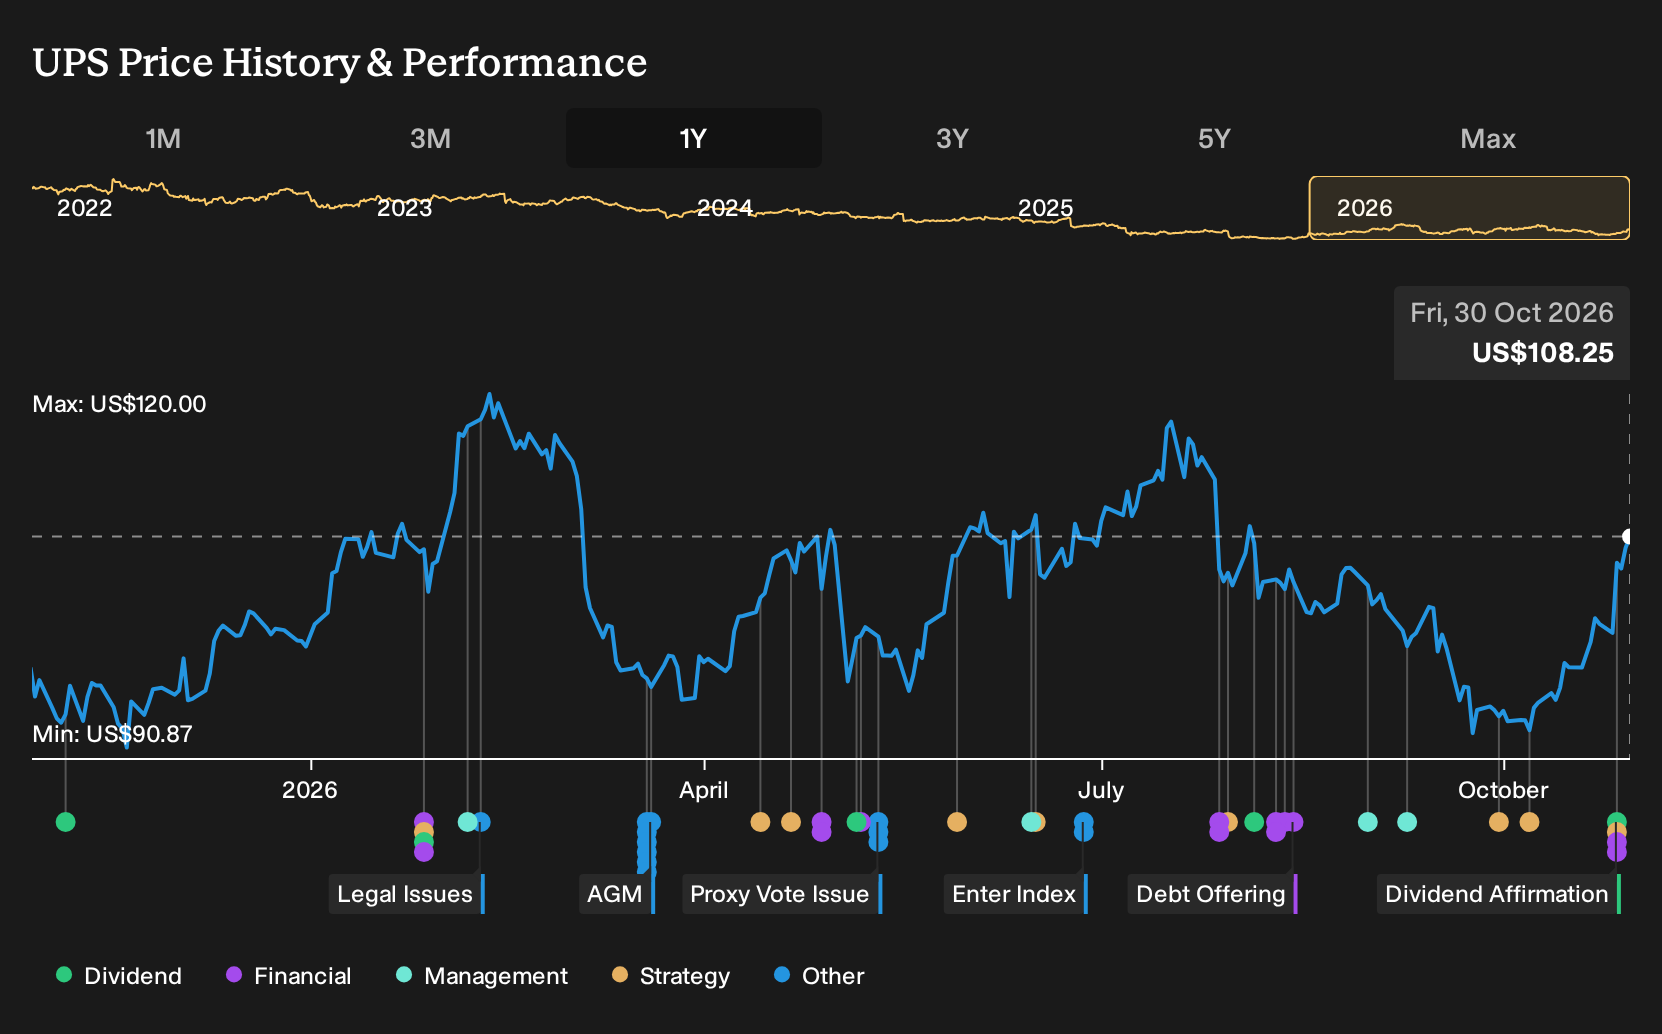
To reconcile those figures with current pricing, analysts work off a P/E of 16.9x on those 2029 earnings, compared with 20.4x today and a sector level of 16.4x for US logistics peers. That framework gives a consensus target of US$112.54 per share, with a wide range of views from US$76 at the low end to US$132 at the high end, which shows how differently people are reading the same story.
For you as a shareholder or prospective investor, the key question is whether the operational changes and premium focus can plausibly support US$7.3b of earnings without stretching assumptions. The forecast also bakes in modest share count growth of 0.31% a year, so most of the heavy lifting in per share numbers is expected to come from margin gains rather than financial engineering.
Uncover why United Parcel Service's fair value indicates a 4% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on United Parcel Service puts labor risk front and center for you. The most bearish analysts worry that rising wage pressure and a tough 2028 contract round may cap the benefit from automation. Before this guidance hike, they were working off about US$91.1b of 2029 revenue and roughly US$6.2b of earnings, which is far more cautious. These forecasts were set before the latest guidance and dividend confirmation, so some of these stories may shift. Use that spread in opinions as a prompt to compare several narratives and decide which set of assumptions feels closest to your own.
Explore 8 other United Parcel Service fair value estimates, including one that suggests as much as 22% downside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your United Parcel Service research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for United Parcel Service. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate United Parcel Service's overall financial health at a glance.
Looking For More Investment Ideas Beyond United Parcel Service?
If the United Parcel Service story has you thinking about how to position your wider portfolio, it can help to line it up against other opportunities that share some of the same qualities or offer a different balance of risk and reward. The Simply Wall St Screener is set up for exactly that, letting you filter by fundamentals rather than headlines.
- If capital preservation sits high on your priority list, compare UPS with a curated set of 30 resilient stocks with low risk scores that score well on resilience and financial stability.
- For readers who care most about balance sheet strength and business quality, start with a list of solid balance sheet and fundamentals (25 results) to see which companies pair robust finances with underlying fundamentals.
- If you want to broaden your watchlist with potential future leaders, scan a 18 high quality undiscovered gems that currently fly under the radar despite stronger metrics than their visibility suggests.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com