


AXIS Capital Holdings (AXS) just posted its third quarter 2026 results, reporting higher revenue alongside lower quarterly earnings and updating investors on an active share repurchase program completed under its February 2026 authorization.
The latest earnings and buyback update lands after a mixed run in AXIS Capital Holdings’ trading performance, with the share price delivering an 11.33% 1 month share price return while the 90 day share price return slipped slightly. However, the 1 year total shareholder return of 13.90% and 3 year total shareholder return of about 105% point to momentum that has been building over a longer stretch as investors reassess growth prospects and risk after recent underwriting results and capital returns.
Scan how AXIS Capital Holdings compares with other specialty insurers by running through the hand-picked 30 resilient stocks with low risk scores that focus on resilient balance sheets and steadier return profiles.
That recent 11.33% swing in AXIS Capital Holdings could be investors rewarding steadier underwriting and capital returns, or just chasing sentiment after an earnings beat. The valuation work starts with separating those two stories.
Preferred P/E of 7.7x: Is it justified?
Valuation work on AXIS Capital Holdings starts with price against earnings, where the stock trades on a P/E of 7.7x despite steady profitability and a long operating history in specialty insurance and reinsurance.
The P/E ratio compares what investors are paying for each dollar of current earnings, and for an insurer like AXIS Capital Holdings it often reflects expectations around underwriting discipline, investment income stability, and the potential for future returns on equity rather than rapid top line expansion.
AXS is described as good value on several fronts, including a P/E of 7.7x that sits below peer averages of 10.9x and the broader US insurance industry at 11.5x, which suggests the market is assigning a lower earnings multiple even though the business generates high quality earnings and has grown profits strongly over the past 5 years.
The estimated fair P/E of 10.3x is also higher than the current multiple, implying a level that the market could move towards if investors reassess the balance between AXIS Capital Holdings' earnings power, return on equity of 16.1%, and its record of profit growth over the longer term.
Explore the SWS fair ratio for AXIS Capital Holdings.
Result: Price-to-earnings of 7.7x (UNDERVALUED)
Still, any rerating case for AXIS Capital Holdings can be knocked back by insurance cycle turns or large catastrophe losses that pressure underwriting results.
Find out about the key risks to this AXIS Capital Holdings narrative.
Another View: AXIS Capital Holdings Through A Cash Flow Lens
The earnings multiple presents AXIS Capital Holdings as inexpensive, and the SWS DCF model suggests an even lower implied valuation. On that cash flow view, the stock at $104.87 is compared with an estimated future cash flow value of $284.60. This indicates a very wide gap in valuation that investors may wish to assess for themselves.
Large differences between earnings-based and cash-flow-based estimates often reflect differing assumptions about future profitability and required returns. When the gap is this wide, it raises an important question for AXIS Capital Holdings: Is the market being overly cautious, or is the model assuming overly favorable long-term cash generation?
Look into how the SWS DCF model arrives at its fair value.
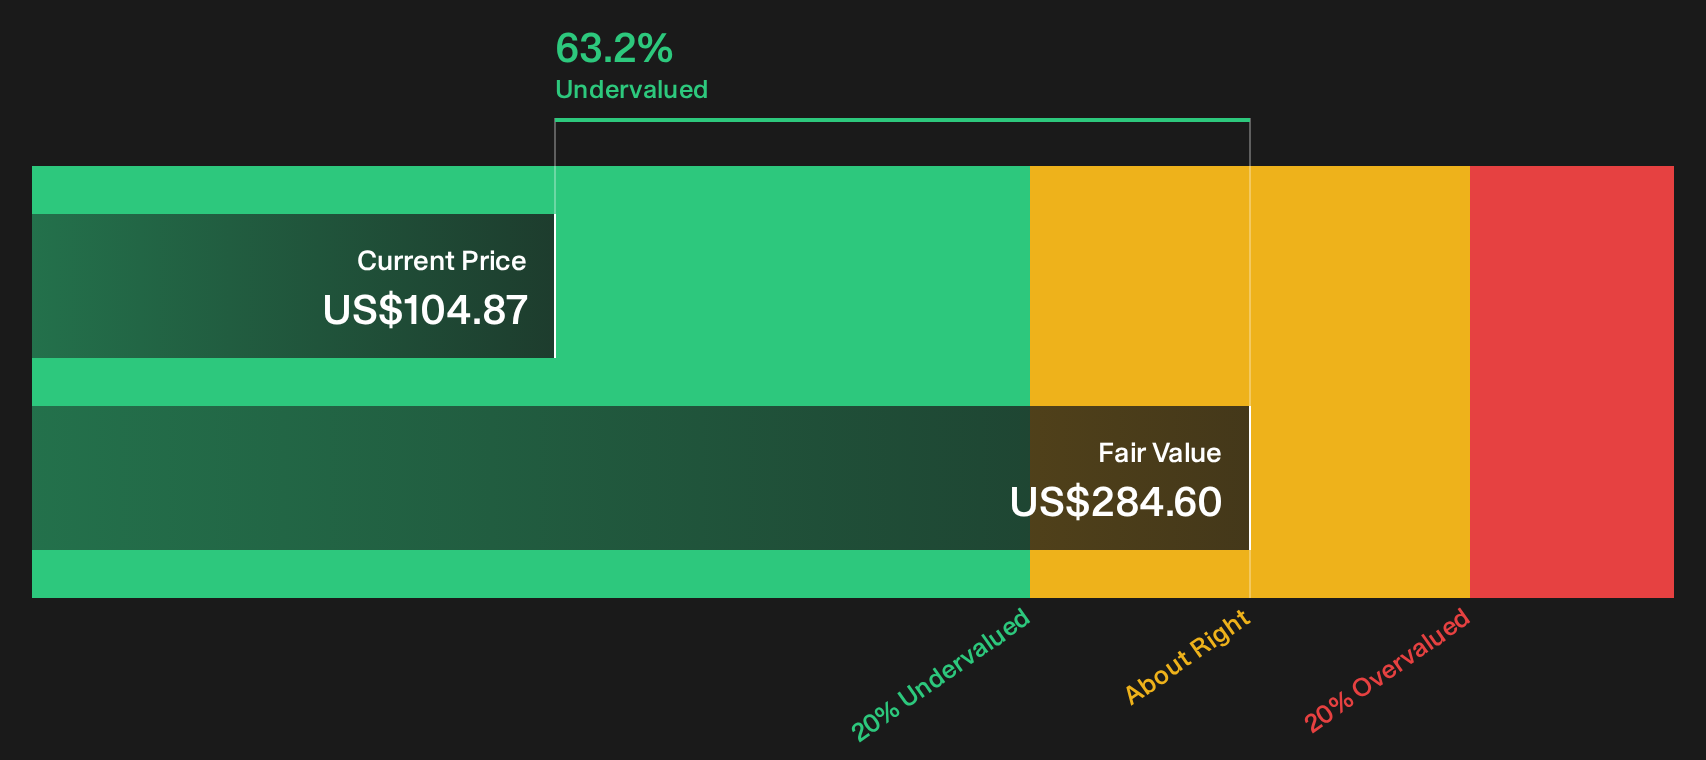
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out AXIS Capital Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment in this review of AXIS Capital Holdings is mixed, so consider the data carefully, weigh the evidence yourself, and then explore the 3 key rewards
Looking for more investment ideas beyond AXIS Capital Holdings?
If AXIS Capital Holdings has sharpened your thinking on value and risk, broaden your watchlist with a few focused stock shortlists built from the same data-driven framework.
- Target resilient compounding potential by scanning a 29 high quality undervalued stocks that surfaces businesses with strong fundamentals trading at compressed valuations.
- Build a sturdier income stream by reviewing a 5 dividend fortresses focused on companies combining higher yields with balance sheet support.
- Strengthen your downside protection by working through a list of solid balance sheet and fundamentals (25 results) designed to spotlight financially robust operators before the crowd pays attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com