


- Billerud reported third quarter 2026 sales of SEK 10,166 million and net income of SEK 212 million, with basic earnings per share from continuing operations at SEK 0.85.
- Across the first nine months of 2026, sales were SEK 29,825 million while the business shifted from prior net income to a net loss of SEK 71 million, highlighting pressure on year to date profitability despite the stronger single quarter.
- The focus now is on how Billerud's return to quarterly profit may influence its investment narrative in relation to packaging, costs and capacity.
Billerud Investment Narrative Recap
Billerud stock asks you to believe that packaging remains the key earnings engine over time, while legacy European paper capacity and pricing are kept in check through cost work and rationalisation. The third quarter return to profit, with SEK 212 million in net income, supports that case but does not erase the nine month loss. The near term story still hinges on mix improvement from higher value packaging, disciplined capital spending and reliable cash generation.
The biggest swing factor right now is whether Project Evolution in North America and the fixed cost program translate into visibly stronger margins despite weaker year to date figures. The main risk is that European overcapacity, pricing pressure and higher carbon and energy related charges eat into those savings, leaving reported profitability stuck at low levels and limiting flexibility on dividend and future investments.
The recent earnings announcement for the third quarter and nine month period is the clearest reference point for these catalysts. Sales of SEK 10,166 million in the quarter and SEK 29,825 million year to date show that Billerud still has scale, while the move from a quarterly loss a year ago to a profit this time gives investors something more tangible to track against the efficiency story.
At the same time, the SEK 71 million net loss over the first nine months underlines that the cost base and European exposure remain a work in progress. For anyone watching catalysts like Project Evolution, the fixed cost saving plan and pulpwood cost relief, this set of results effectively becomes a baseline to judge whether those efforts start to show up consistently in earnings, or whether input cost swings and soft demand continue to cap progress.
Billerud's current analyst narrative centers on revenues reaching SEK 43.5b and earnings of SEK 2.8b by 2029, based on assumed 3.5% yearly revenue growth and an earnings increase of roughly SEK 2.6b from current earnings of SEK 233.0m.
Uncover how Billerud's fair value indicates a 9% potential upside to its current price before sentiment closes that gap.
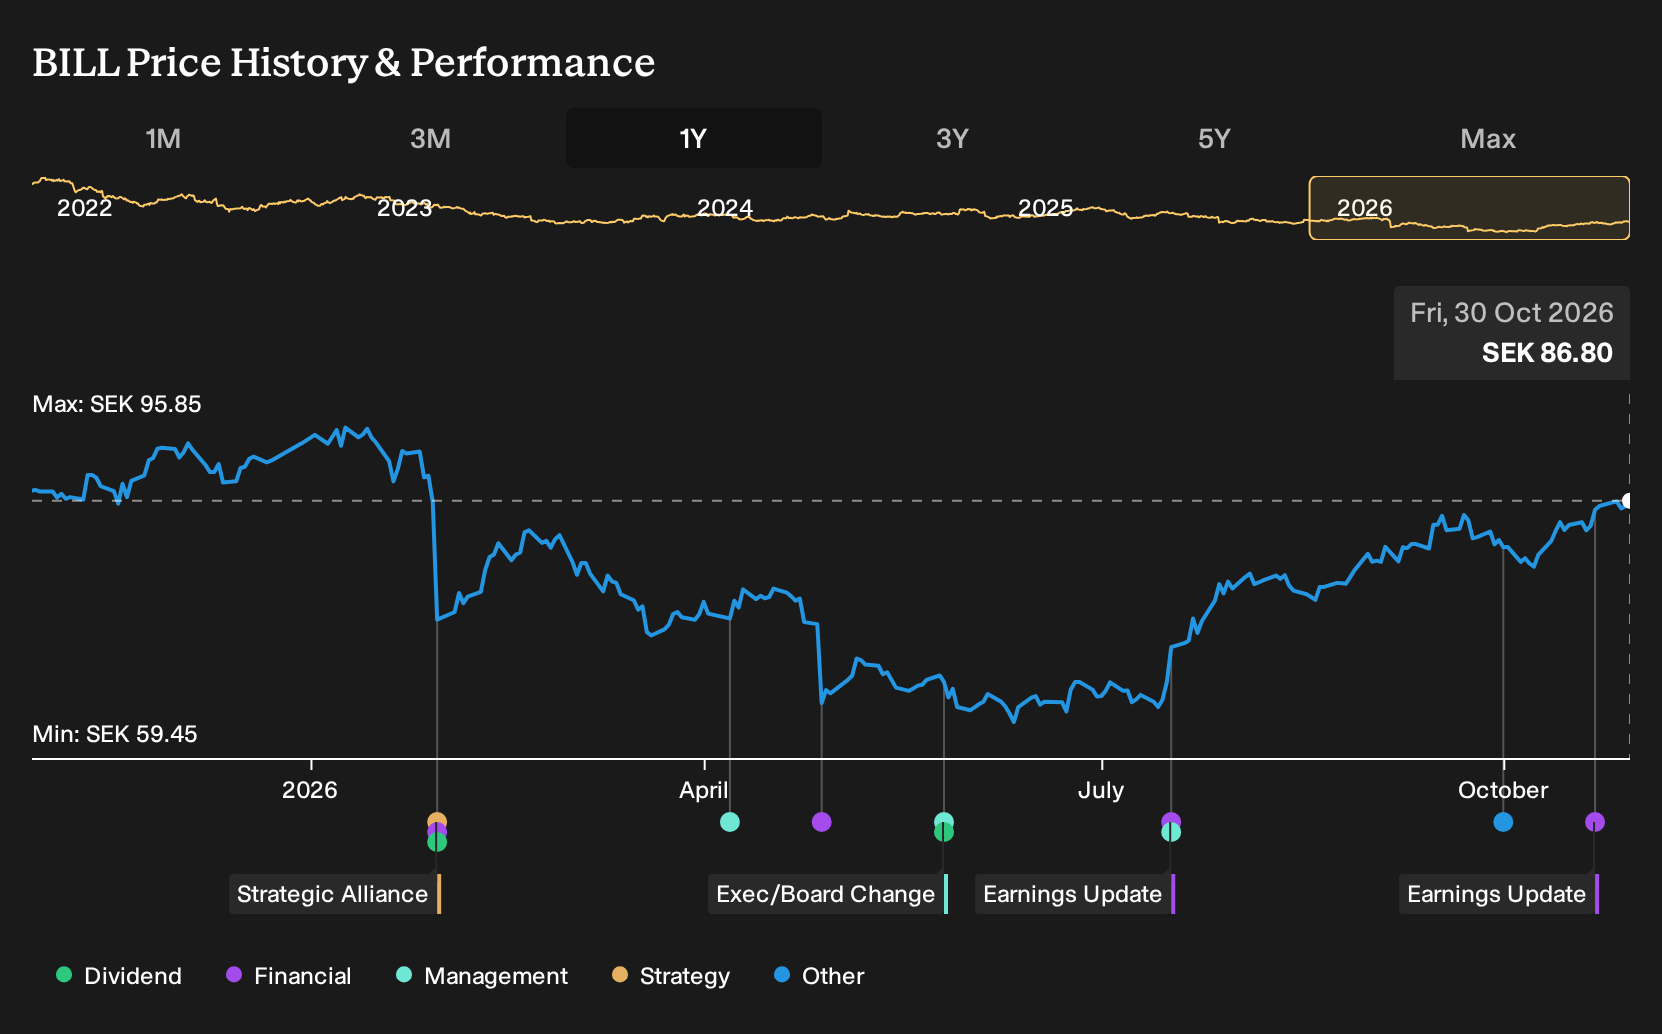
Exploring Other Perspectives
The lowest analysts put much more weight on European overcapacity risk. Before this earnings release they were working with revenue around SEK 40.8b and earnings near SEK 2.0b by 2029, versus the higher SEK 43.5b and SEK 2.8b consensus. Use this quarter from Billerud as a fresh lens and compare both stories for yourself.
Explore another Billerud fair value estimate, including one that suggests it could be worth just SEK94.86.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Billerud research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Billerud. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Billerud's overall financial health at a glance.
Looking for more Billerud-like investment ideas?
If the Billerud story has you thinking about where fundamentals, balance sheet strength and future potential line up, it can help to widen the lens and compare it with other stocks facing their own mix of catalysts and challenges.
- For investors who care most about financial resilience and low leverage, start with companies on the list of solid balance sheet and fundamentals (203 results) to see which businesses pair steady finances with room for growth.
- If capital protection ranks high on your list, focus on the 218 resilient stocks with low risk scores to surface companies that score well on stability and downside control.
- When you want to look beyond widely followed tickers, check out the 602 high quality undiscovered gems that combine solid fundamentals with less crowded investor attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com