


- Tokuyama reported half-year results for the period ended 30 September 2026 with sales of ¥178,676 million, net income of ¥9,981 million and basic earnings per share from continuing operations of ¥139.26.
- Sales were higher than the prior-year period while net income and earnings per share were lower, which points to pressure somewhere between Tokuyama's cost base, pricing, and product mix.
- The focus now shifts to how Tokuyama's higher sales but lower earnings might reshape the longer term investment narrative around the business.
See how Tokuyama's earnings reset compares with other industrials under profit pressure by reviewing our curated list of 15 high quality undervalued stocks.
What Is Tokuyama's Investment Narrative?
The big picture for Tokuyama is simple. You need to believe this is an industrial group that can convert a broad chemicals and materials portfolio into reasonably steady cash flows over time, even with cyclical swings in cement and electronics. Recent half year earnings show higher sales but softer profit and earnings per share, which points straight to input costs, selling prices, or mix working against it. That does not break the story, but it does remind you that execution on costs and pricing really matters here.
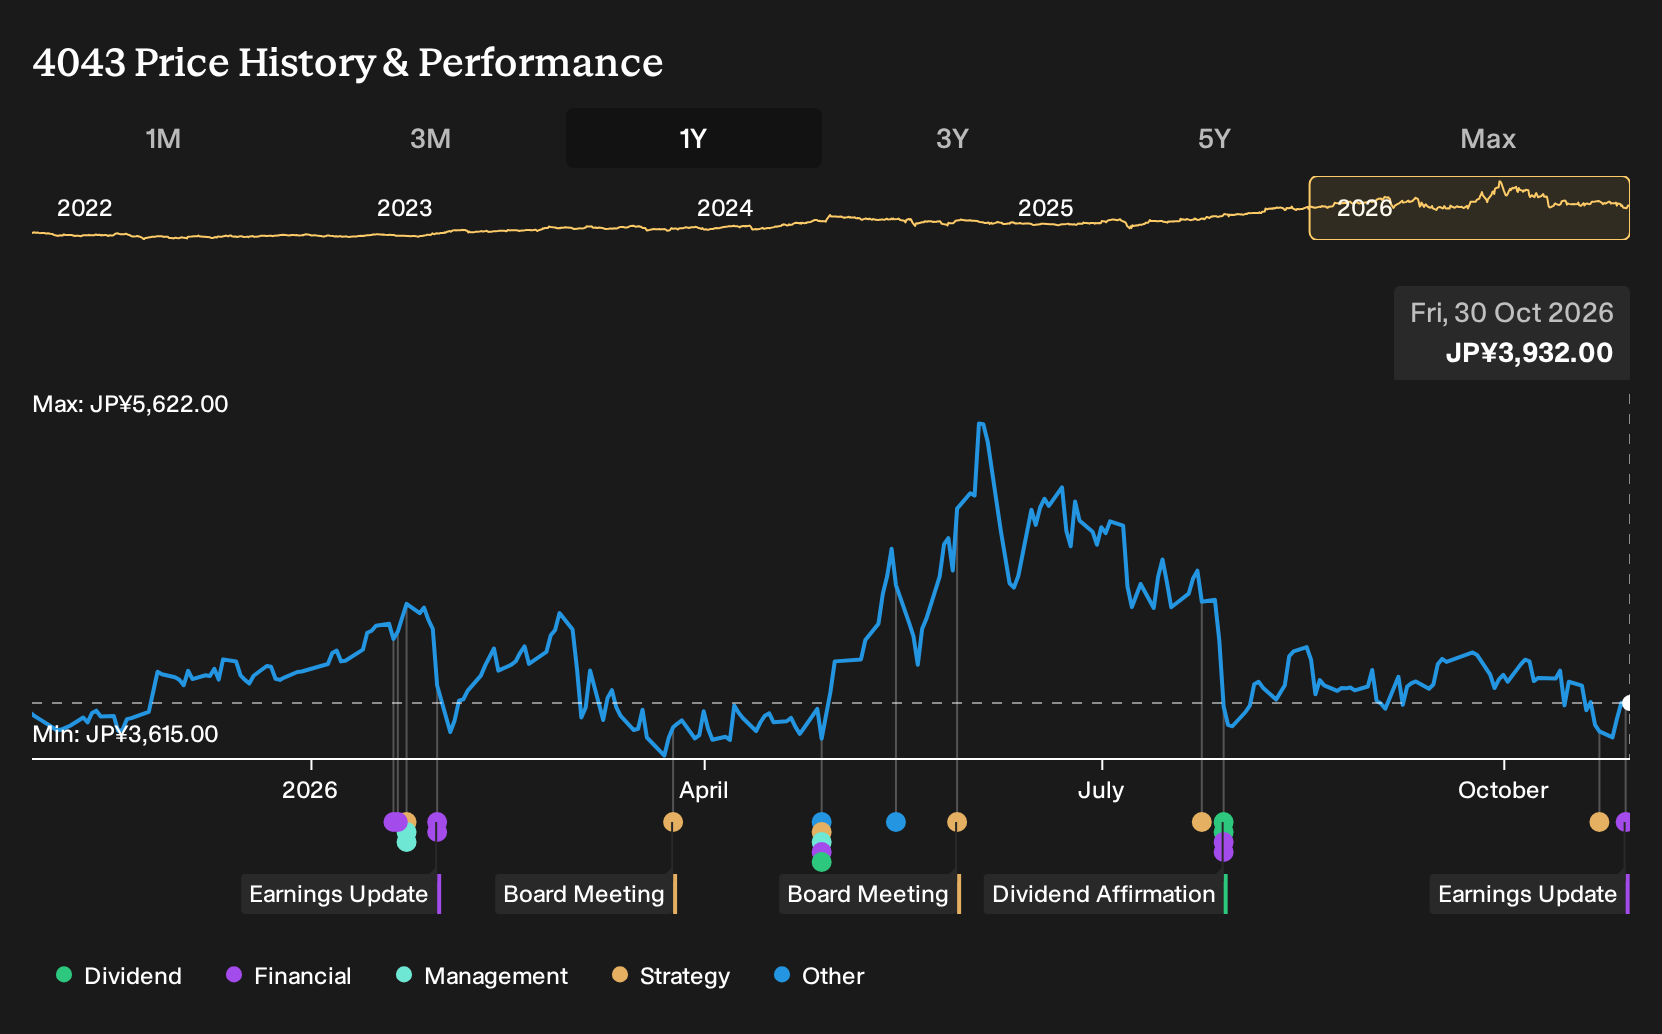
The parallel thread is capital allocation. Management is weighing a merger structure at board level, and that could reshape how Tokuyama deploys cash across its cement, chemical products, and electronics oriented lines. In the short term, the merger discussion and earnings reset sit alongside a share price that has risen over the past week but is still down year to date. Analyst targets and discount metrics only matter if the business can defend margins and keep funding its capital intensive assets without stretching the balance sheet.
Even so, there is one operational pressure point that could quietly become the real swing factor for Tokuyama if...
There's only one way to know the right time to buy, sell or hold Tokuyama. Head to Simply Wall St's company report for the latest analysis of Tokuyama's Fair Value.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Tokuyama research is our analysis highlighting 6 key rewards that could impact your investment decision.
- See our latest analysis for Tokuyama. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tokuyama's overall financial health at a glance.
Looking For More Investment Ideas Beyond Tokuyama?
If Tokuyama has sharpened your focus on earnings quality and balance sheet resilience, it can help to compare it with other companies that have similar strengths or very different risk profiles. The Simply Wall St Screener lets you filter by fundamentals, dividends, or financial strength so you can build a wider watchlist that matches your own approach.
- If capital preservation comes first for you, start with companies that score well on resilience and risk by reviewing our 24 resilient stocks with low risk scores.
- If income is a priority, scan for payouts that clear your yield hurdle by checking out a curated set of 27 dividend fortresses.
- If you are hunting for underfollowed opportunities backed by solid numbers, broaden your research list with a focused group of 71 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com