


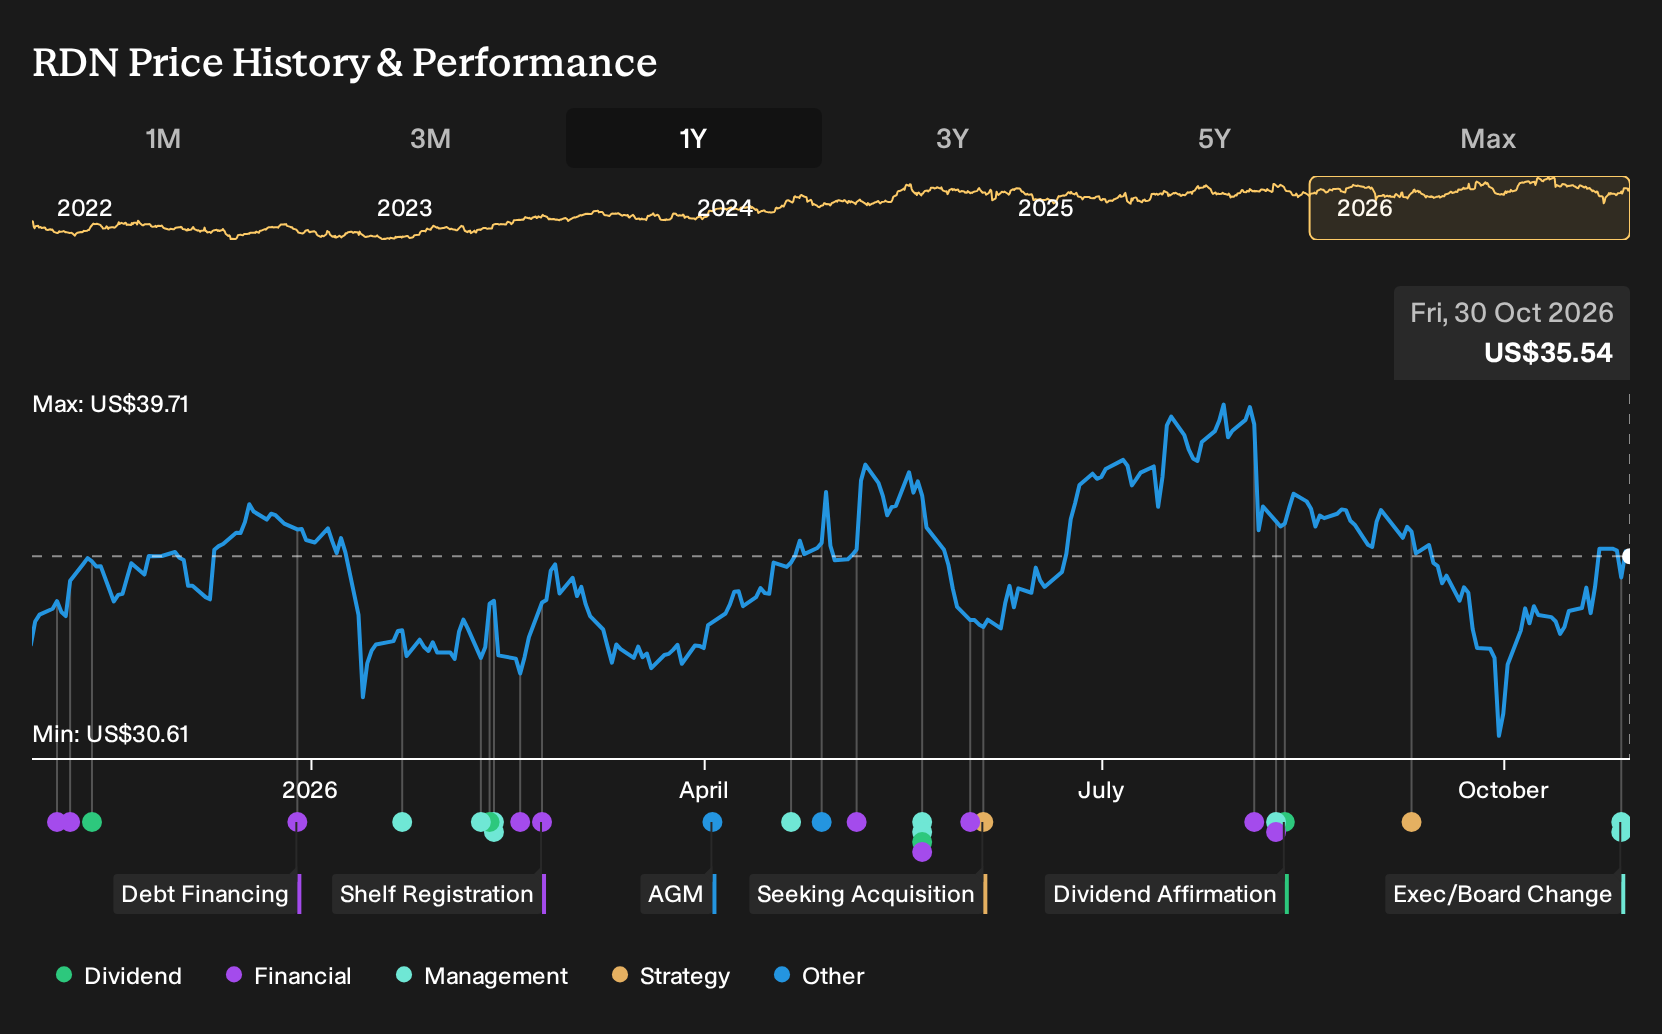
- Radian Group reported that Dan Kobell has been appointed Chief Financial Officer and Courtney Smith Goodrich has joined as Chief Information Officer, formalizing leadership over finance and technology following Kobell’s interim CFO tenure and bringing experience from Fannie Mae, Wells Fargo, and JPMorgan Chase into the organization.
- The leadership reshuffle, including new oversight of capital allocation, risk management, and system modernization, signals that Radian Group is putting senior decision-makers directly on core operating levers such as underwriting discipline, data use, and long-term financial flexibility.
- Attention now turns to how Radian Group's refreshed finance and technology leadership might reshape the investment narrative around capital discipline and modernization.
What Is Radian Group's Investment Narrative?
To own Radian Group, you need to believe this is a steady mortgage risk platform that can keep underwriting discipline tight while using technology and data to protect returns. The business leans on mortgage insurers and credit investors who value consistent risk transfer more than headline growth. Earnings and revenue are forecast to grow, but not at a rapid clip, so execution on pricing, loss ratios, and capital intensity does more work than raw top line expansion.
The recent appointments matter most around those execution levers. A permanent CFO with a mandate for disciplined capital allocation and a CIO focused on system modernization and analytics both point to a push on decision speed and risk insight rather than a dramatic near term earnings catalyst. The bigger near term watchpoints stay the same, including softer profit margins versus last year and underwriting results through the next credit cycle.
That said, there is a less obvious vulnerability in Radian Group's story once you look closely at how its funding mix and return profile interact with ...
There's only one way to know the right time to buy, sell or hold Radian Group. Head to Simply Wall St's company report for the latest analysis of Radian Group's Fair Value.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Radian Group research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Radian Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Radian Group's overall financial health at a glance.
Looking for more investment ideas beyond Radian Group?
Once you have formed a view on Radian Group, it can help to line it up against a broader watchlist of potential opportunities that fit different portfolio roles.
Use the Simply Wall St Screener to quickly scan for other stocks that match the kind of quality, income, or resilience profile you want next.
- If you care most about resilient balance sheets and durable fundamentals, start with this curated list of solid balance sheet and fundamentals (25 results) that can help you focus on financially grounded businesses.
- For readers hunting for mispriced opportunities with strong underlying quality, filter ideas using our focused 29 high quality undervalued stocks that zeroes in on companies where fundamentals and price look out of sync.
- Income oriented investors who value consistent payouts can sift for yield opportunities through a targeted 5 dividend fortresses that highlights higher yielding stocks with the potential to complement Radian Group in a diversified portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com