


- Adma Biologics is drawing increased attention ahead of its November 4, 2026 earnings release, with consensus forecasts pointing to year over year gains in both EPS and revenue, supported by expectations for continued operational leverage.
- The steady Zacks Rank #3 (Hold), alongside an average brokerage recommendation of 2.00, highlights a gap between upbeat earnings expectations and more cautious aggregate analyst positioning on the business.
- We will now see how Adma Biologics' investment narrative might be affected by growing earnings expectations and heightened investor focus.
Scan beyond ADMA Biologics by reviewing hand-picked peers with similar earnings momentum using our 29 high quality undervalued stocks.
ADMA Biologics Investment Narrative Recap
To own ADMA Biologics, you need to believe the business can keep turning its concentrated plasma portfolio into durable cash generation, even as the standard immunoglobulin market stays competitive. The near term story still leans on ASCENIV adoption, high gross margins and disciplined use of largely fixed manufacturing assets.
The November 4 earnings expectations for higher EPS and revenue raise the bar on execution but do not change the core near term swing factors. The key catalyst remains proof that ASCENIV led mix and yield improvements support earnings quality. The biggest risk is product specific pricing and volume pressure spilling beyond BIVIGAM.
The clearest recent datapoint is the forecast for current quarter EPS of US$0.19 and sales growth of 4.2% year over year. Those figures put operational delivery under closer scrutiny. Strong reported profitability metrics, including a 33% net margin and 41.4% return on equity, already signal that efficiency is central to the thesis.
Consensus now points to EPS growth of 18.75% year over year for the upcoming print, while the Zacks Rank sits at #3 (Hold). For you, the focus is less on the label and more on whether ADMA Biologics can keep translating yield gains, ASCENIV adoption and plasma access into resilient earnings in a crowded IG market.
ADMA Biologics' current analyst framework points to revenues of US$783.1 million and earnings of US$317.5 million by 2029. This outlook is built on an assumed 15.2% yearly increase in revenue and an earnings uplift of about US$148.5 million from US$169.0 million today.
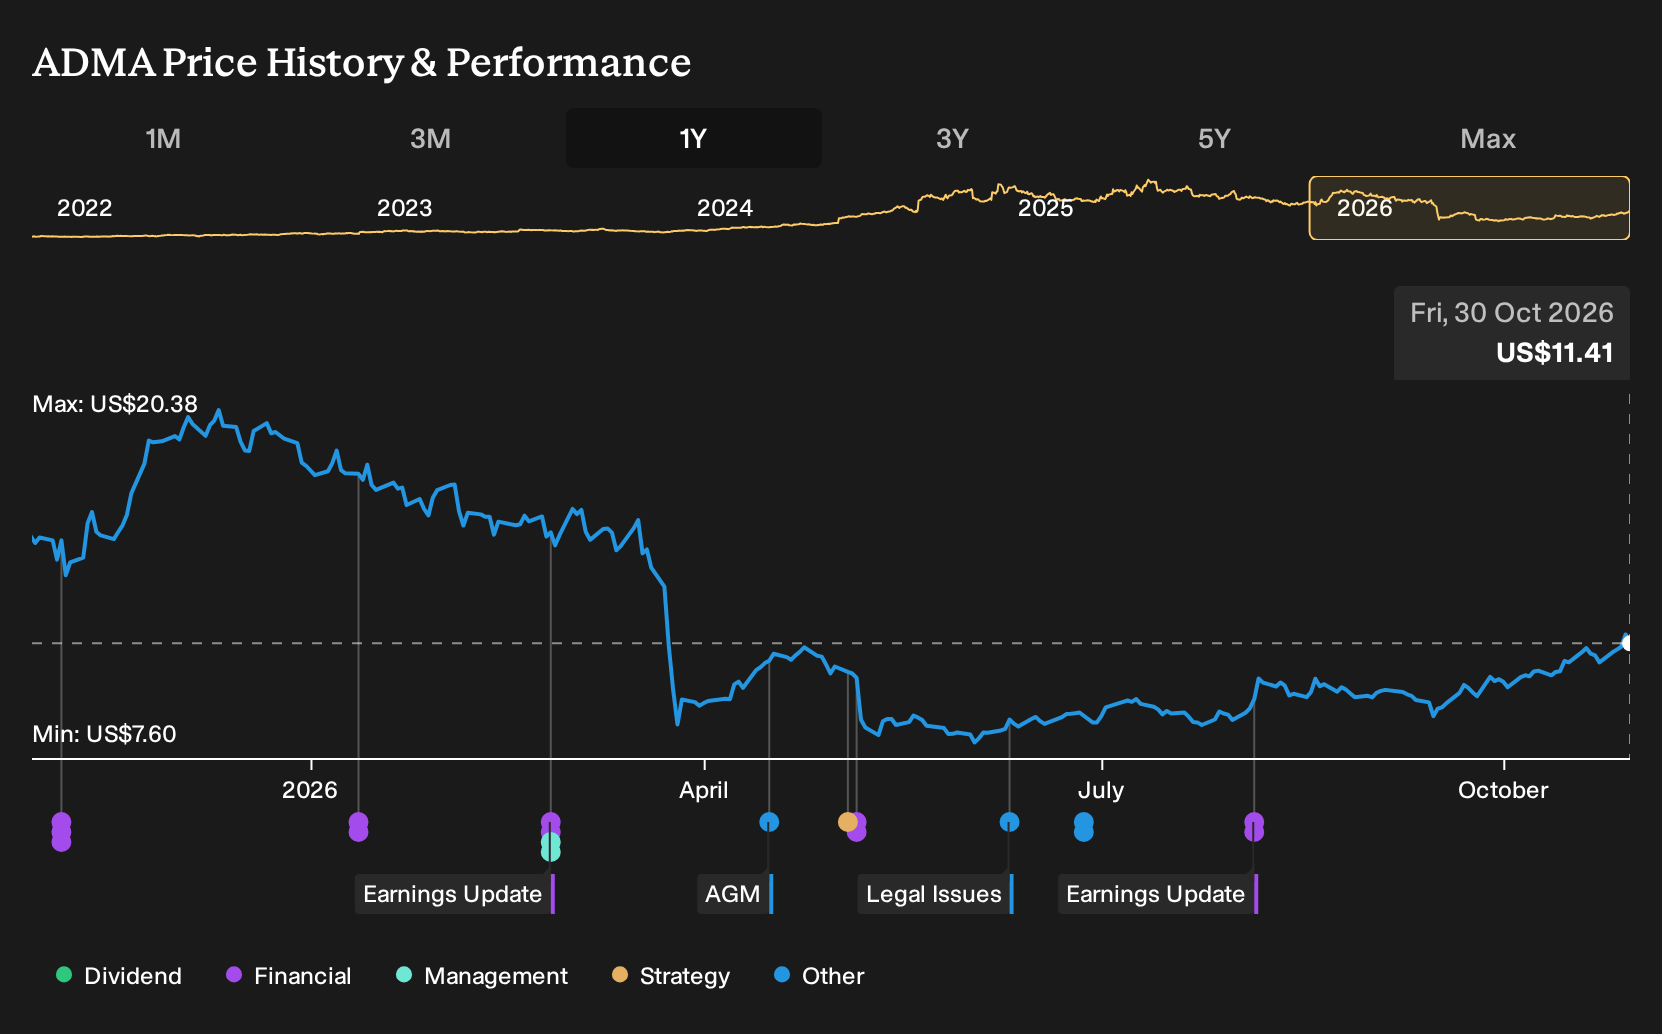
Uncover why ADMA Biologics' fair value indicates a 49% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
For a different angle on ADMA Biologics, focus on the bullish catalyst around ASCENIV mix and earnings power. The most optimistic analysts were penciling in about US$899.5 million of revenue and US$365.3 million of earnings by 2029. That is far above consensus, and both narratives were set before this latest earnings focus, so you may see estimates shift as new information lands.
Explore 6 other ADMA Biologics fair value estimates, including one that suggests potential upside of up to 219% from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ADMA Biologics research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for ADMA Biologics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ADMA Biologics' overall financial health at a glance.
Looking For More Investment Ideas Beyond ADMA Biologics?
Once you have formed a view on ADMA Biologics, it can help to broaden the watchlist with companies that line up with the type of risk and return profile you prefer. The Simply Wall St Screener lets you filter quickly so you spend your time assessing fundamentals rather than hunting for tickers.
- If you want potential mispricings with quality fundamentals, start with a focused set of 29 high quality undervalued stocks that already clear several balance sheet and cash flow checks.
- For investors who care most about resilience, narrow your search to 30 resilient stocks with low risk scores that score well on volatility and financial risk metrics.
- If capital preservation and financial strength come first for you, build a shortlist from the list of solid balance sheet and fundamentals (25 results) so you can concentrate on businesses with robust funding profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com