


Missiles are suddenly back in the spotlight, as Washington weighs how to respond to faster, cheaper hypersonic hardware from rivals and startups like Castelion that are racing to win Pentagon dollars. For investors, that shift could quietly reshape where defense money flows next and which listed contractors benefit from higher volume, lower cost munitions. This piece examines how that story connects to three U.S. stocks that are exposed to this hypersonic news cycle.
The stocks profiled below are just a starter set. The full screen on Simply Wall St has surfaced 13 more U.S. precision missile and munitions manufacturers with equally compelling stories that are not covered here. If you want to identify potential high conviction exposures in this corner of defense, go straight to the U.S. Precision Missile & Munitions Manufacturers screener
Voyager Technologies (VOYG)
Overview: Voyager Technologies is a defense and space contractor that supplies propulsion, guidance, and mission-critical electronics used in precision weapons and orbital systems.
Operations: Voyager reports segment-level revenue of about $178 million, with approximately $161 million generated in the United States and the balance from adjustments.
Market Cap: US$1.70b
Voyager Technologies matters in this hypersonic-focused screen because its propulsion and guidance hardware sits inside the very missiles the Pentagon wants to buy in greater volume.
"Starlab is the Future of LEO. NASA Validation: Voyager has secured hundreds of millions in NASA funding to replace the ISS."
What happens to Voyager Technologies’ long-term cash generation if one quiet assumption about how those mission systems are procured starts to shift?
If that procurement shift is what you are really focused on, read the full narrative for Voyager Technologies to see how hypersonic demand could reshape Voyager Technologies’ risk and opportunity profile.

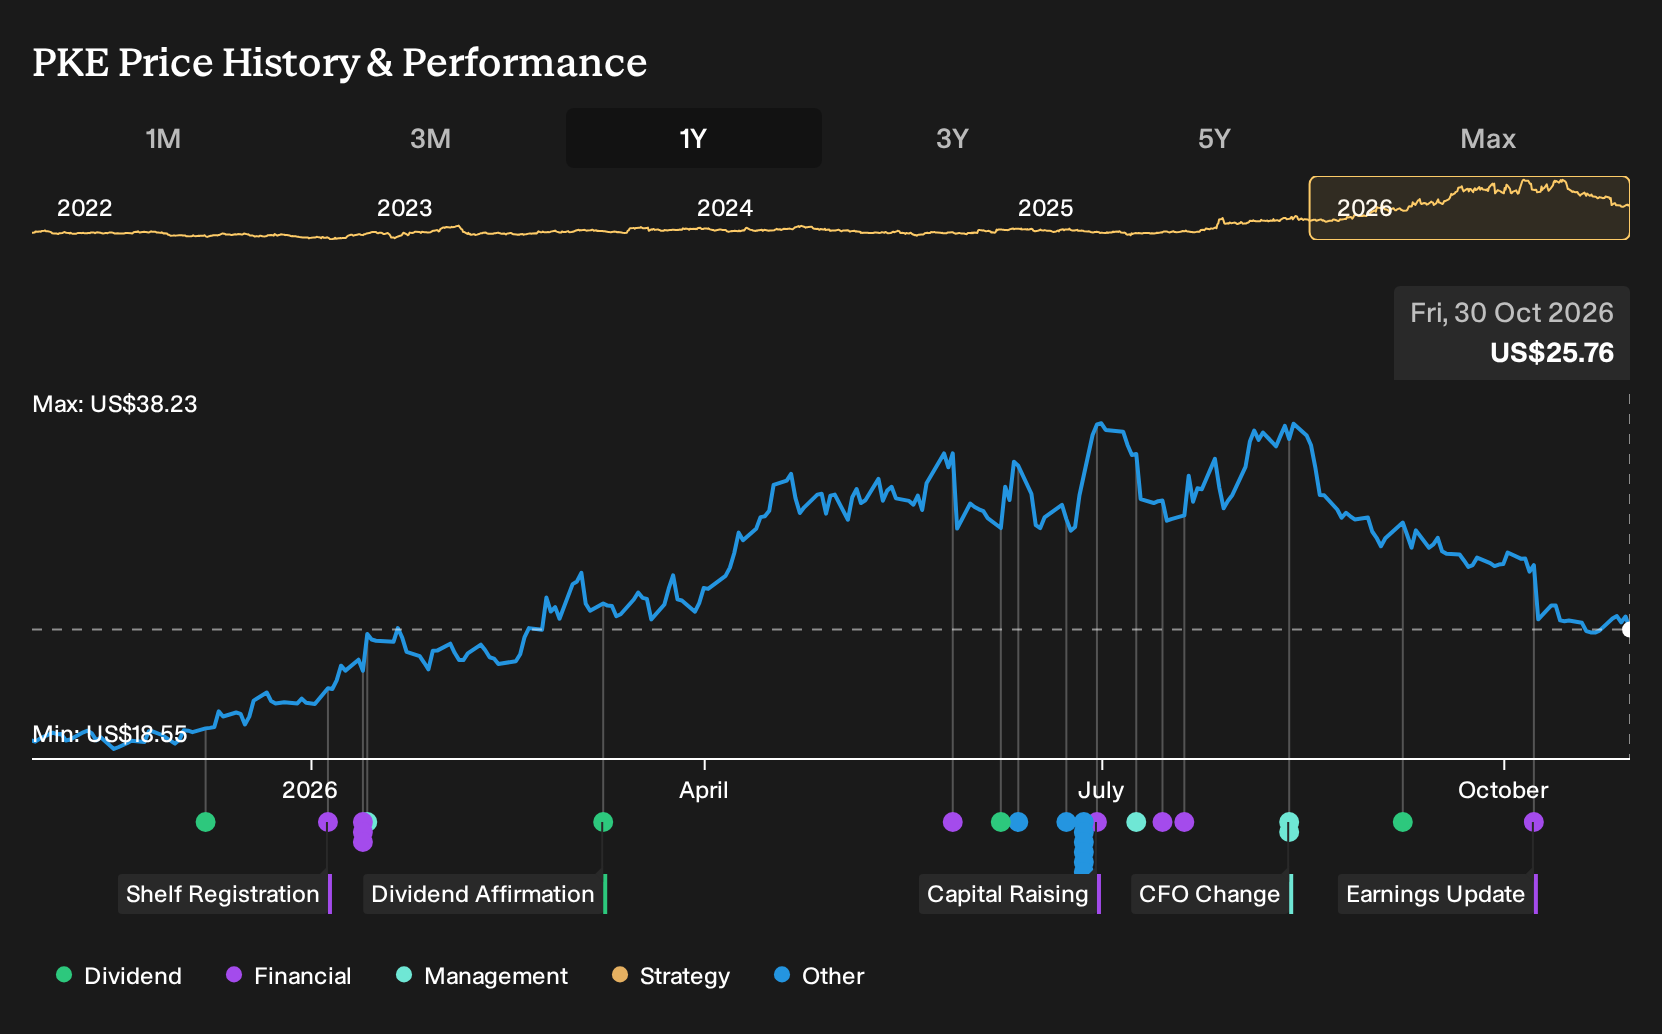
Park Aerospace (PKE)
Overview: Park Aerospace develops advanced composite materials and parts used in aircraft and rocket structures, including components that can support precision missile systems.
Operations: Park Aerospace generates about $80.6 million from Aerospace & Defense materials and parts, with roughly $76.5 million of that coming from North America.
Market Cap: US$585 million
Park Aerospace matters for this hypersonic and high volume munitions theme because its composite materials feed directly into missile bodies and thermal protection where reliability, weight and throughput all suddenly matter more.
"Management once described a Lockheed agreement with the Department of Defense to raise PAC-3 MSE interceptor production capacity “from 600 per year to 2,000,” with language delivered with visible enthusiasm and called “unheard of” and “incredible.”
What happens to Park Aerospace’s earnings power if that kind of missile build rate shift collides with one quiet assumption about program sourcing?
That quiet shift starts with how missile programs are actually allocated, which is exactly what the full narrative for Park Aerospace unpacks, including where accelerating demand could still surprise.
Curtiss-Wright (CW)
Overview: Curtiss-Wright supplies engineered electronics, actuation hardware, and nuclear systems that plug into U.S. aerospace, defense, and power programs.
Operations: Curtiss-Wright generates about US$1.6b from Naval & Power, US$1.0b from Aerospace & Industrial, and US$1.0b from Defense Electronics annually.
Market Cap: US$18.35b
Curtiss-Wright matters in this precision missile and munitions screen because its Tier 2 and Tier 3 hardware and computing gear sit inside many of the platforms that hypersonic and high volume missile programs rely on.
"The global nuclear resurgence remains in play for Curtiss-Wright. Management now expects the commercial nuclear business to roughly double from its 2023 base by 2028 and to reach about US$1.5b in annual revenue by the mid 2030s, with potential AP1000 and SMR content supporting a long-cycle uplift in segment revenue and margins that is not yet fully reflected in near term guidance."
What happens to Curtiss-Wright’s long run earnings power if one quiet assumption about how this nuclear and defense mix evolves starts to shift?
That shift is where Curtiss-Wright gets interesting, so read the full narrative for Curtiss-Wright to see how hypersonic demand and nuclear spend could be quietly accelerating the story.

Seeking Fresh Alternatives Beyond Defense?
Fresh opportunities move fast. Breakout stories gain momentum, under the radar for now, then get caught once the crowd arrives. Scan these ideas while it matters and get in early.
- Lock onto resilient balance sheets before momentum traders notice by scanning the list of solid balance sheet and fundamentals (25 results) curated from cash rich, financially disciplined businesses that can keep funding growth even when markets turn impatient.
- Ride the next wave of automation as factories, logistics hubs, and warehouses upgrade, using the 96 robotics and automation stocks to zero in on curated enablers of real world productivity gains and cost drops.
- Position ahead of potential power grid overhauls by running the 39 power grid technology and infrastructure stocks to spot focused companies tied to transmission upgrades, grid hardening, and smarter electricity infrastructure while the story is still forming.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com