


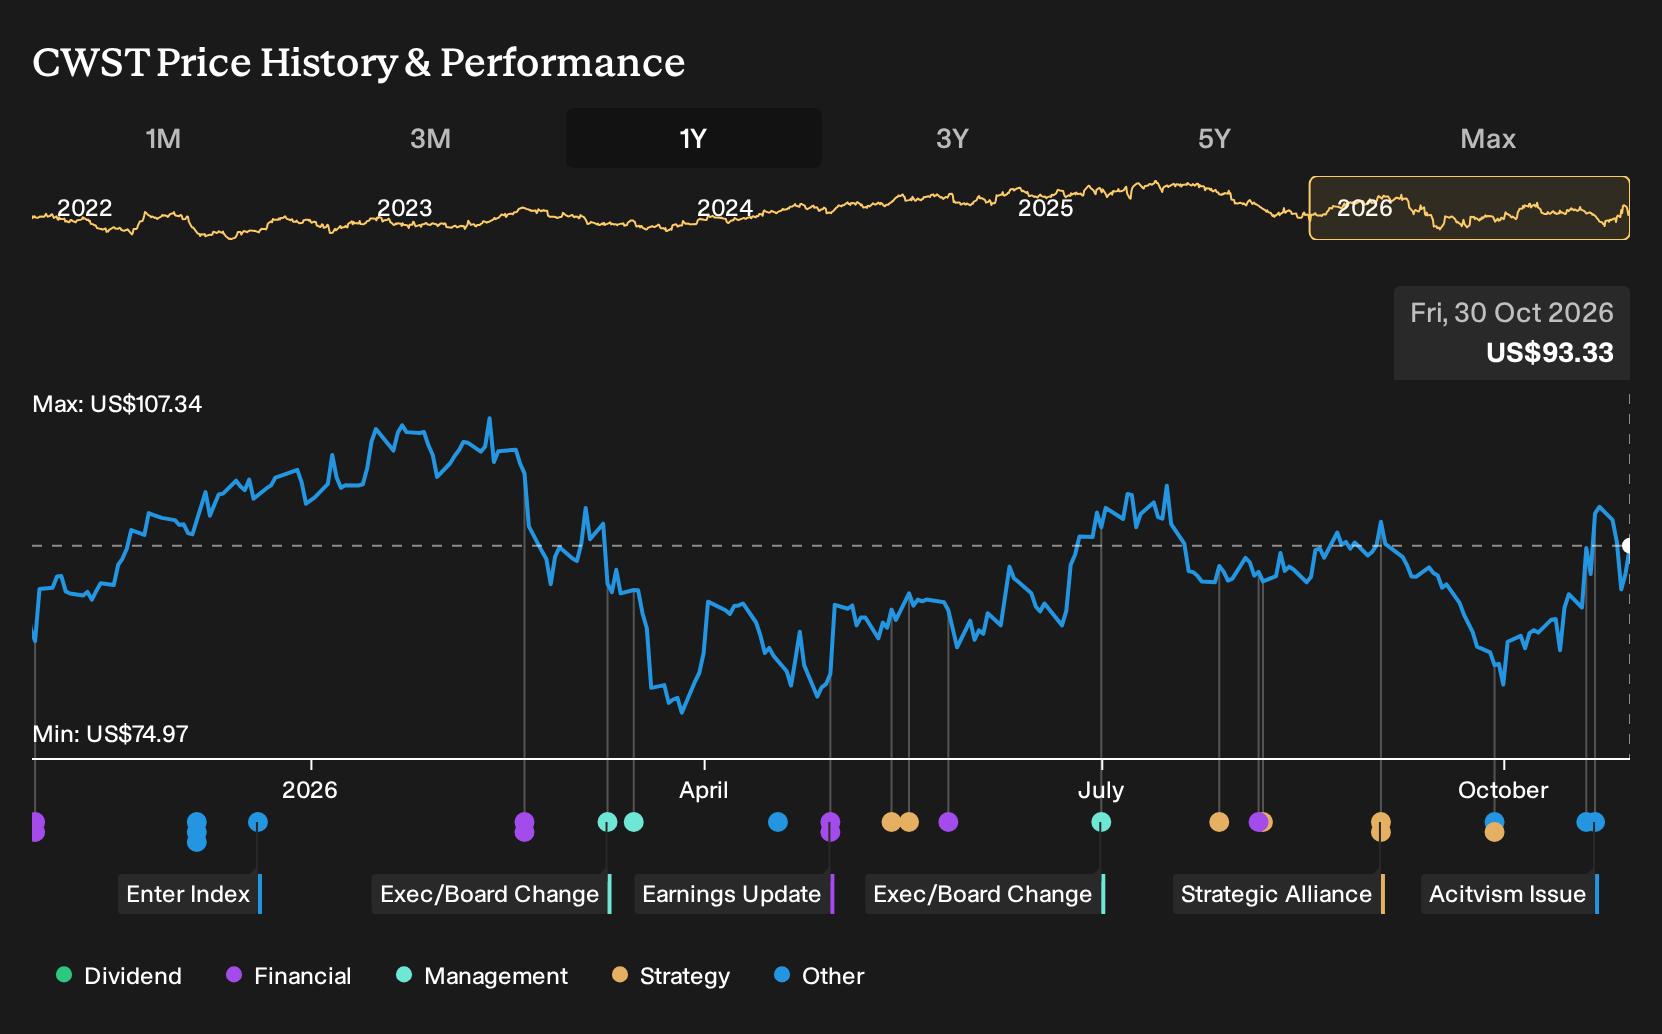
- In October 2026, Jana Partners LLC revealed a new position in Casella Waste Systems and publicly pushed for higher EBITDA margins, better capital efficiency, a performance-improvement consultant, and executive pay tied more tightly to shareholder returns by 2029.
- The activist focus on a roughly 27% EBITDA margin target and return on capital puts Casella Waste Systems' cost structure and acquisition-heavy playbook under fresh scrutiny.
- The next question is what this activism-driven EBITDA push could mean for Casella Waste Systems' existing investment narrative built on consolidation and efficiency gains.
Apply the same margin and capital-discipline lens Jana is bringing to Casella Waste Systems and scan our hand picked list of solid balance sheet and fundamentals (25 results) for potential ideas built on financial resilience.
Casella Waste Systems Investment Narrative Recap
To own Casella Waste Systems, you need to believe that its consolidation model, landfill assets and recycling and organics platform can eventually support healthier profitability than the recent 0.3% net margin. Jana Partners is effectively stress testing that view. The near term swing factor is whether cost cuts, automation and Mid Atlantic integration work can start to lift EBITDA without disrupting service quality.
The biggest operational risk is that acquisition integration, one off items and cost inflation keep earnings weak while interest costs remain hard to cover. Jana’s 27% EBITDA margin push raises the bar, but it does not change the core near term concern. Execution on efficiency and pricing still matters more than activism headlines.
The Jana Partners campaign itself is the key new development. Public calls for a roughly 27% EBITDA margin, better return on capital and tighter pay alignment with shareholder outcomes put Casella Waste Systems’ acquisition heavy approach and cost base under closer scrutiny. That scrutiny intersects directly with earlier worries about compressed operating margins and earnings pressure.
If management responds with clearer cost targets, capital allocation discipline and potentially a performance improvement consultant, that could influence how investors view the existing catalysts, from landfill internalization to automation savings and renewable natural gas projects. If integration issues, one off charges and interest coverage concerns persist, the Jana plan could instead highlight how tight the current operating equation already is.
Casella Waste Systems' narrative projects US$2.5b revenue and US$70.5m earnings by 2029. This assumes 8.4% yearly revenue growth and an earnings increase of about US$64.8m from US$5.7m today.
Uncover why Casella Waste Systems' fair value indicates a 14% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between about US$106.50 and US$158.74, which shows how far private investors can spread on Casella Waste Systems. You now have Jana’s 27% EBITDA margin push on one side and ongoing integration and cost pressure questions on the other. Use that gap to test your own view.
Explore another Casella Waste Systems fair value estimate, including one that suggests it could be worth just $106.50.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Casella Waste Systems research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Casella Waste Systems. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, making it easy to evaluate Casella Waste Systems' overall financial health at a glance.
Looking for more Casella Waste Systems sized ideas?
Once you have a view on Casella Waste Systems, it can help to line it up against a broader watchlist so you are not anchored to just one story. The Simply Wall St Screener is built for exactly that kind of side by side comparison.
- If capital preservation is front of mind, start with a group of companies that screen as more resilient by reviewing 30 resilient stocks with low risk scores.
- If income matters more to you, scan companies with stronger yields and more robust distributions through 5 dividend fortresses.
- If you want to focus on quality that the market may be overlooking, use 18 high quality undiscovered gems to surface lesser known stocks with solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com